

RELX Put Its Legal AI Inside the Renewal Price Instead of Giving It Away
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The cheapest way to defend a subscription against a chatbot is to hand the chatbot features over free. RELX's half-year disclosure shows LexisNexis did the opposite, and customers signed: roughly nine in ten dollars of new sales value and about three-quarters of renewal value now run through the Lexis+ with Protégé package.
Legal was the group's fastest-growing division in the first half, underlying revenue up 10% to £959m with divisional adjusted operating profit up 13%, and the group adjusted margin widened to 35.5% from 34.8% — not by starving content and technology, since management puts token cost at under 1% of the cost base. Thomson Reuters ran the same play on Westlaw and CoCounsel, with Legal Professionals organic revenue up 10% and 97% of it recurring.
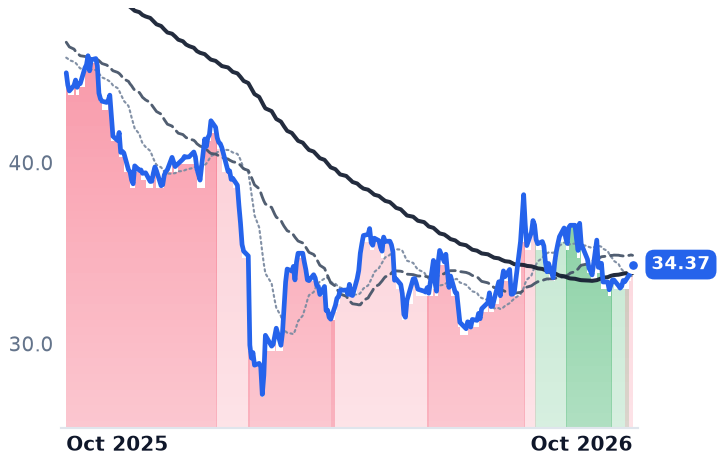
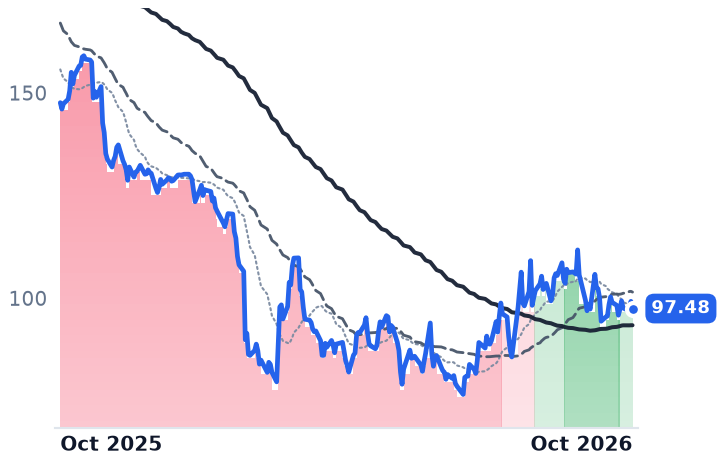
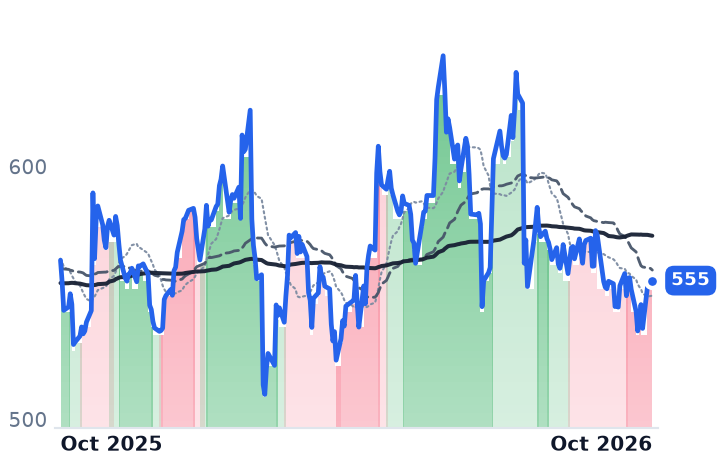
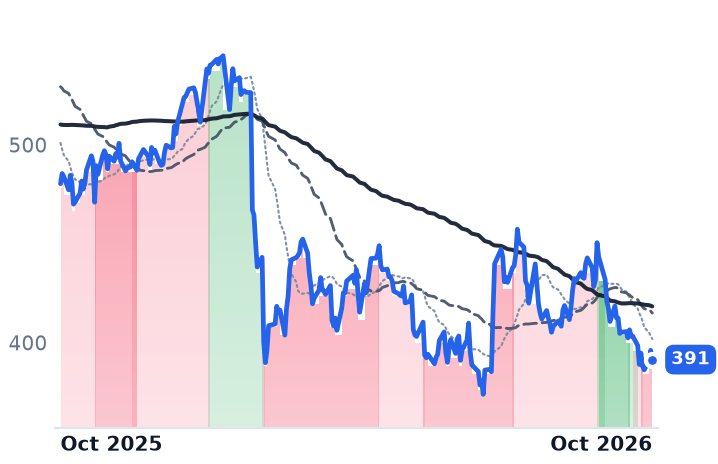
Both businesses accelerated through a twelve-month de-rating of 24.4% and 35.7%. What neither discloses is a renewal-retention rate.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
RELX | RELX | Information & Analytics Platforms | 🌱 Emerging Bull | −0.9% | −23.6% |
TRI | Thomson Reuters | Information & Analytics Platforms | 🌱 Emerging Bull | −2.0% | −34.0% |
| Compared against · context, not the story | |||||
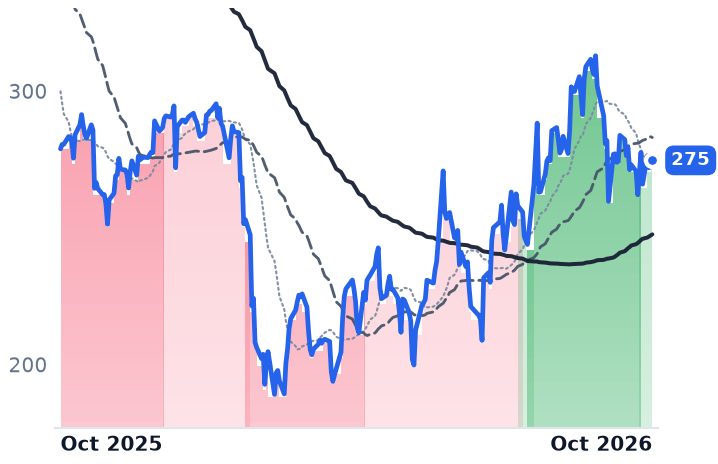
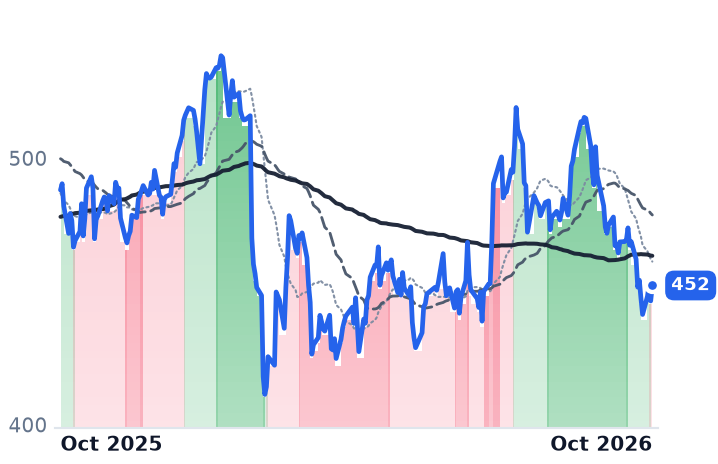
FDS | FactSet Research Systems | Investment Data & Analytics | 🌱 Emerging Bull | −5.6% | −1.5% |
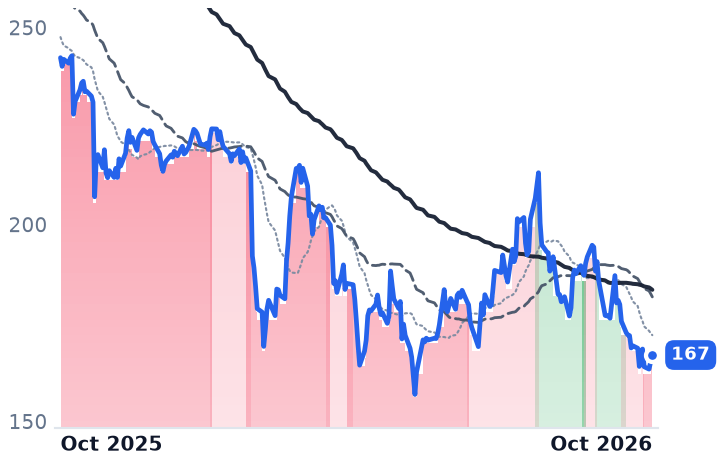
VRSK | Verisk Analytics | Software - Services | 🔴 Cont. Bear | −5.7% | −31.2% |
MSCI | MSCI | Investment Data & Analytics | ⚠️ Emerging Bear | +0.1% | −1.4% |
SPGI | S&P Global | Credit Ratings | 🔴 Cont. Bear | −9.4% | −18.5% |
MCO | Moody's | Credit Ratings | 🌱 Emerging Bull | −6.2% | −7.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RELX | $60.3B | 20.6x | 24.6x | 4.7x | 6.0x | 7.5x | 9.6x | 13.4x | 6.4% |
TRI | $42.6B | 26.1x | 22.3x | 5.4x | 5.3x | 8.2x | 8.0x | 13.7x | 5.2% |
FDS | $9.7B | 18.7x | 13.9x | 3.9x | 3.7x | 7.8x | 7.3x | 12.1x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRSK | $22.3B | 26.3x | 22.2x | 7.1x | 6.9x | 10.5x | 10.2x | 15.7x | 5.5% |
MSCI | $41.1B | 31.1x | 28.7x | 12.3x | 11.7x | 14.9x | 14.1x | 23.1x | 3.9% |
SPGI | $119.3B | 25.1x | 20.5x | 7.6x | 7.2x | 10.8x | 10.3x | 16.8x | 4.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MCO | $74.9B | 30.4x | 25.7x | 9.5x | 9.1x | 13.7x | 13.0x | 20.4x | 4.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RELX | Revenue | +2.7% | +6.5% | +7.6% |
| EPS | +8.7% | +10.8% | +12.0% | |
TRI | Revenue | +5.8% | +7.2% | +8.6% |
| EPS | +9.4% | +14.2% | +13.1% | |
FDS | Revenue | +6.7% | +6.0% | +6.0% |
| EPS | +4.5% | +10.1% | +10.3% | |
VRSK | Revenue | +4.9% | +6.7% | +6.8% |
| EPS | +11.1% | +12.7% | +12.3% | |
MSCI | Revenue | +12.0% | +8.7% | +8.6% |
| EPS | +14.5% | +14.0% | +13.7% | |
SPGI | Revenue | +7.7% | +7.2% | +7.3% |
| EPS | +9.9% | +13.3% | +14.0% | |
MCO | Revenue | +7.2% | +7.6% | +7.7% |
| EPS | +13.5% | +11.6% | +11.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
RELX has put the generative-artificial-intelligence layer of its legal business inside the renewal price. The London group, which sells research and decision tools to law firms, insurers, scientists and governments, disclosed in July that roughly 90% of the value of new LexisNexis sales now runs through Lexis+ with Protégé, its package for legal research, drafting and document analysis, and that about three-quarters of renewal value comes from the same product.
For a year the market treated LexisNexis and its rival Westlaw as the obvious casualties of machines that answer legal questions for nothing: RELX's American shares are down 24.4% over twelve months and Thomson Reuters' down 35.7%. The renewal line says the AI is the thing customers are paying more for. Legal was RELX's fastest-growing division in the first half of 2026, underlying revenue up 10% to £959m, a record for the division, with adjusted operating profit up 13%.
The uplift is a line on the invoice
The per-seat arithmetic shows where that comes from. A published cost comparison puts Westlaw Classic at $132.80 a month for a single state and $266.40 for all states plus federal, Lexis+ core research plans at $80 to $135 per user per month, and estimates all-in AI-layer seats on either platform at roughly $250 to $500 a seat a month.
The AI tier is not a feature folded into the old price; it is a multiple of it.
Chief executive Erik Engstrom told investors on the 23 July half-year call that the migration to Lexis+ with Protégé is "a necessary starting point for the future growth opportunity for the next decade or so," likening it to the industry's earlier move from print to electronic products.
Margins are not paying for the migration. RELX's group adjusted operating margin widened to 35.5% from 34.8% on underlying revenue growth of 7%, with management describing the cost of tokens as under 1% of the overall cost base and its ability to manage that cost for customers as a competitive advantage. Sterling reported growth was only 3%, because a strong pound took two points off the line: currency, with nothing visible in demand. Risk grew 8% underlying, scientific and medical publishing 6% and Exhibitions 6%, by the company's count.
Thomson Reuters charges for it too
The mirror image is in Toronto. Thomson Reuters, which sells workflow software and content to legal, tax and corporate-compliance professionals, grew second-quarter organic revenue 8%, with its three core professional segments up 10% organically and 83% of revenue, and raised its full-year outlook in August to about 8.0% total and organic growth, 9.5% to 10.0% for those three. Legal Professionals grew 10% organically with recurring revenue at 97% of the segment, led by Westlaw and CoCounsel; tax and accounting grew 8% organically on filing work that statute requires.
Its agentic CoCounsel Legal bundle became generally available in August, priced publicly only for firms up to ten attorneys, with 12% off for two-year and 18% off for three-year terms. The shares trade at 22.3x forward earnings against 26.1x trailing, the same forward multiple as Verisk, a peer in the same information group that grew revenue 4.4% last quarter.
Both stocks bottomed in midsummer, Thomson Reuters on 15 June and RELX on 1 July, and recovered 8.7% and 7.2% over three months before stalling. In the last thirty days RELX gave back 3.2% and Thomson Reuters 2.0%, while FactSet fell 9.4%, S&P Global 11.7% and Verisk 10.2% — a drawdown that followed FactSet's 30 September guidance for fiscal 2027 adjusted earnings of $19.25 to $19.65, below consensus, on organic subscription growth cut to 5% to 6.5%. FactSet sells workstations to the investment industry; a slower budget there says little about a law firm's research seat.
Retention is the number nobody prints
The fundamentals account for the summer recovery and then some. Two businesses accelerated and widened margins through a de-rating of roughly a quarter to a third, and the one leg of the bear case that was checkable, that AI would be surrendered free to hold seats, reads the other way at both. Seat counts are not obviously shrinking either: legal staffing data has Am Law 100 headcount up 3% since January 2023 and the second hundred up nearly 8%.
Three things stay open. Neither company disclosed a renewal-retention rate in this material, so the institutional stickiness the model implies is assumption rather than reported fact. Reuters' AI content licensing cannot be sized: chief executive Steve Hasker said in London on 12 May that the deals cover only archive text and are kept deliberately short so they must be renegotiated, and no terms are public. And consensus has Thomson Reuters' 2026 revenue at $7.97bn, about 6.6% growth, still short of the roughly 8% management guided in August.
The pitch both companies are making is that a corpus of case law and citations becomes more valuable when a machine reads it, and that the customer will pay the difference. Two renewal seasons' worth of invoices now say they will. The third is being signed.