

Uranium Royalty Emptied Its Uranium Stockpile to Part-Fund a Soda Ash Royalty Book
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A company named for uranium royalties now owns no uranium and collects almost none of its revenue from uranium royalties. Uranium Royalty Corp held more than 2.3m pounds of uranium oxide in January, ran the stockpile to zero by selling the remainder at $85.91 a pound, and put the proceeds toward a $1.14bn purchase of trona (soda ash) royalties in Wyoming.
Royalty revenue for the year to April was $0.15m, and four of its 24 uranium properties are production-stage. The company is nonetheless the one uranium-linked share rising while Cameco falls, because its cash arrived inside the quarter, from pounds already sold. The single analyst covering it models revenue down 39% this fiscal year.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
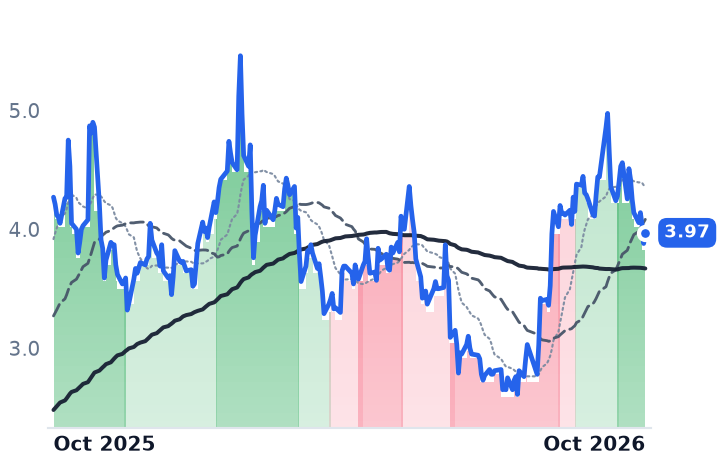
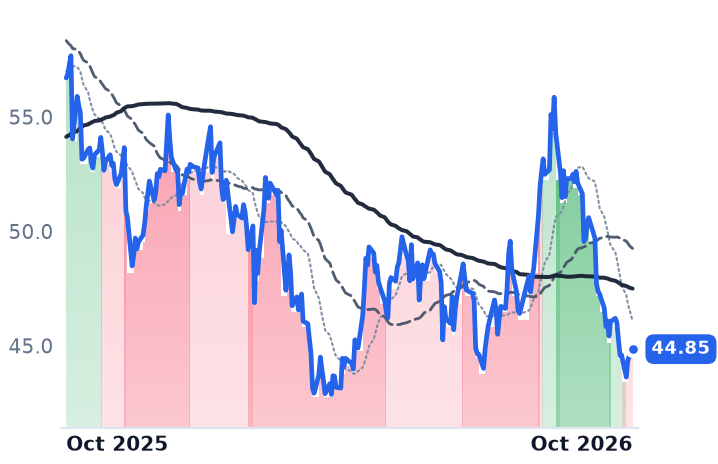
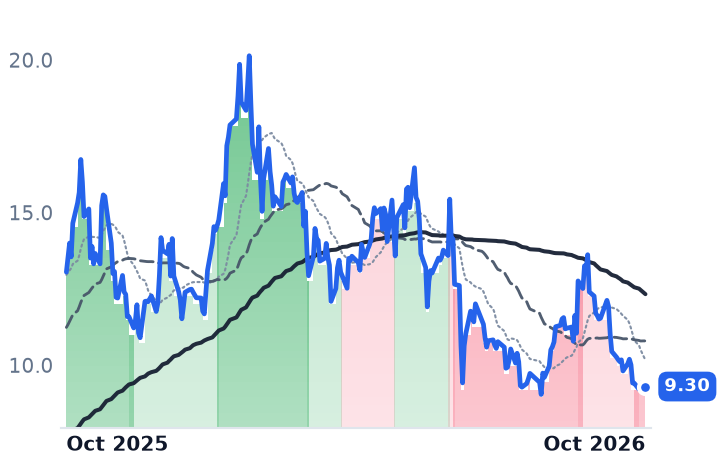
UROY | Uranium Royalty | Uranium | 🟢 Cont. Bull | −18.2% | −7.0% |
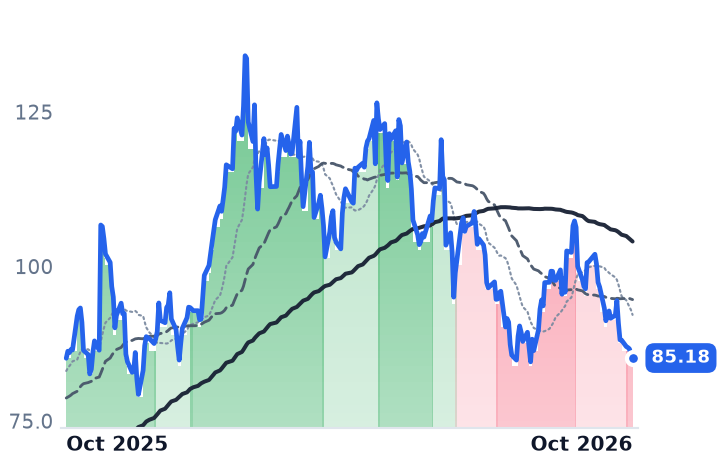
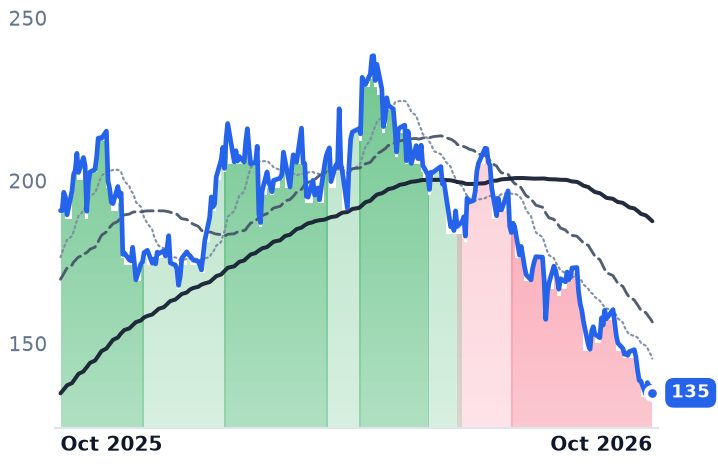
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −16.5% | +0.0% |
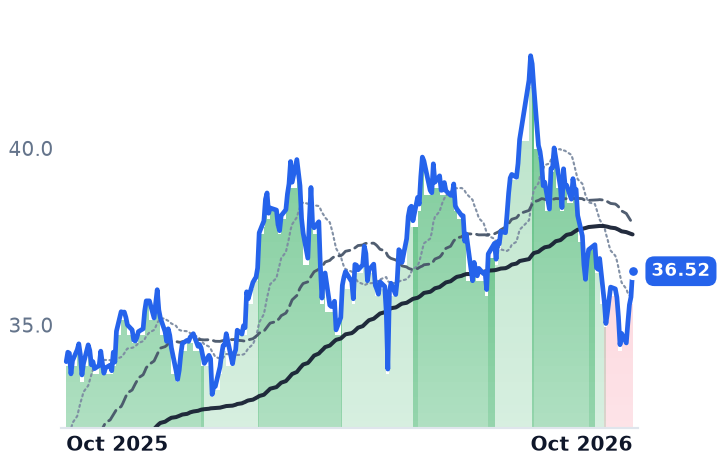
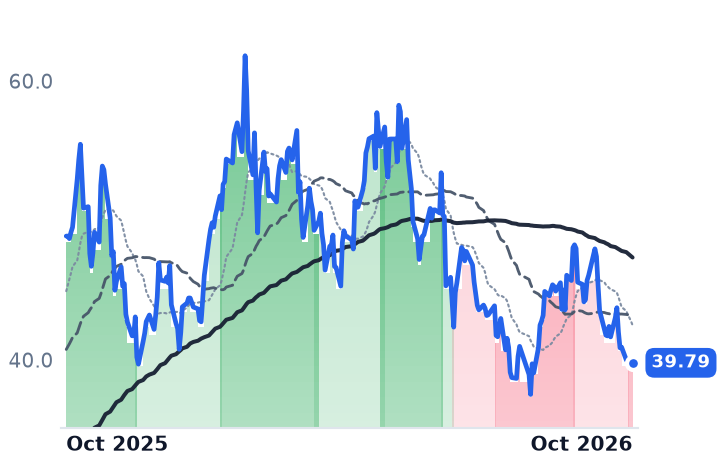
BIP | Brookfield Infrastructure Partners | Infrastructure & Transport Conglomerates | 🟢 Cont. Bull | −2.0% | +7.5% |
| Compared against · context, not the story | |||||
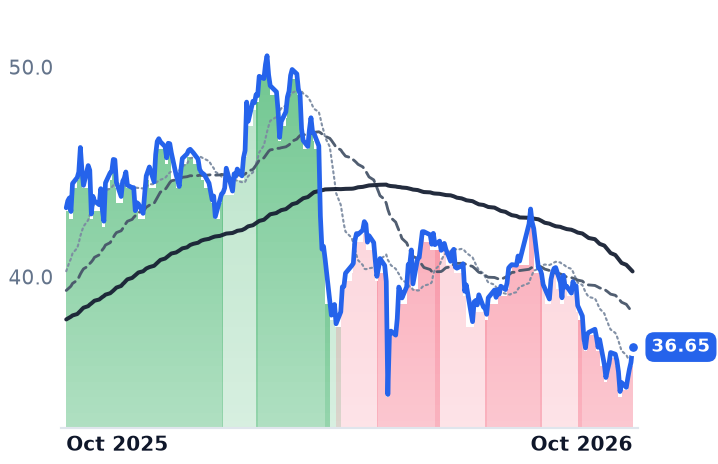
BIPC | Brookfield Infrastructure | International Gas Infrastructure | 🔴 Cont. Bear | −2.3% | −15.3% |
BAM | Brookfield Asset Management | Real Estate & Infrastructure | 🌱 Emerging Bull | −9.8% | −20.9% |
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −17.0% | −18.6% |
BWXT | BWX Technologies | Naval & Shipbuilding | 🔴 Cont. Bear | −15.9% | −29.3% |
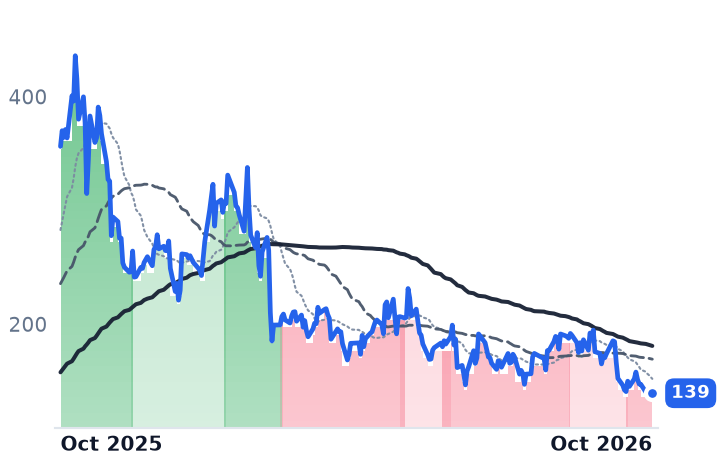
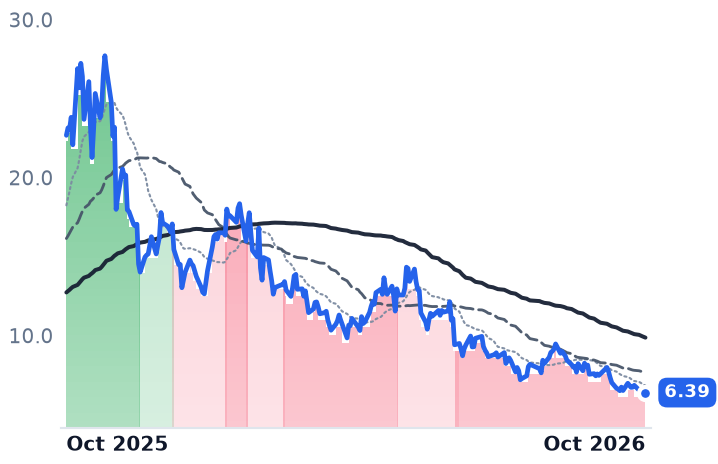
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −24.9% | −60.9% |
UEC | Uranium Energy | Uranium | 🔴 Cont. Bear | −23.3% | −28.7% |
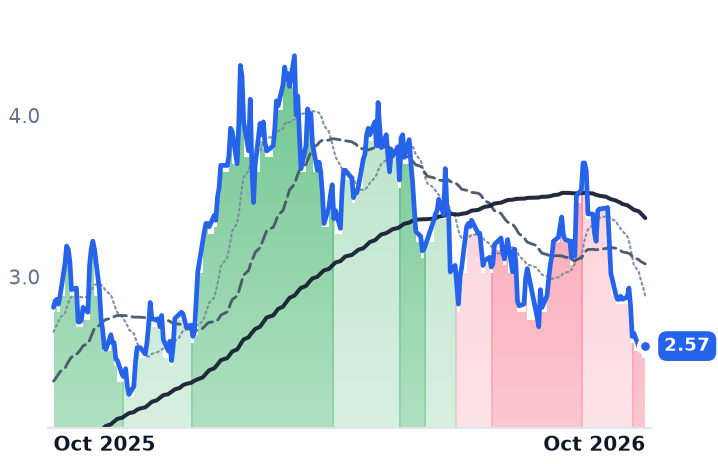
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −19.9% | −71.8% |
DNN | Denison Mines | Uranium | 🔴 Cont. Bear | −25.0% | −8.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UROY | $582.0M | 10.0x | 451.6x | 2.4x | 8.4x | 7.9x | 27.5x | 3.8x | 39.5% |
CCJ | $37.1B | 148.5x | 57.8x | 15.2x | 10.7x | 55.2x | 38.7x | 61.2x | 1.0% |
BIP | $16.8B | 50.9x | 64.3x | 0.7x | 1.0x | 2.5x | 3.7x | 7.0x | -3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BIPC | $4.5B | n/m | — | 1.2x | 1.2x | 1.9x | 1.9x | 4.3x | -4.7% |
BAM | $75.5B | 27.2x | 25.3x | 14.0x | 12.2x | 17.4x | 15.2x | 87.0x | 2.9% |
URA | $3.9B | — | — | — | — | — | — | — | — |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $12.4B | 34.8x | 28.4x | 3.5x | 3.2x | 15.9x | 14.7x | 24.9x | 2.6% |
LEU | $2.6B | 55.1x | 54.3x | 5.5x | 5.6x | 23.7x | 23.9x | 26.5x | -8.5% |
UEC | $4.6B | n/m | — | 225.6x | 44.5x | 533.1x | 105.1x | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LTBR | $258.0M | n/m | — | n/m | — | — | — | n/m | -6.6% |
DNN | $2.9B | n/m | — | 988.4x | 120.1x | — | — | n/m | -4.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
UROY | Revenue | +718.5% | −38.8% | −35.5% |
| EPS | −174.5% | −58.8% | −90.6% | |
CCJ | Revenue | +1.4% | +12.3% | +8.3% |
| EPS | +2.6% | +71.9% | +24.2% | |
BIP | Revenue | +112.0% | −44.9% | +8.3% |
| EPS | −46.5% | +88.2% | −29.9% | |
BIPC | Revenue | +3.7% | +6.4% | +6.3% |
| EPS | −120.4% | −553.3% | +14.2% | |
BAM | Revenue | +14.2% | +17.1% | +11.7% |
| EPS | +14.6% | +18.2% | +16.8% | |
BWXT | Revenue | +20.7% | +9.1% | +8.7% |
| EPS | +24.1% | +10.6% | +13.3% | |
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +53.3% | −65.1% | −345.7% | |
DNN | Revenue | +394.2% | −27.3% | +1699.7% |
| EPS | −30.5% | −73.1% | −363.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Uranium Royalty Corp closed its fiscal year holding no uranium. The Vancouver company, with 14 employees and run by chief executive Scott Melbye, owns royalty and streaming interests on deposits from McArthur River in Saskatchewan to Langer Heinrich in Namibia, and it carried 2,329,637 pounds of uranium oxide at the end of January. By 30 April the stockpile was down to 593,255 pounds, held in its account at Cameco's Port Hope and Blind River plants, and those last pounds were sold after year-end at a weighted average of $85.91 a pound.
The equity is read as a pure claim on reactor demand, and over the three months to 2 October it was the only uranium-linked share going up: 41.3% higher, while Cameco, the largest listed producer, lost 11.8%. The accounts say that gap is not about reactors at all. It separates a company whose uranium money has already been banked from companies waiting on utilities to sign.
The pounds paid; the royalties barely exist
In the quarter to 31 July, the sale of those 593,255 pounds produced $51.0m of revenue at about $86 a pound against $34.1m of cost of sales: roughly $57 a pound, because the inventory was accumulated years earlier. Net income was $16.25m, up 1,530%, on diluted earnings of $0.10 a share.
The royalty book contributed almost nothing. Uranium royalty revenue for the year to 30 April was $0.15m, against $0.06m the year before, and only four of 24 uranium properties are production-stage; the other 20 are exploration-stage. When a royalty does pay, it may not pay in money. On 14 March, Orano Canada settled the calendar-2025 McArthur River royalty by delivering 13,618 pounds of uranium oxide into storage. The Cigar Lake interest is a sliding-scale 10% to 20% net profits interest on a 3.75% share of production derived from Orano's 40.453% stake in the project, a fraction of a fraction of one mine.
What $1.14bn bought in the Green River Basin
What the pounds funded is not uranium. In July the company acquired about 92% of the Sweetwater entities from funds managed by Orion Resource Partners and from HRG Metals, a subsidiary of the Ontario Teachers' Pension Plan, for roughly $1.14bn: about $330m in cash plus 223,252,749 new shares at a deemed $3.64. Existing shareholders were left with about 41% of the combined company.
Sweetwater is trona (soda ash) royalties and land in Wyoming's Green River Basin, Utah and Colorado, typically an 8% production royalty on net sales from leases over 108,934 acres worked by WE Soda, American Soda, Sisecam and Tata Chemicals. Expansions are expected to lift attributable production capacity by more than 60% with no further capital from the company. On completion, Melbye said the land ownership "encompasses one of the world's largest known trona (soda ash) resources with five currently operating mines", which is "expected to provide steady cash flows to advance the company's uranium aspirations".
The producers are paid in volume, and volume fell
Uranium itself has not weakened. Spot reached $89.54 a pound at the end of August, about 20% higher year on year, and the long-term contract price set a record near $96, above the $95 of 2007. The record formed on thin business: term contracting fell about 15% year on year to just over 38m pounds by 31 August, with utilities balking at the price. Producers are paid in signed volumes, which is why Cameco sits 37% below its $135.24 high and still carries 148x trailing and 57.8x forward earnings.
A cheap multiple on a share count that no longer exists
The trailing figures circulating on Uranium Royalty, just under 10x earnings and 1.3x book, rest on a $582m market value that predates July's issuance. At about 381m shares the company is worth roughly $1.51bn, per third-party counts, which against $55.5m of net income for the year to April works out near 27x. The one analyst publishing estimates models revenue falling 38.8% to $69.2m this fiscal year and 35.5% again next, with earnings per share of less than a cent. The implied forward multiple runs into the hundreds. The shares, at $3.97 on 2 October, are 12.4% below their 17 September peak.
So the strongest share in the fuel chain belongs to the member that stopped holding fuel. The sorting principle is the timing of cash rather than nuclear construction: inventory sold at $86 pays this year, a contract signed for the 2030s does not, and the de-rating that hit Cameco, Centrus and Lightbridge together ranked the complex by how far away the money is.
The uranium left inside Uranium Royalty is mostly exploration ground, one metal-settled royalty and the aspiration in Melbye's sentence. The bills, for now, are paid by soda ash.