

StandardAero Stopped Rebilling No-Margin Parts, and Its Revenue Growth Fell to 4.6%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Decelerating revenue across jet-engine suppliers has been read as the aftermarket cycle rolling over. At StandardAero the deceleration was self-inflicted: restructured contracts eliminated material that the company buys for customers and rebills at little or no markup, so June-quarter revenue grew 4.6% against 20.4% a year earlier while adjusted margin set a company record at 14.4%.
Howmet, which casts and forges the airfoils inside those engines, shows the same accounting from the other side. Metal pass-through did dilute margin — in heavy-truck wheels, by 360 basis points, while Engine Products margin rose to 37.7% from 33.0% and spares revenue grew 37%.
Both businesses improved and both stocks fell with the complex. The difference is the starting price: Howmet still trades at 43.3x forward earnings, StandardAero at 13.6x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
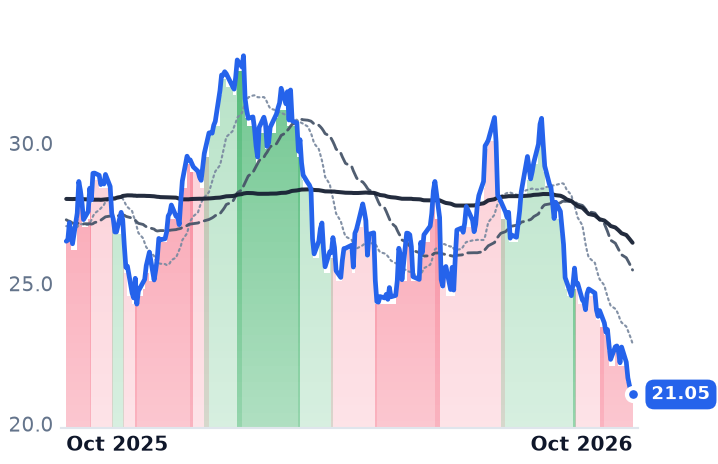
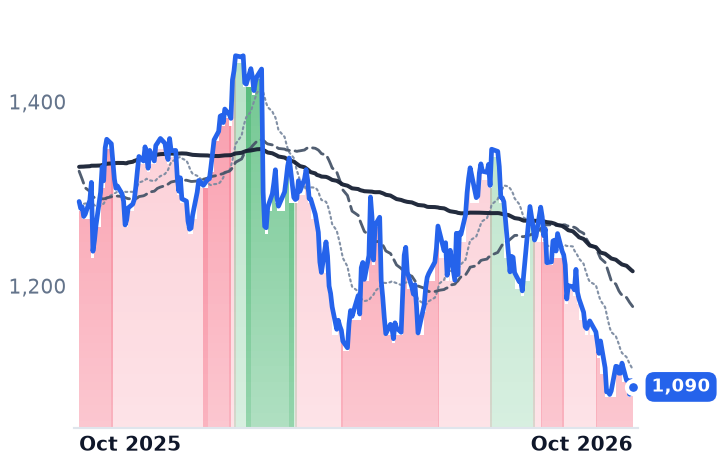
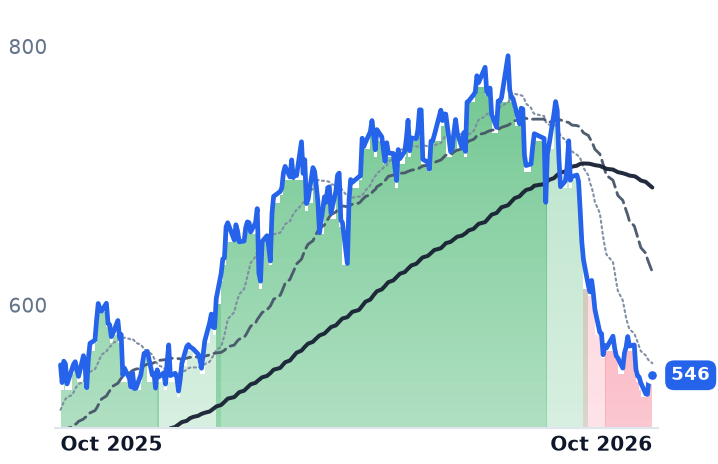
SARO | StandardAero | Engines & Propulsion | 🔴 Cont. Bear | −14.7% | −20.6% |
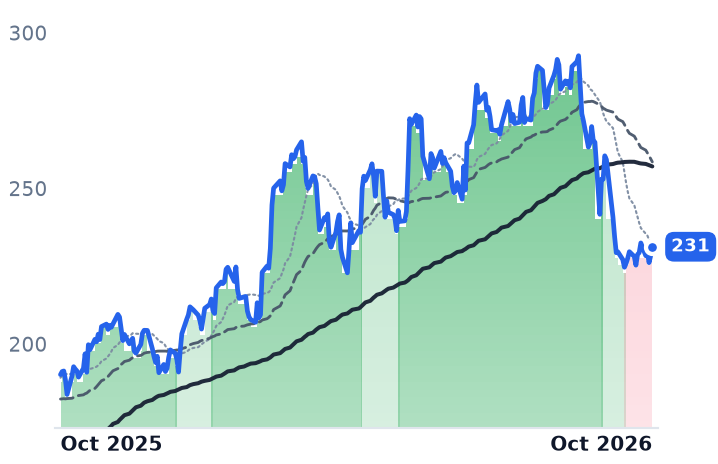
HWM | Howmet Aerospace | Engines & Propulsion | 🟢 Cont. Bull | −4.0% | +21.6% |
| Compared against · context, not the story | |||||
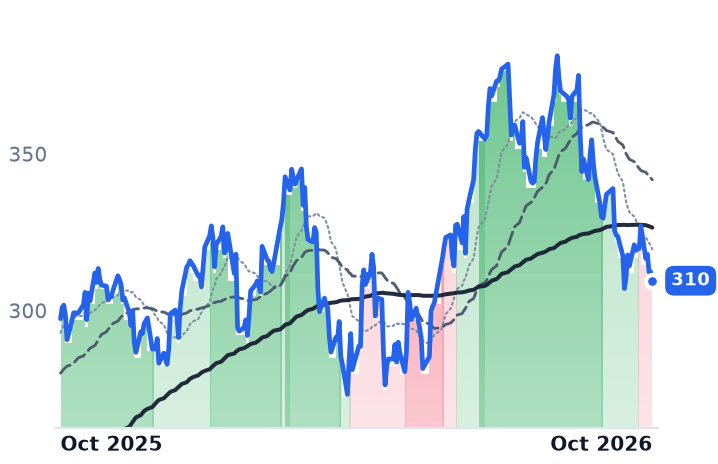
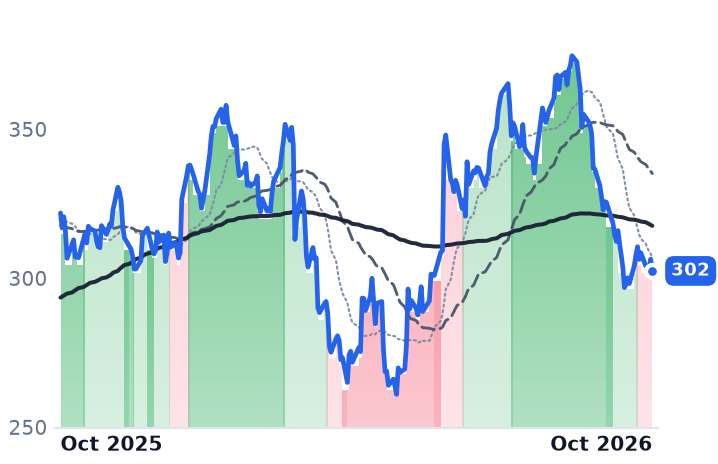
GE | GE Aerospace | Large Diversified Primes | 🟢 Cont. Bull | −8.7% | +4.1% |
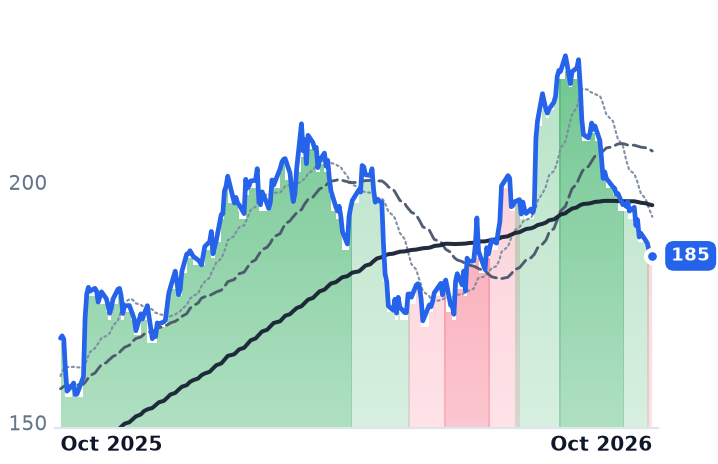
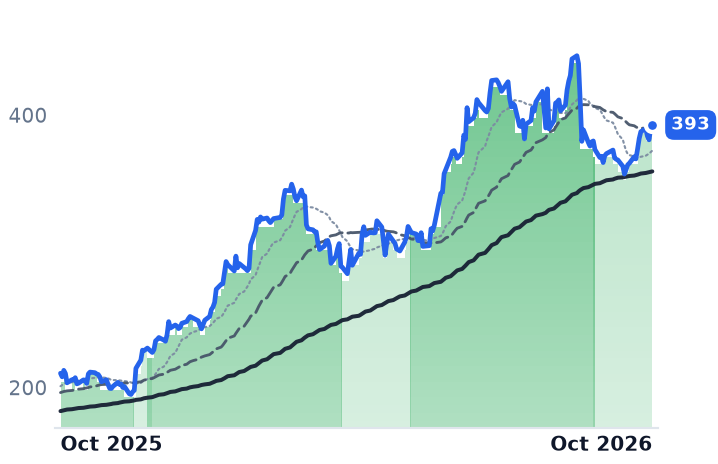
RTX | RTX | Large Diversified Primes | 🟢 Cont. Bull | −7.2% | +10.2% |
TDG | TransDigm Group Incorporated | Advanced Materials & Components | 🔴 Cont. Bear | −5.2% | −15.6% |
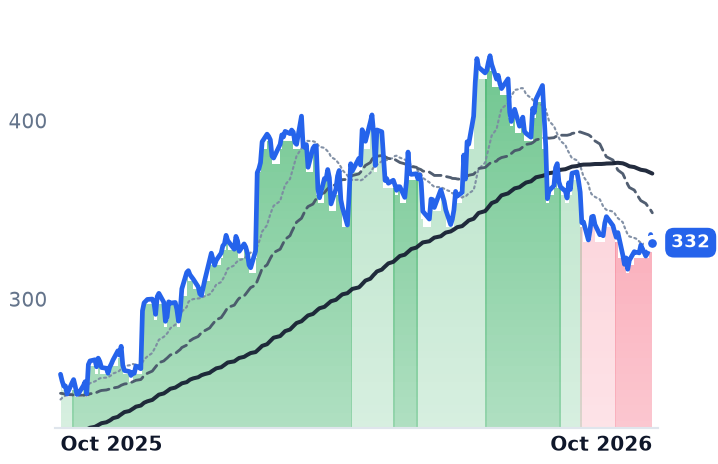
HEI | HEICO | Avionics & Electronic Systems | 🟢 Cont. Bull | −5.0% | −6.0% |
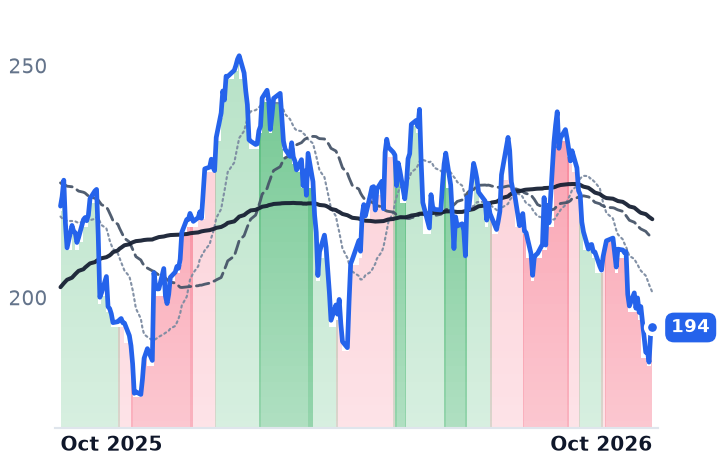
BA | The Boeing | Large Diversified Primes | 🔴 Cont. Bear | −9.1% | −11.9% |
WWD | Woodward | Flight Controls & Actuation | ⚠️ Emerging Bear | −2.8% | +28.6% |
CW | Curtiss-Wright | Flight Controls & Actuation | ⚠️ Emerging Bear | −5.3% | −1.4% |
MOG-A | Moog | Flight Controls & Actuation | 🟢 Cont. Bull | +4.9% | +86.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SARO | $7.0B | 21.3x | 13.6x | 1.1x | 1.1x | 7.5x | 7.4x | 11.2x | 3.1% |
HWM | $92.5B | 49.5x | 43.3x | 10.1x | 9.2x | 29.5x | 26.6x | 35.0x | 1.7% |
GE | $321.2B | 36.3x | 39.1x | 6.3x | 6.4x | 17.9x | 18.0x | 27.1x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RTX | $248.9B | 32.1x | 25.5x | 2.7x | 2.6x | 13.1x | 12.7x | 17.4x | 4.8% |
TDG | $64.1B | 34.7x | 27.9x | 6.4x | 6.1x | 10.7x | 10.2x | 19.0x | 3.0% |
HEI | $44.0B | 52.0x | 50.3x | 8.5x | 8.2x | 21.1x | 20.2x | 31.6x | 2.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BA | $173.8B | 79.6x | — | 1.9x | 1.8x | 39.2x | 37.0x | 29.7x | -0.6% |
WWD | $20.8B | 40.6x | 37.5x | 5.2x | 4.8x | 18.3x | 17.1x | 28.5x | 1.9% |
CW | $26.3B | 51.5x | 46.9x | 7.3x | 7.0x | 19.6x | 18.8x | 36.4x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOG-A | $9.6B | 33.8x | 29.1x | 2.3x | 2.2x | 8.6x | 8.3x | 18.6x | 2.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SARO | Revenue | +7.0% | +9.9% | +9.4% |
| EPS | +84.6% | +15.3% | +17.4% | |
HWM | Revenue | +23.2% | +13.8% | +11.7% |
| EPS | +44.1% | +22.1% | +18.6% | |
GE | Revenue | +20.6% | +10.9% | +9.0% |
| EPS | +26.6% | +14.8% | +13.8% | |
RTX | Revenue | +10.6% | +7.6% | +7.3% |
| EPS | +16.8% | +9.2% | +10.5% | |
TDG | Revenue | +19.4% | +10.1% | +7.6% |
| EPS | +12.2% | +17.7% | +15.2% | |
HEI | Revenue | +21.1% | +11.1% | +8.7% |
| EPS | +31.4% | +13.5% | +13.1% | |
BA | Revenue | +10.8% | +14.6% | +9.6% |
| EPS | −98.6% | −3232.7% | +86.2% | |
WWD | Revenue | +22.4% | +8.6% | +10.0% |
| EPS | +39.2% | +14.6% | +17.6% | |
CW | Revenue | +9.6% | +8.0% | +8.1% |
| EPS | +15.6% | +12.0% | +12.1% | |
MOG-A | Revenue | +13.9% | +6.5% | +6.0% |
| EPS | +26.1% | +10.1% | +7.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
StandardAero, which overhauls jet engines under licence from the engine makers for airline, military and business-jet operators, spent this year taking revenue out of its own contracts. Restructured agreements eliminated material pass-through: parts the company buys for a customer's engine and rebills at little or no markup. June-quarter revenue rose 4.6%, against 20.4% a year earlier. Profitability moved the other way, to a record adjusted margin before interest, taxes, depreciation and amortization of 14.4%, up a point.
The reason that decomposition matters is that the market has spent five weeks treating slowing top lines across engines and propulsion as proof the aftermarket cycle is peaking. In early September, Melius Research downgraded GE Aerospace, HEICO, Honeywell Aerospace Technologies, TransDigm and Woodward to Hold, warning that several years of robust aftermarket growth may be ending. In a trade where a large slab of a reported dollar is metal and parts bought on the customer's behalf, revenue growth is a poor instrument for measuring demand.
What is actually inside a shop-visit dollar
StandardAero's full-year 2025 gross margin was 14.8% against Howmet's 30.7% — roughly a fifth, because so much of an overhaul invoice is components rather than value added. Strip the worst of that out and the line shrinks. Engine Services revenue rose 4.0% to $1.41bn as growth in all three end markets was offset by the pass-through elimination, the company's quarterly filing says, while segment adjusted EBITDA margin rose to 14.5% from 13.2%.
The rest of the quarter reads like a company with more work than throughput. "We achieved profitability in the second quarter while continuing to ramp the program and win new awards. This is an important milestone," chief executive Russell Ford said of the LEAP overhaul programme on the 6 August call. Capacity, not orders, is the limit: a second LEAP test cell in San Antonio needs 12 to 18 months of correlation before it can take engines. Leverage fell to 2.6x adjusted EBITDA from 3.0x, and $100m of stock was repurchased in the first half. The genuine soft spot is military: Component Repair Services grew 9.2% but lost 270 basis points of margin, to 26.3%, on input delays.
Howmet's metal drag sits in truck wheels
Howmet casts and forges turbine airfoils and structural parts for engines, and also makes fasteners, titanium structures and forged aluminium wheels for heavy trucks. Its June quarter put revenue at $2.55bn, up 24% with 21% organic, and Engine Products margin at 37.7% against 33.0%. Spares — the high-value parts sold straight into overhaul shops — rose 37% to about $560m, around 22% of first-half revenue, a greater share than historically.
Aluminium pass-through did dilute a margin, in heavy trucks rather than engines: 360 basis points off Forged Wheels. Engineered Structures, the one segment going backwards, fell 13% to $269m. "More robust build rates for commercial aircraft are supported by record backlogs, while engine spares needs continue to increase," executive chairman and chief executive John Plant said on 6 August. The build rates behind that are rising — Boeing's 737 line moved from 42 to 47 a month with regulatory concurrence in the first half.
The long bond did the work
Over the three months to 2 October the complex fell together: TransDigm down 19.1%, GE Aerospace 18.0%, HEICO 16.5%, Boeing and Howmet 14.5% each, RTX 7.3%, StandardAero worst at 30.1%. Over that span the 10-year Treasury yield reached its highest since 2002 and sat at 5.26% on 5 October after the Federal Reserve's first rate rise in more than three years. On 30 September Wells Fargo's David Strauss cut Howmet to Equal Weight, target $255 from $315, saying further earnings beats "may be more difficult to achieve in a slowing economic growth environment" — an elasticity argument about a slowdown that has not yet appeared in either order book.
The installed base says otherwise so far. GE Aerospace now expects 2,300 to 2,400 CFM56 shop visits a year in both 2026 and 2027, with retirements running at 1.5% to 2% against the 3% to 4% it originally anticipated.
So the results explain almost none of the decline and the starting price explains most of it, unevenly. Howmet's operating record accelerated into the fall and its shares still carry 43.3x forward earnings, dearer than GE Aerospace at 39.1x despite being a component supplier to it; a fifth off that price is arithmetic on the rate, not a verdict on the forge. StandardAero's margin, leverage and cash all improved while its shares reached their low for the year, leaving 13.6x forward against 21.3x trailing — the gap is the 85% earnings increase analysts have pencilled in, and it is the one of the two where the business and the quotation have genuinely parted company.
The question the next print settles is whether removing no-margin parts billing was a one-off reset or the start of a company that reports smaller revenue every year it gets better. Investors have no practice valuing the second kind.