

M/I Homes' Mortgage Arm Wrote 96% of Its Buyers' Loans and Covered 2% of Its Lost Profit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The in-house lender was supposed to be what paid for the discount. At M/I Homes it does not come close. The builder's captive mortgage and title business financed a record share of its own buyers in the June quarter, and its first-half pre-tax income still fell, to $28.5m from $30.6m, against a $107m drop in the parent's operating income.
What did stabilize is the thing that matters: homebuilding gross margin has been flat two quarters running at about 22% after bottoming at 18.1% in late 2025, on record second-quarter orders and cancellations down to 8% from 13%. Dream Finders is the other side — homebuilding margin at 14.2%, option deposits being written off, and a $2.2bn cash purchase of Beazer closing into the weakest margins of the cycle.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
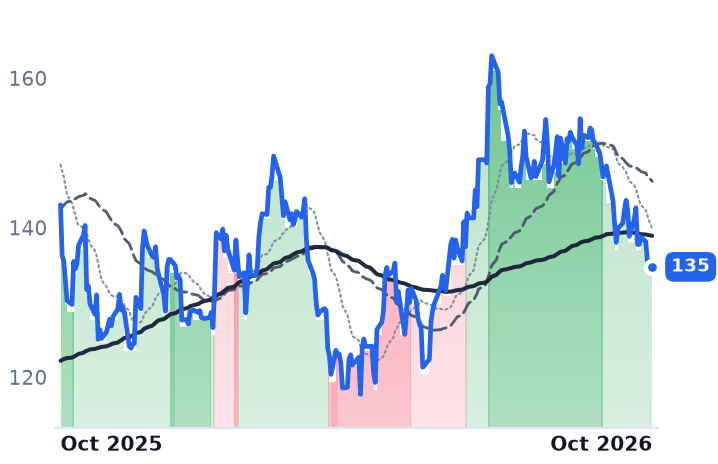
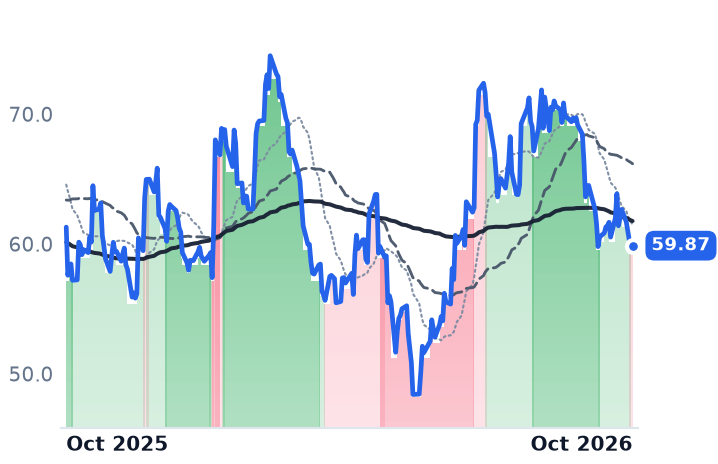
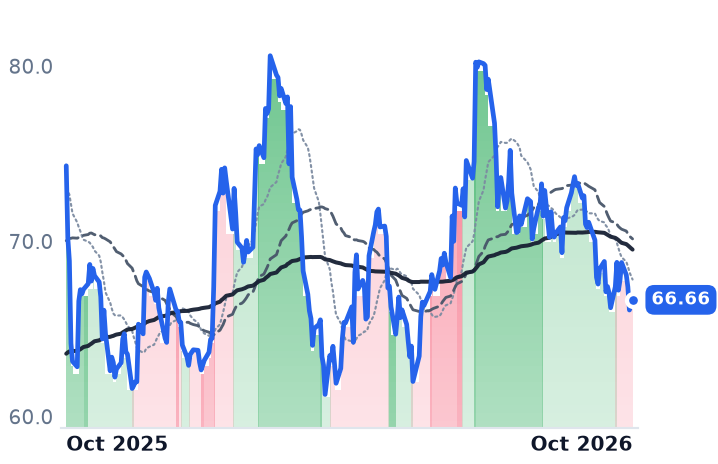
MHO | M/I Homes | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −9.1% | −5.8% |
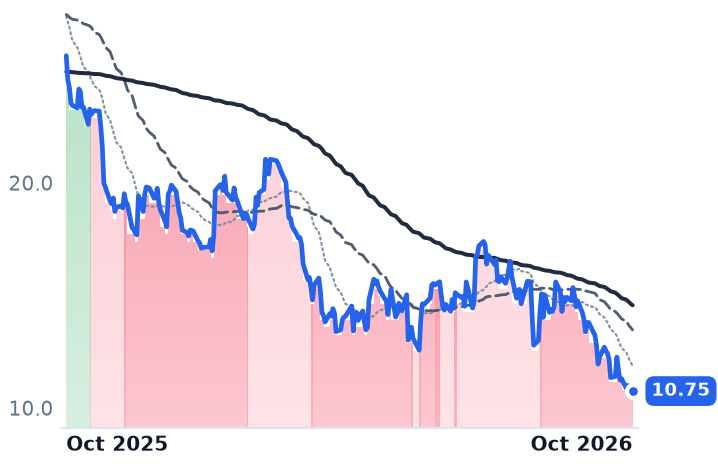
DFH | Dream Finders Homes | Regional & Mid-Size Homebuilders | 🔴 Cont. Bear | −22.1% | −58.1% |
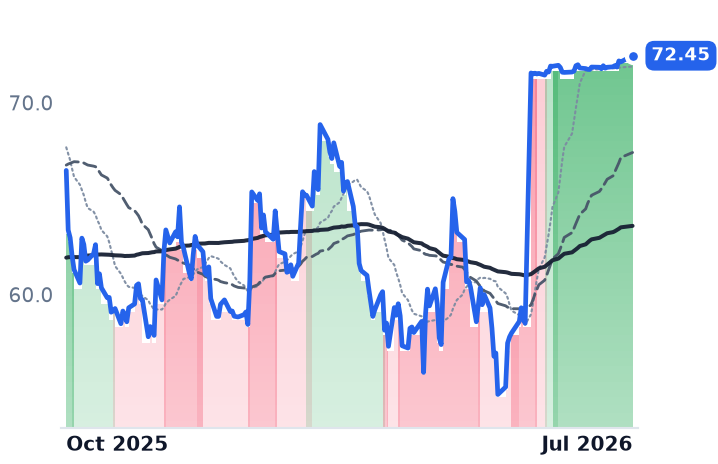
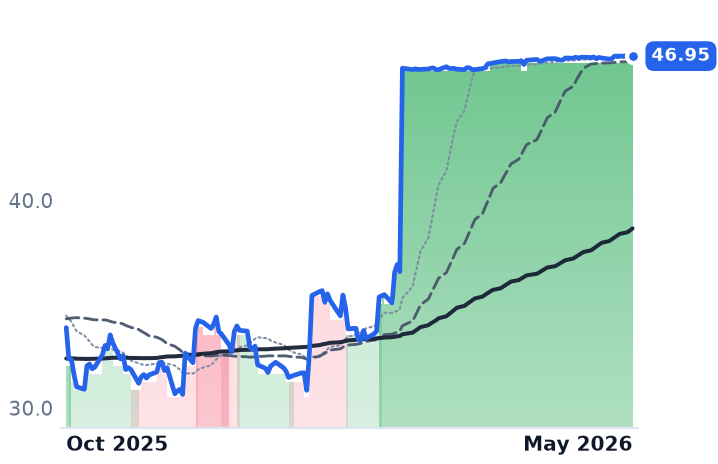
TMHC | Taylor Morrison Home | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | — | +9.0% |
| Compared against · context, not the story | |||||
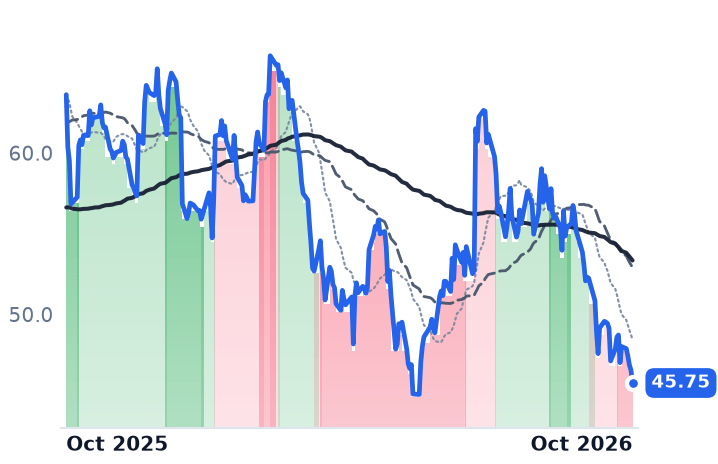
KBH | KB Home | Regional & Mid-Size Homebuilders | 🔴 Cont. Bear | −12.4% | −28.1% |
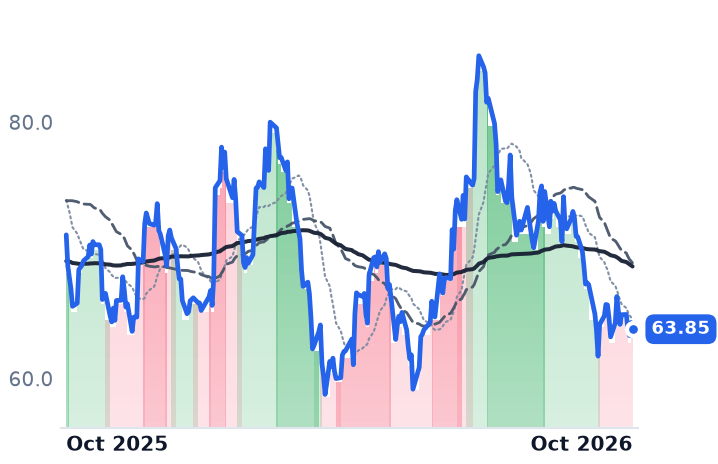
MTH | Meritage Homes | Regional & Mid-Size Homebuilders | 🌱 Emerging Bull | −5.2% | −10.3% |
CCS | Century Communities | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −7.2% | −2.3% |
GRBK | Green Brick Partners | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | −6.2% | −10.3% |
TPH | Tri Pointe Homes | Regional & Mid-Size Homebuilders | 🟢 Cont. Bull | — | +38.6% |
BZH | Beazer Homes USA | Entry-Level & Value Homebuilders | 🟢 Cont. Bull | +0.4% | +37.4% |
DHI | D.R. Horton | Large National Homebuilders | ⚠️ Emerging Bear | −5.4% | −20.6% |
LEN | Lennar | Large National Homebuilders | 🔴 Cont. Bear | −4.5% | −36.0% |
PHM | PulteGroup | Large National Homebuilders | 🟢 Cont. Bull | −7.0% | −14.2% |
NVR | NVR | Large National Homebuilders | 🔴 Cont. Bear | −4.8% | −25.7% |
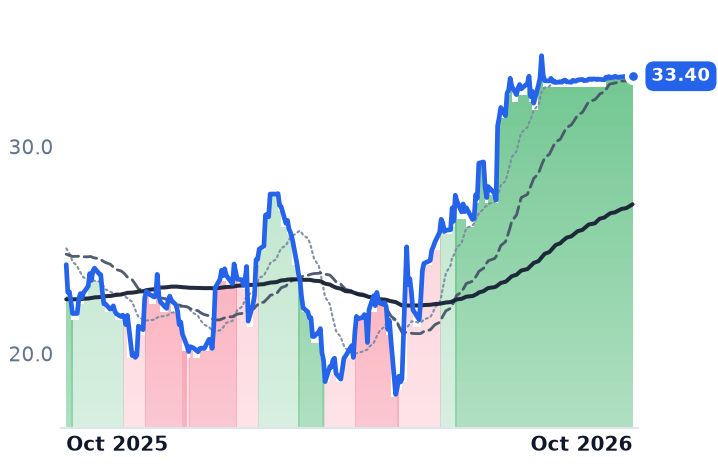
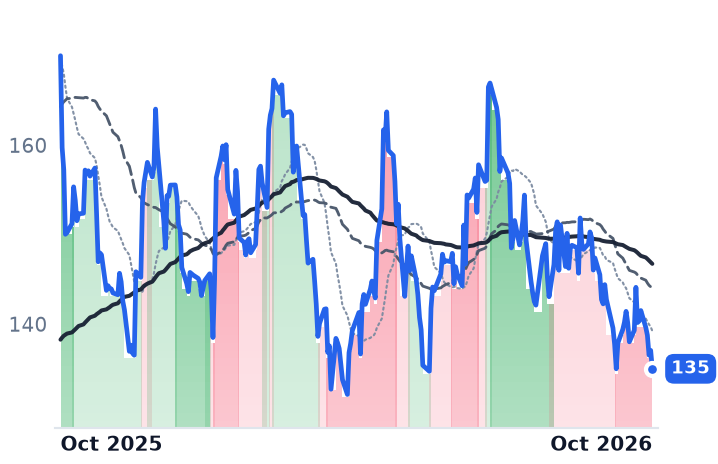
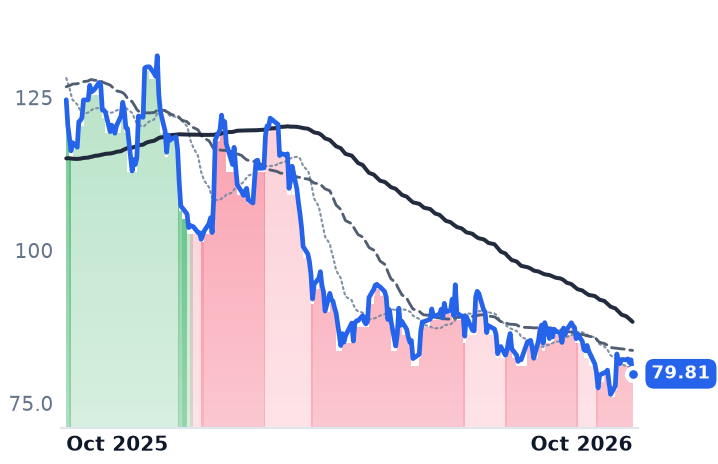
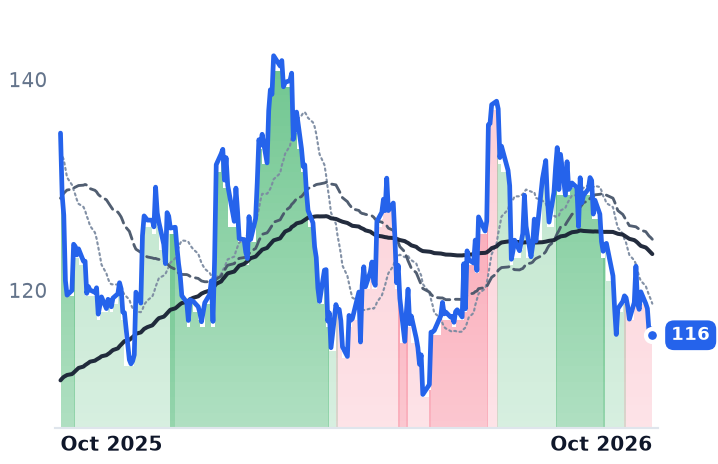
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MHO | $3.4B | 11.1x | 11.2x | 0.8x | 0.8x | 3.7x | 3.8x | 7.2x | 5.9% |
DFH | $991.0M | 6.8x | 10.1x | 0.2x | 0.2x | 1.7x | 1.7x | 11.1x | -16.3% |
KBH | $2.9B | 11.4x | 14.5x | 0.5x | 0.6x | 3.1x | 3.4x | 12.3x | 12.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MTH | $4.3B | 13.4x | 13.0x | 0.8x | 0.8x | 4.2x | 4.2x | 10.6x | 9.7% |
CCS | $1.4B | 10.7x | 12.9x | 0.3x | 0.4x | 2.0x | 2.2x | 14.2x | 6.8% |
GRBK | $2.7B | 9.0x | 10.5x | 1.3x | 1.4x | 4.3x | 4.4x | 7.0x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TMHC | $6.7B | 10.6x | 13.7x | 0.9x | 1.0x | 3.9x | 4.5x | 8.7x | 10.6% |
TPH | $4.0B | 21.7x | 24.5x | 1.2x | 1.3x | 6.0x | 6.5x | 16.0x | 2.8% |
BZH | $604.6M | n/m | — | 0.3x | 0.3x | 2.2x | 2.2x | — | -11.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DHI | $38.4B | 12.3x | 12.8x | 1.2x | 1.1x | 5.0x | 5.0x | 10.4x | 9.1% |
LEN | $20.8B | 11.3x | 13.4x | 0.6x | 0.6x | 3.7x | 3.8x | 9.4x | 0.1% |
PHM | $21.0B | 10.3x | 11.0x | 1.2x | 1.3x | 4.8x | 4.9x | 7.8x | 7.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVR | $15.0B | 12.5x | 15.4x | 1.5x | 1.6x | 6.8x | 6.9x | 8.9x | 8.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MHO | Revenue | −4.5% | +4.1% | −2.1% |
| EPS | −25.7% | +15.4% | +9.6% | |
DFH | Revenue | +0.9% | +3.0% | +3.7% |
| EPS | −50.6% | −26.3% | +21.0% | |
KBH | Revenue | −17.6% | +7.5% | +7.3% |
| EPS | −48.3% | +33.4% | +28.4% | |
MTH | Revenue | −8.9% | +7.3% | +7.2% |
| EPS | −26.3% | +20.1% | +30.2% | |
CCS | Revenue | −6.2% | +8.3% | — |
| EPS | −30.8% | +30.8% | — | |
GRBK | Revenue | −3.0% | +9.3% | — |
| EPS | −15.0% | +12.4% | — | |
TMHC | Revenue | −16.2% | +7.7% | — |
| EPS | −32.1% | +23.5% | — | |
TPH | Revenue | −11.9% | +7.7% | +96.9% |
| EPS | −31.5% | +21.3% | +249.2% | |
BZH | Revenue | −6.8% | +14.8% | — |
| EPS | −151.2% | −296.5% | — | |
DHI | Revenue | −1.8% | +5.8% | +6.1% |
| EPS | −10.5% | +12.3% | +16.8% | |
LEN | Revenue | −2.9% | +3.4% | +8.6% |
| EPS | −25.8% | +21.8% | +22.3% | |
PHM | Revenue | −3.9% | +4.9% | +7.6% |
| EPS | −12.0% | +11.5% | +17.9% | |
NVR | Revenue | −5.5% | +6.3% | +2.7% |
| EPS | −14.5% | +16.3% | +22.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
M/I Homes builds single-family houses and townhomes across nine states from Ohio to Texas, and it owns the lender that finances them. In the June quarter that lender wrote the loan for 96% of the company's buyers, a record. It also earned less money than it did a year earlier.
That is the finding, and it kills a convenient story about how production builders are surviving 7% mortgages. The discount a buyer needs today is not taken off the sticker; it is spent on forward-commitment points that buy the mortgage rate down, and that cost is booked in cost of sales. The captive lender is supposed to recapture some of it. At M/I Homes, financial services pre-tax income fell to $28.5m in the first half from $30.6m, with segment revenue up 1% to $63.6m as the higher capture rate and extra originations were offset by smaller average loans. Consolidated operating income over the same half fell $106.6m, to $187.3m. The subsidy covered about 2% of the damage.
The margin stopped falling anyway
Strip the lender out and M/I Homes' homebuilding line is the most encouraging in the group. Gross margin was 22.0% in the first quarter and 22.1% in the second, after a trough of 18.1% in the fourth quarter of 2025 and a reading above 25% in early 2025. Second-quarter revenue fell 8.5% to $1.06bn while gross profit fell 17.8% — the squeeze is in price realization, not units. Orders were a second-quarter record, up 15% to 2,387 homes on a flat 234 communities, with monthly pace at 3.4 homes per community from 3.0 and cancellations at 8% against 13%. Backlog carried an average sales price of $538,000. The list price is holding; the concession is hidden in the financing.
"We continue to use mortgage rate buydowns as our primary incentive, and given the current rate environment, will continue to promote with such buydowns for the foreseeable future," chairman and chief executive Robert Schottenstein said on the July 29 call. About 78% of second-quarter orders were specs — finished or in-progress houses sold off the shelf — a bet the rest of the industry is backing away from. Schottenstein put a price on it: in nearly every one of the company's 17 markets a to-be-built home carries a better margin than a spec, "in some, just slightly; in others, it could be 100 or 200 basis points." The buydowns are priced to a payment, advertised slightly below 5% on government programs, against a 30-year survey rate Freddie Mac put at 7.28% on October 1.
The stress case, and the control
Dream Finders Homes, a Jacksonville builder of starter and move-up houses that brokers its mortgages to PrimeLending rather than consolidating a lender, shows what the same bill does to a thinner balance sheet: homebuilding gross margin of 14.2% against 16.5%, lots controlled down to 54,091 from 63,121 at year-end, and $3.0m of lot-deposit and abandonment charges — options walked away from rather than exercised. It trades at 6.8x trailing earnings and 10.1x forward, because consensus for 2026 has halved to $1.07 a share and 2027 has been cut to $0.79; free cash flow is negative. Into that it is closing a $2.2bn all-cash purchase of Beazer Homes, with Beazer holders voting October 15 and $350m of notes being redeemed October 20.
KB Home, which builds to order rather than on spec, is the test of whether any of this is margin-specific. Its third quarter showed revenue down 20% to $1.30bn and housing gross margin of 16.5% against 18.2%, with backlog rising for the first time in four years — and full-year margin guidance still cut to 16.0-16.2%. Across the industry, 66% of builders reported using incentives in September, up from 63%. The bill is still growing.
What the shares are paying for
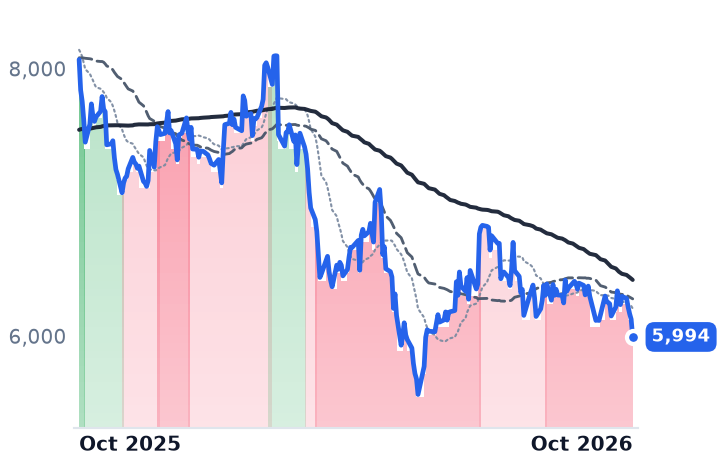
M/I Homes closed at $134.76 on October 2, down 8.2% over thirty days and 14.1% over three months, but up 10.8% over six — the best six-month return of the ten listed builders checked. Every builder fell over that month, from Dream Finders at -19.7% to Lennar at -4.5%, and no company announcement dated inside the window was discoverable for M/I Homes, so the likelier reading is rates and the September slide in builder confidence rather than anything at the company. It trades at 11.1x trailing earnings and 11.2x forward — the market paying for no growth at all — and at 1.07x book, dearer than Meritage at 0.85x, KB Home at 0.78x and Dream Finders at 0.62x.
So the trough is real and the subsidy is not. M/I Homes has earned two flat margin quarters with better orders and fewer cancellations, which is more than anyone else on this shelf can show; what it has not earned is the idea that owning the mortgage company pays for the buydown. That makes the next print a question about one number — incentive load — and not about demand, which is arriving. Dream Finders' de-rating, by contrast, is its own arithmetic, and it is about to add Beazer's leverage to it.
Two of this shelf's names stopped trading this year because strategic buyers wanted the cash flow at these margins: Berkshire Hathaway closed its $72.50-a-share purchase of Taylor Morrison on July 24, and Sumitomo Forestry took out Tri Pointe at $47 in May. The six still listed are being marked down for selling the same houses.