

Aon Grew Each of Its Four Lines 5% and Expanded Its Margin, Then Fell to a 52-Week Low
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
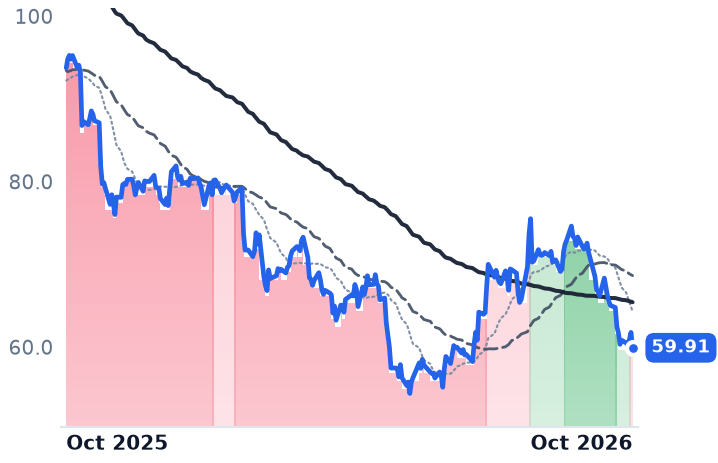
Two large insurance brokers have lost about a quarter of their value over twelve months, and only one of them has the operating numbers to justify it. Aon's adjusted operating margin widened to 28.9% in the June quarter, every one of its four business lines grew 5% organically, and the consensus earnings estimate for this year has been trimmed less than 1% since mid-September — yet the shares closed October 2 exactly at their 52-week low, at 14.5 times that estimate against the 19.4 times its price a year earlier implied.
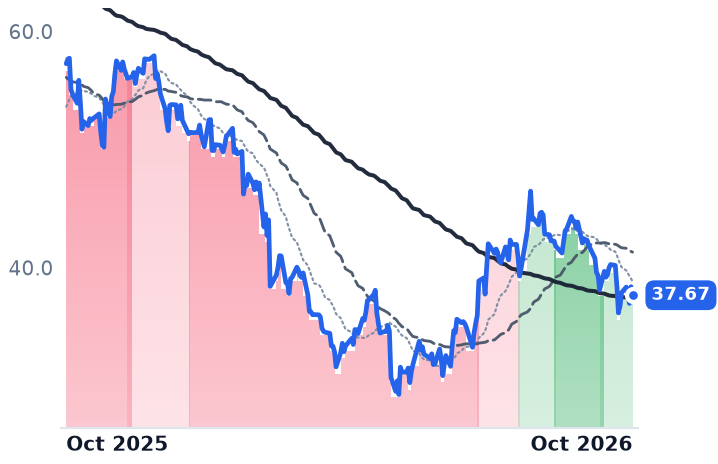
Gallagher's de-rating is the better-earned one: after a 27% fall it is still the most expensive of the four big brokers on forward earnings, on enterprise value against cash earnings, and on free-cash-flow yield at 3.94%. What Aon's price does not reflect is operating damage. What it may reflect is $17bn of borrowed money for USI Insurance Services that adds nothing to per-share earnings until 2028.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AON | Aon | Global Risk & Insurance Brokers | 🌱 Emerging Bull | −16.6% | −26.1% |
AJG | Arthur J. Gallagher | Global Risk & Insurance Brokers | 🌱 Emerging Bull | −13.9% | −26.4% |
| Compared against · context, not the story | |||||
MRSH | Marsh & McLennan Companies | Global Risk & Insurance Brokers | 🌱 Emerging Bull | −8.4% | −14.7% |
WTW | Willis Towers Watson Public | Global Risk & Insurance Brokers | 🌱 Emerging Bull | −13.8% | −16.9% |
BRO | Brown & Brown | Retail & Specialty Brokers | 🌱 Emerging Bull | −16.1% | −36.1% |
RYAN | Ryan Specialty | Specialty Lines & Services | 🌱 Emerging Bull | −10.1% | −34.2% |
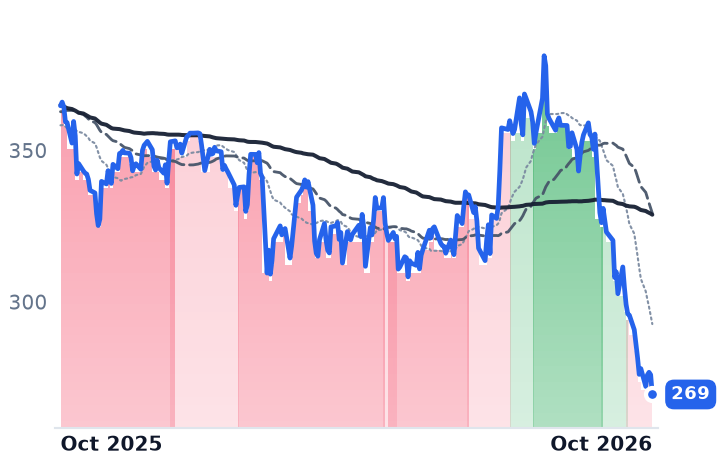
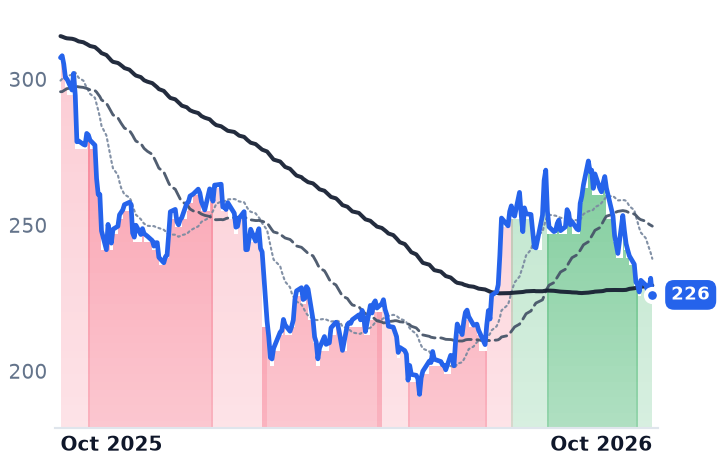
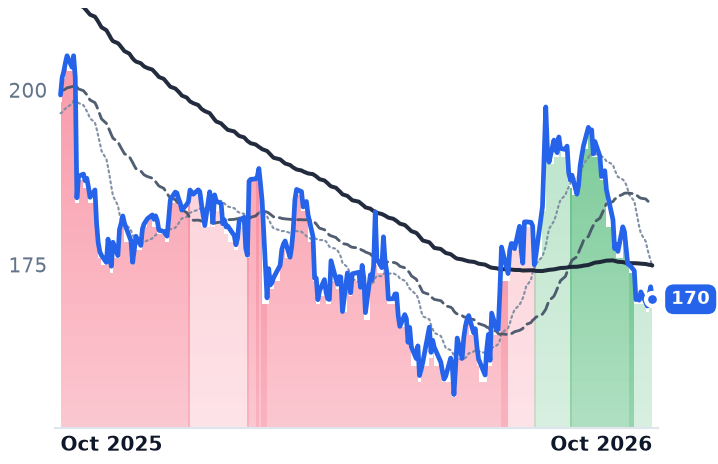
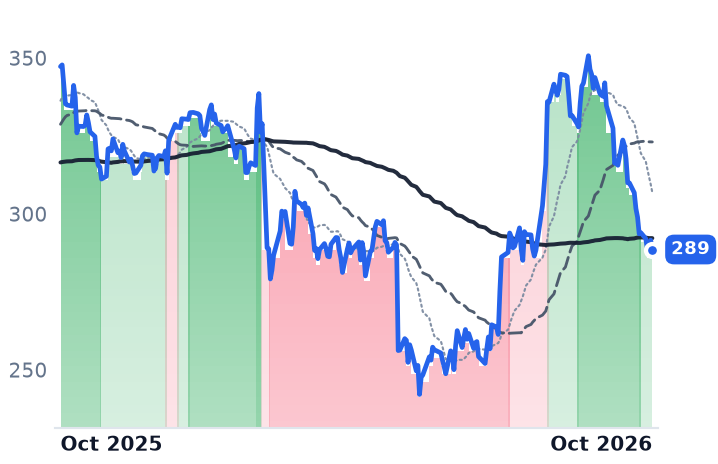
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AON | $57.2B | 14.8x | 14.5x | 3.3x | 3.2x | 3.9x | 3.8x | 11.4x | 5.7% |
AJG | $58.1B | 37.1x | 17.2x | 3.7x | 3.5x | 4.9x | 4.7x | 14.8x | 3.9% |
MRSH | $77.6B | 19.9x | 15.5x | 2.8x | 2.7x | 6.7x | 6.4x | 14.7x | 6.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WTW | $26.8B | 17.7x | 14.6x | 2.7x | 2.6x | 4.9x | 4.8x | 12.0x | 6.3% |
BRO | $21.8B | 18.0x | 14.5x | 3.2x | 3.1x | 5.4x | 5.3x | 11.9x | 6.9% |
RYAN | $4.1B | 31.3x | 15.6x | 1.3x | 1.3x | 1.6x | 1.5x | 9.6x | 13.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AON | Revenue | +3.8% | +17.2% | +6.2% |
| EPS | +9.9% | +9.5% | +15.9% | |
AJG | Revenue | +20.1% | +8.8% | +9.1% |
| EPS | +23.3% | +13.0% | +12.0% | |
MRSH | Revenue | +5.5% | +5.0% | +5.1% |
| EPS | +8.4% | +8.8% | +8.9% | |
WTW | Revenue | +8.7% | +5.3% | +5.6% |
| EPS | +16.8% | +15.4% | +18.6% | |
BRO | Revenue | +17.6% | +4.3% | +5.9% |
| EPS | +5.7% | +7.8% | +9.0% | |
RYAN | Revenue | +6.0% | +8.3% | +10.1% |
| EPS | +1.3% | +14.0% | +15.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Every one of Aon's four business lines grew 5% organically in the June quarter, the Dublin-headquartered broker's adjusted operating margin widened, and the shares have spent the three months since falling to their lowest level in a year. Aon closed October 2 at $269.45 — exactly its 52-week low, and 29.3% below the $381.26 it traded at within the past twelve months.
The selling deepened rather than settled after mid-September, when Aon placed $13.5bn of bonds to fund its purchase of USI Insurance Services into roughly $65bn of orders and the equity kept sliding regardless. Over the thirty days to October 2, Aon fell 18.6% and Arthur J. Gallagher — the Rolling Meadows brokerage and claims administrator that places retail and wholesale property-casualty and employee-benefit cover and runs the Gallagher Bassett claims business — fell 14.5%. The next hard tests are dated: Marsh & McLennan reports on October 15, Gallagher on October 29 and Aon on October 30.
The premium is softening; the commission is not collapsing
A broker is paid a share of a premium it does not set, so the premium cycle is the revenue cycle. Marsh's own quarterly index put global commercial insurance rates down 6% in the June quarter, the eighth consecutive quarterly decline, on abundant capacity and strong insurer profitability. But the softness is concentrated: within that composite, property rates fell 12% while casualty rates rose 2% on US claims severity and litigation. Gallagher's own client renewals split the same way, property premiums down 6% and casualty up 5%.
That is why the commission meter has kept running. Aon's reported revenue rose only 2.0% to $4.2bn in the June quarter, but the company reconciles that to 5% organic growth, a point of favorable currency and four points of drag from selling the NFP Wealth business and Stroz Friedberg. Commercial Risk, Reinsurance, Health and Wealth each grew 5%; Reinsurance Solutions alone turned over $711m. Adjusted operating margin reached 28.9% against 28.2% a year earlier. On reported figures the margin went the other way, to 19.4% from 20.7%, which is amortization, restructuring and transaction costs rather than a thinner commission.
One line did shrink. Fiduciary investment income — the yield Aon earns on client premium it holds in trust between the insured and the underwriter — fell 12% to $58m, which the company attributes to "lower interest rates and average balances". The yield half of that explanation is now running backwards: the Federal Reserve raised its target to 3.75–4.00% in September, with futures pointing to about 4.1% by January. What remains is the balance half — a smaller premium pool to hold.
The self-inflicted part
Aon agreed on August 31 to buy USI, the tenth-largest US broker with roughly $3bn of revenue, from KKR and other holders for $17.0bn in cash, targeting $395m of annual run-rate synergies. Chief executive Gregory Case said the deal would "position Aon to accelerate organic growth" in the US middle market. It is funded entirely with debt, lifts pro-forma leverage to 4.3–4.5 times earnings before interest, tax, depreciation and amortization from 2.7 times, has suspended buybacks until that unwinds, and adds to adjusted earnings per share only in 2028. Aon paid 14.5 times earnings for USI; Gallagher paid 11.3 times for AssuredPartners.
Where the four trade
Aon's $269.45 is 14.5 times the $18.64 consensus for this year — a figure trimmed less than 1% since mid-September — against the 19.4 times its price a year ago implied on effectively the same estimate. It is also the cheapest of the four on enterprise value against cash earnings, at 11.4 times, a reading that predates the USI debt. Gallagher has fallen from 23.4 times forward earnings a year ago, and 26.7 times two years ago, to 17.2 times — and is still the group's dearest name on forward earnings, at 14.8 times on enterprise value and with a 3.94% free-cash-flow yield, the lowest of the four. Keefe, Bruyette & Woods cut its target to $250 from $271 on September 24, expecting "slowly-decelerating middle-market property and casualty pricing to constrain overall organic growth in the near term." Marsh & McLennan, with the largest consulting offset, de-rated least, to 17.7 times forward earnings; Willis Towers Watson, the smallest, is the only one of the four whose reported revenue is accelerating, up 9.1% in the June quarter.
What earns the fall and what does not
The twelve-month de-rating has a datable origin the operating numbers never touched. On February 9, OpenAI approved Insurify's app letting ChatGPT users pull personalized homeowners quotes, and Bank of America sized $15bn of low-complexity commissions as exposed to disintermediation. Willis fell 12.1% that session, Gallagher 9.9%, Aon 9.3%. Goldman Sachs called the move "disconnected from near-term fundamentals" and "overdone"; Barclays upgraded Gallagher in March with a $262 target, 13.7% above where the stock now sits.
So the fall divides cleanly. Gallagher's is a premium being normalized — it bought $13.45bn of revenue, diluted its share count 15.5% since 2024, and still commands the group's richest valuation on every measure. Aon's is harder to pin on the business: 5% organic growth across all four lines and a wider adjusted margin do not produce a 25% fall in the share price. Part of it Aon did to itself, trading a 2.7-times balance sheet and its buyback for an asset that pays back in 2028. The rest is a market pricing the terminal value of a commission rather than this year's. Nothing in the brokers' reported organic growth has yet confirmed it.
The first number comes from inside the group: Marsh reports on October 15, and with it the index that tells its three rivals what their commissions are a percentage of.