

Century Aluminum Sold a Smelter's 480 Megawatts; TeraWulf Leased 401 of Them to Anthropic
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
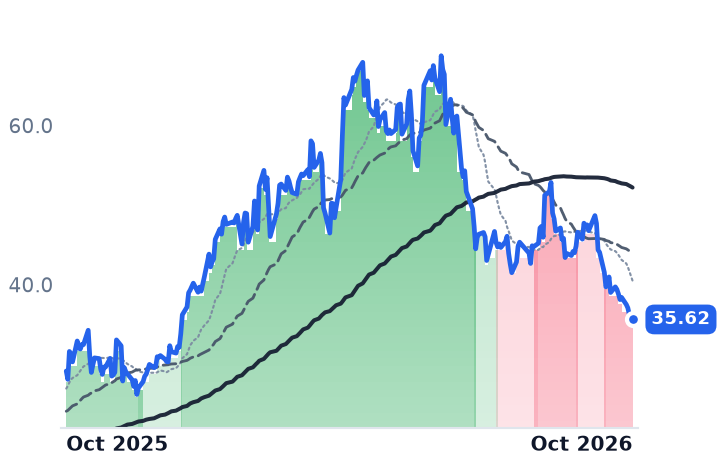
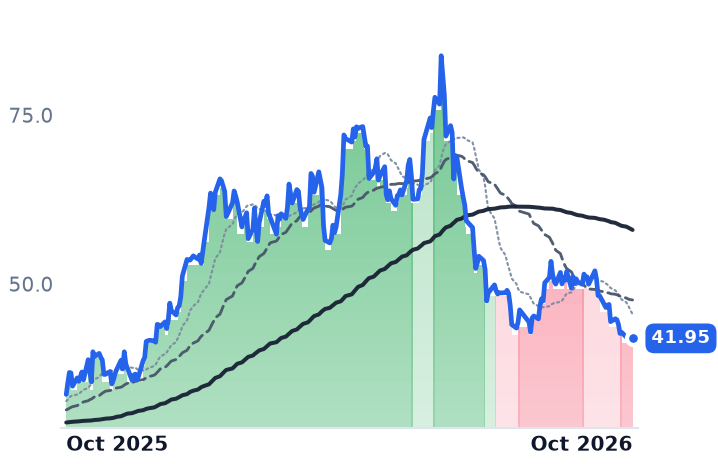
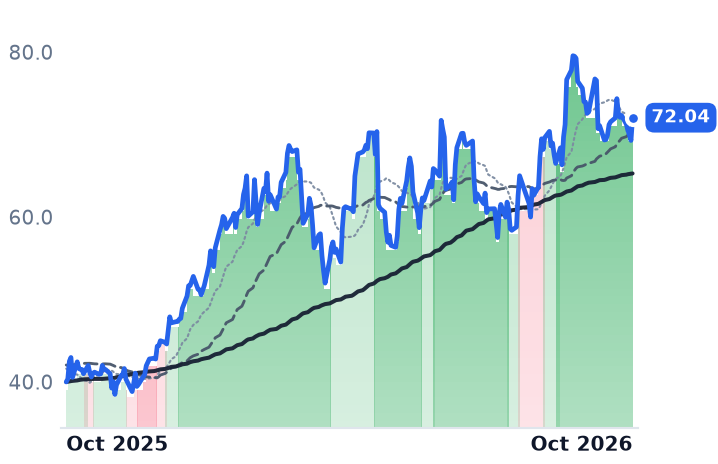
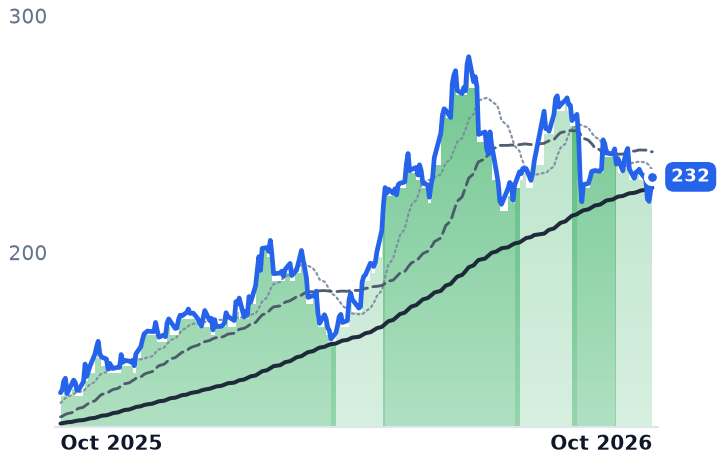
The two best operating quarters on America's metals shelf belong to the two worst share prices. Century Aluminum earned a record $327m of adjusted EBITDA in the June quarter at a 30.3% gross margin, and Alcoa reported record aluminum-segment profit — then both stocks halved from a high they reached on the same day in June.
Electricity sorts the group. Power at the Indiana hub serving Century's Sebree smelter has gone from $31 to $57 a megawatt-hour in two years, against the $40 ceiling the Aluminum Association says a new US smelter can bear. Copper miners sell into the grid buildout; aluminum smelters bid against it for the same electrons. The halving itself traces to the metal — aluminum is 18% off its June peak — and, at Alcoa, to the debt and the shares issued for South32's bauxite and alumina assets.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
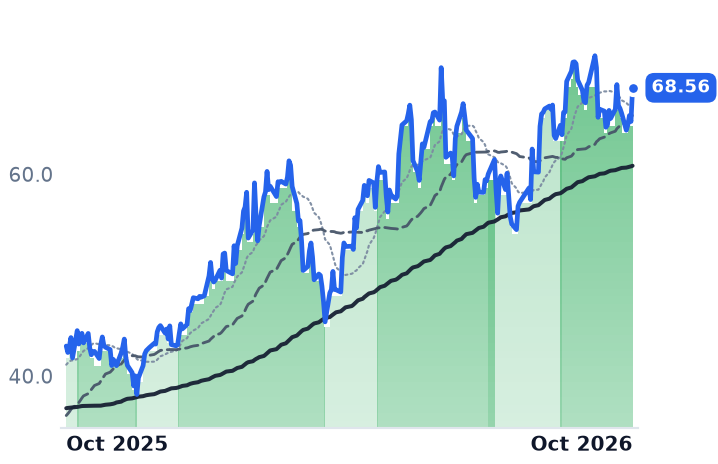
CENX | Century Aluminum | Aluminum | ⚠️ Emerging Bear | −23.8% | +22.2% |
AA | Alcoa | Aluminum | 🔴 Cont. Bear | −16.0% | +24.7% |
CLF | Cleveland-Cliffs | Flat-Rolled Steel | 🟢 Cont. Bull | −9.4% | −10.4% |
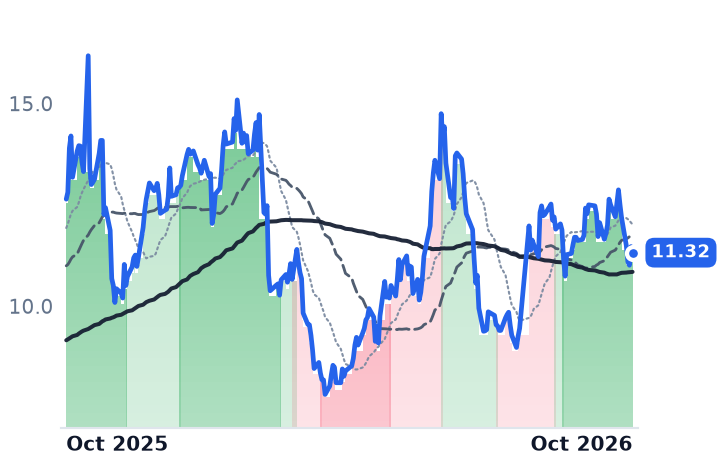
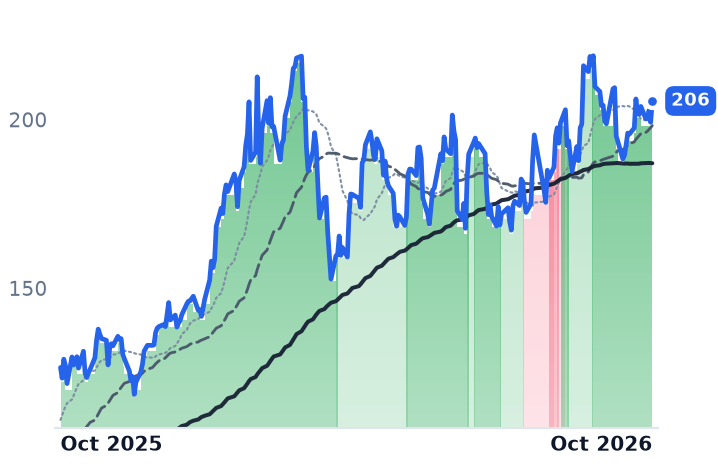
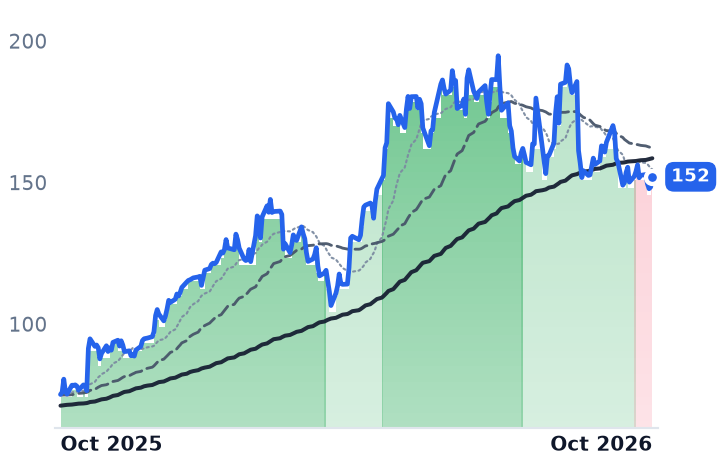
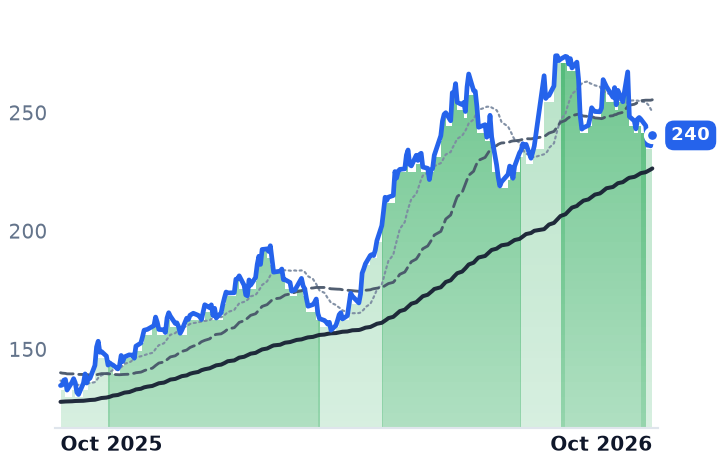
SCCO | Southern Copper | Copper | 🟢 Cont. Bull | +3.4% | +62.5% |
FCX | Freeport-McMoRan | Copper | 🟢 Cont. Bull | −0.9% | +80.2% |
TECK | Teck Resources | Major Diversified Mining | 🟢 Cont. Bull | −0.8% | +59.6% |
KALU | Kaiser Aluminum | Aluminum | 🟢 Cont. Bull | −7.4% | +102.4% |
NUE | Nucor | Integrated Steelmakers | 🟢 Cont. Bull | −7.9% | +78.5% |
STLD | Steel Dynamics | Long Products & Rebar | 🟢 Cont. Bull | −4.2% | +64.8% |
RIO | Rio Tinto | Major Diversified Mining | ⚠️ Emerging Bear | −8.8% | +44.6% |
PKX | POSCO | Integrated Steelmakers | 🔴 Cont. Bear | −8.2% | +18.5% |
MT | ArcelorMittal | Integrated Steelmakers | 🟢 Cont. Bull | −18.1% | +67.7% |
BHP | BHP | Major Diversified Mining | 🟢 Cont. Bull | −4.8% | +56.8% |
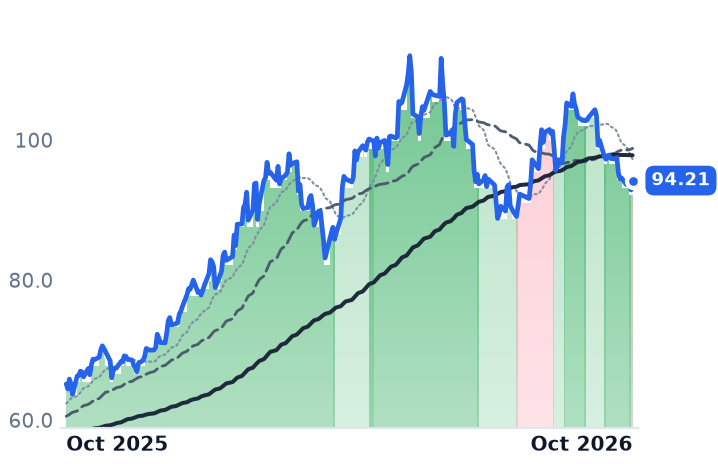
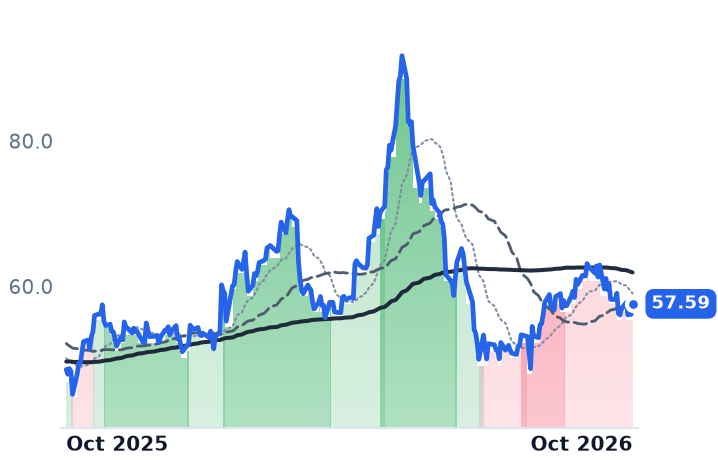
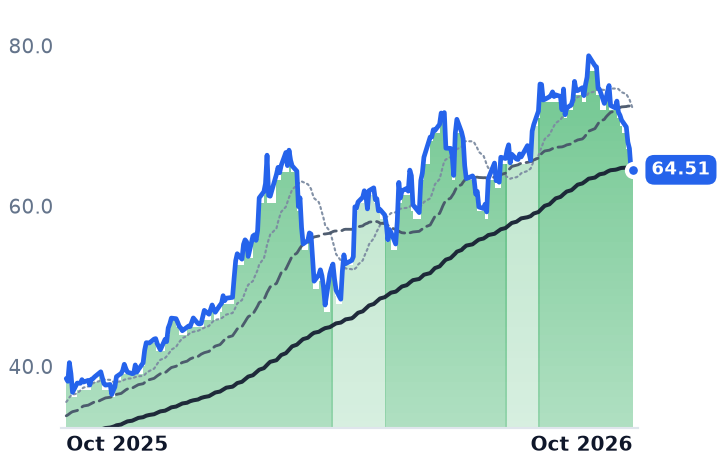
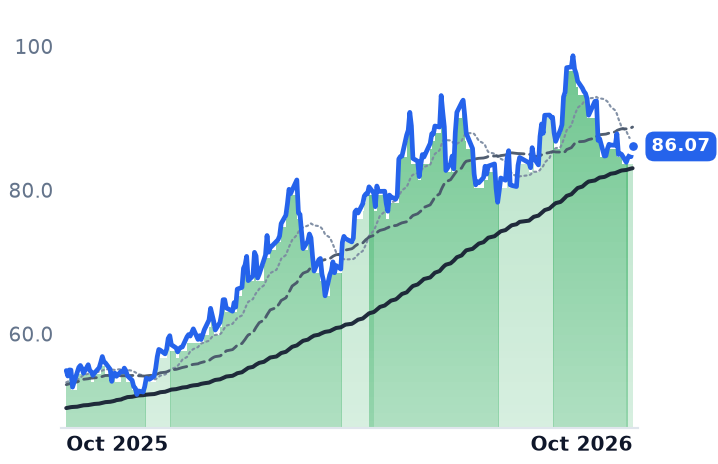
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CENX | $3.5B | 5.8x | 3.5x | 1.3x | 1.0x | 6.9x | 5.4x | 5.1x | 4.3% |
AA | $11.1B | 8.5x | 6.5x | 0.8x | 0.7x | 4.3x | 4.0x | 6.0x | 3.2% |
CLF | $6.5B | n/m | — | 0.3x | 0.3x | — | — | 22.7x | -13.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SCCO | $171.5B | 30.1x | 26.8x | 10.9x | 10.1x | 17.4x | 16.2x | 17.6x | 3.5% |
FCX | $103.6B | 35.5x | 24.2x | 4.0x | 3.5x | 14.9x | 13.1x | 12.2x | 5.7% |
TECK | $33.1B | 19.1x | 11.4x | 3.4x | 2.2x | 9.7x | 6.3x | 7.9x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KALU | $2.5B | 10.9x | 10.8x | 0.6x | 0.5x | 5.2x | 4.5x | 7.4x | 3.5% |
NUE | $54.7B | 19.2x | 12.7x | 1.5x | 1.3x | 9.8x | 8.7x | 10.5x | 2.9% |
STLD | $33.3B | 21.0x | 13.3x | 1.6x | 1.4x | 11.1x | 9.5x | 12.4x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RIO | $153.1B | 12.6x | 11.3x | 2.5x | 2.4x | 9.0x | 8.8x | 6.9x | 3.8% |
PKX | $17.4B | 17.5x | — | 0.3x | — | 4.2x | — | 7.9x | -9.1% |
MT | $49.1B | 27.0x | 15.1x | 0.8x | 0.7x | 8.1x | 7.7x | 9.0x | -2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BHP | $218.6B | 22.0x | 17.6x | 3.7x | 3.8x | 4.9x | 5.1x | 7.7x | 5.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CENX | Revenue | +32.6% | +21.2% | −2.6% |
| EPS | +359.7% | +10.4% | +39.8% | |
AA | Revenue | +17.0% | +2.2% | −4.5% |
| EPS | +82.3% | −6.9% | +7.0% | |
CLF | Revenue | +14.0% | +3.5% | −0.9% |
| EPS | −92.9% | −530.4% | −40.0% | |
SCCO | Revenue | +29.2% | −4.2% | −0.8% |
| EPS | +50.0% | −6.3% | −4.4% | |
FCX | Revenue | +15.7% | +20.0% | +3.0% |
| EPS | +91.4% | +35.7% | +14.0% | |
TECK | Revenue | +41.4% | −0.1% | −15.4% |
| EPS | +128.4% | −14.7% | −25.6% | |
KALU | Revenue | +42.9% | −0.1% | +1.3% |
| EPS | +131.2% | −17.7% | +17.5% | |
NUE | Revenue | +24.3% | +2.6% | +0.3% |
| EPS | +137.3% | +4.2% | −5.1% | |
STLD | Revenue | +30.7% | +1.7% | −0.6% |
| EPS | +118.7% | +16.7% | −8.2% | |
RIO | Revenue | +11.9% | +2.3% | +1.9% |
| EPS | +24.7% | −0.7% | −0.7% | |
PKX | Revenue | +2.2% | +3.8% | +3.2% |
| EPS | +79.8% | +23.3% | +18.6% | |
MT | Revenue | +7.5% | +5.9% | — |
| EPS | +2.6% | +74.3% | — | |
BHP | Revenue | +13.3% | −1.5% | −0.3% |
| EPS | +23.7% | −2.6% | +0.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A dead smelter's interconnect, repriced
Century Aluminum, which runs primary aluminum smelters in the United States and Iceland, fully curtailed its Hawesville, Kentucky plant in August 2022 and never found power cheap enough to restart it. In February it sold the site — more than 750 acres with roughly 480 megawatts available through existing high-voltage transmission and an energized on-site substation — to TeraWulf for $200m in cash plus a 6.8% minority interest in the affiliate developing a data center there. On July 6 TeraWulf disclosed that a subsidiary had signed a 20-year lease with Anthropic for about 401 megawatts of critical computing load at the same address.
That is the clearest price yet on the input that decides whether a US smelter exists at all, and it is why the metals shelf has stopped trading as one thing. The grid buildout is a customer for copper and electrical steel and a competing bidder for the electricity aluminum needs. Alcoa reports third-quarter results on October 15 and Cleveland-Cliffs on October 19, which is when the two sides of that arithmetic next get marked.
The cost side
A single smelter draws roughly 11 terawatt-hours a year, about what a city the size of Boston uses. Century's own slides put power at the Indiana hub serving its Sebree smelter at $57 per megawatt-hour so far in 2026 against a $58 spot, up from $31 in 2024 and $44 last year, and the company guided to $10m to $15m of energy headwind in the third quarter. The Aluminum Association reckons a new smelter needs a 20-year contract at no more than $40 per megawatt-hour; power in the four states holding idle smelter capacity averaged $73.42. Microsoft conceded $115 per megawatt-hour to restart Three Mile Island.
And yet the quarter was the best in Century's history. June-quarter revenue rose 19.7% to $752.1m, gross margin reached 30.3% against 5.8% a year earlier, adjusted EBITDA hit $327m and cash now exceeds total debt. Mt. Holly returned to full capacity for the first time since 2015 on power secured through 2031 from Santee Cooper. Chief executive Jesse Gary said the new tonnes were arriving "into as strong a market as this industry has seen in a very long time," on the second-quarter call.
Alcoa's quarter was the same story at scale: its highest quarterly revenue in a ten-year corporate history and record aluminum-segment EBITDA of $1.1bn at a 32.3% margin. Alcoa is also insulated from the power squeeze for now — under 1% of its electricity is spot-priced, with the rest contracted or hedged — and the cost pressure that did show up was diesel and instability at its Punjab refinery, not electrons.
Both shares peaked on June 2 and both closed at 2026 lows on October 2, down 49.9% and 48.2% from that shared high. London aluminum is 18% off its June four-year peak at $3,115 a tonne, while the Midwest premium that earlier coverage tracked is back near $1.09 a pound, exactly Century's guidance assumption. Century now trades at 3.5x forward earnings against 5.8x trailing, on consensus 2026 earnings of $10.04 a share versus $0.42 reported for 2025. Alcoa's 6.5x forward against 8.5x trailing is harder to call dislocation: it is funding South32's bauxite, alumina and aluminum assets for $4.1bn upfront with $2.6bn of 6.63% and 6.88% notes plus 17m new shares, roughly 6% dilution, and fell 9% the day it was announced.
The demand side
Copper reached an all-time $14,617 a tonne in early September on grid and data-center demand against constrained mines. Southern Copper, which mines and refines copper and molybdenum in Peru and Mexico, ran a 62% gross margin on revenue up 40.6%, and by-product credits took its first-half net cash cost to minus three cents a pound — it is the most expensive name here at 26.8x forward earnings. Teck Resources grew revenue 78.3% with gross margin widening 21 points, and is the cheapest of the three at 11.4x forward against 19.1x trailing. Freeport-McMoRan is the exception: June-quarter revenue fell 7.3% and gross margin slipped, Grasberg milled about 67% of pre-incident rates last quarter, and the shares carry 24.2x forward on a 2027 recovery.
Cleveland-Cliffs, the only US producer of grain-oriented electrical steel and the flat-rolled supplier to Detroit, turned a positive gross margin for the first time in six quarters, with $286m of adjusted EBITDA, selling prices up $76 a ton and automotive shipments the highest in two years. It trades at 1.15x book because consensus still has it loss-making this year. The transformer-assembly leg of its grid story is gone — the Weirton plant was shelved — leaving the electrical-steel franchise to carry it.
What the power channel does and does not explain
Electricity does not explain this quarter's aluminum numbers; the margins were records and Alcoa's hedges hold. What it explains is the terminal value a buyer will pay for a smelter: every megawatt-hour the data centers bid up raises the cost of the next restart and the price of the next contract renewal, and Hawesville showed the land is worth more without pot lines on it. The halving is the metal price plus, at Alcoa, a genuine change in the equity's risk from near-7% debt and fresh shares. Nothing in either company's operating record explains the rest of it. On the other side, the grid bill of materials is being paid for in cash at Teck and Southern Copper and borrowed against the future at Freeport.
Century once employed hundreds of people at Hawesville turning electricity into metal. The same wires now carry a 20-year lease.