

Liberty, ProPetro and ProFrac Depreciated $295m of Iron Against $265m of Cash Earnings
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Three American frac pumpers ran their equipment harder in the June quarter than ever before, and all three are worth less than they were in July. The explanation is not a thinning completions market — the US frac spread count reached 195 on October 1, and oilfield service pricing turned positive in the Dallas Fed's third-quarter survey.
What the income statements show instead is depreciation eating the cash. Liberty Energy earned $151m before depreciation last quarter and $12.7m after it; ProPetro's annualized depreciation of roughly $199m exceeds the $186m of full-year cash earnings analysts expect it to produce. Liberty is also committing about $1.5bn of capital this year, most of it deposits on power-generation equipment.
Liberty and ProPetro are being repriced for that capital claim rather than for pumping. ProFrac, whose net debt exceeds its market value, earns its decline.
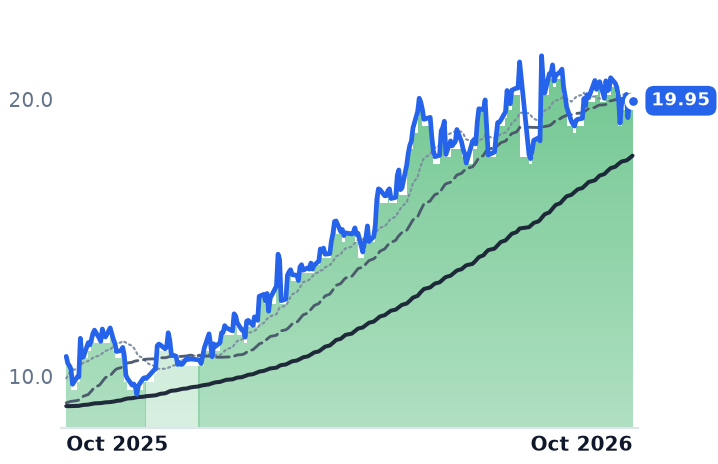
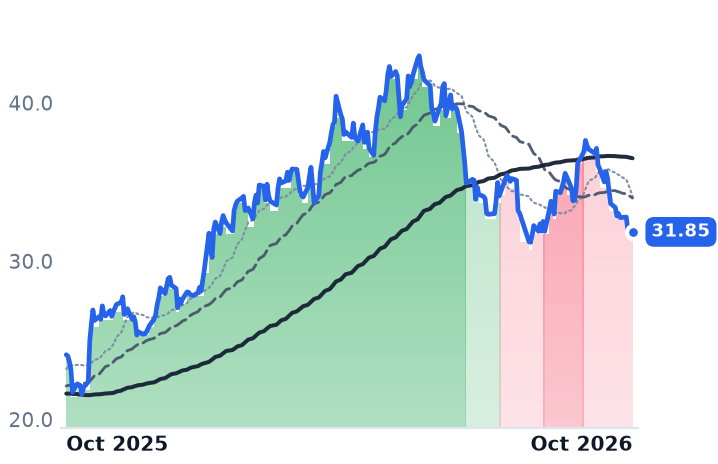
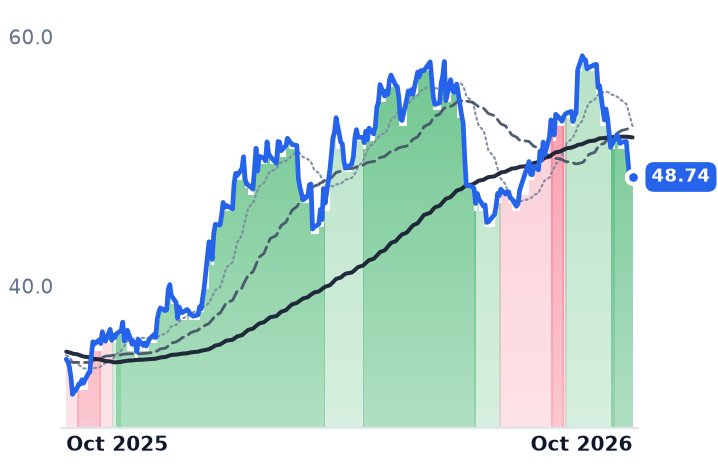
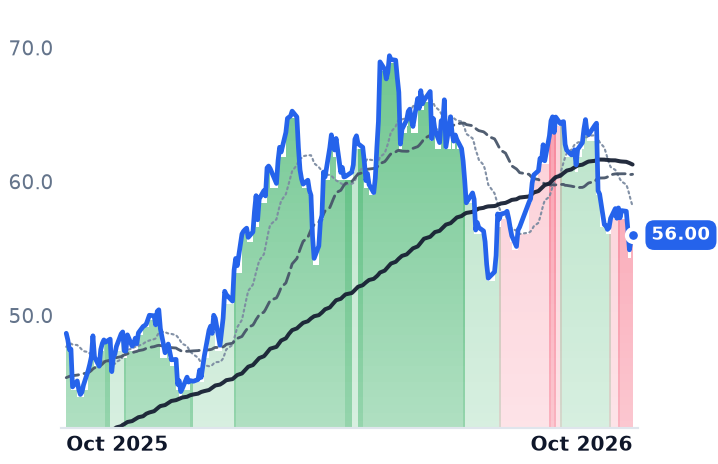
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
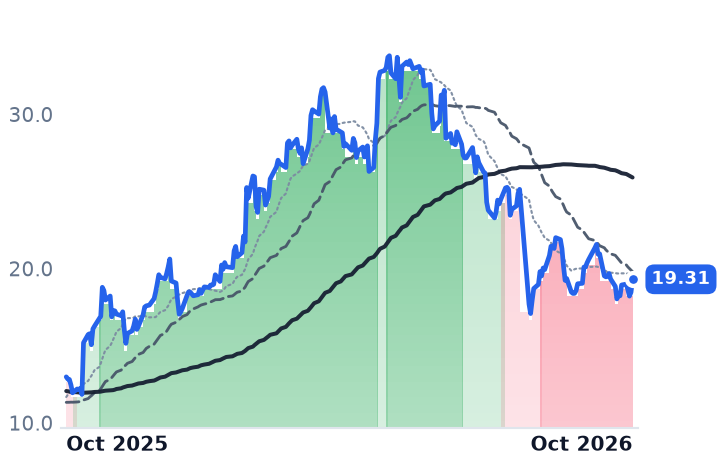
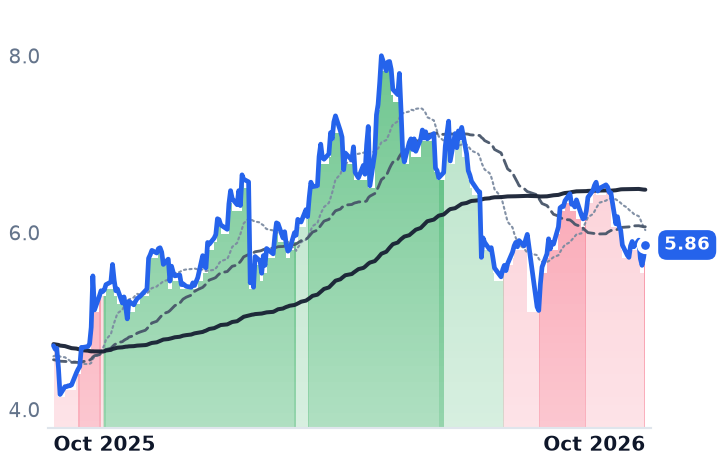
LBRT | Liberty Energy | Well Services & Stimulation | ⚠️ Emerging Bear | −6.2% | +48.7% |
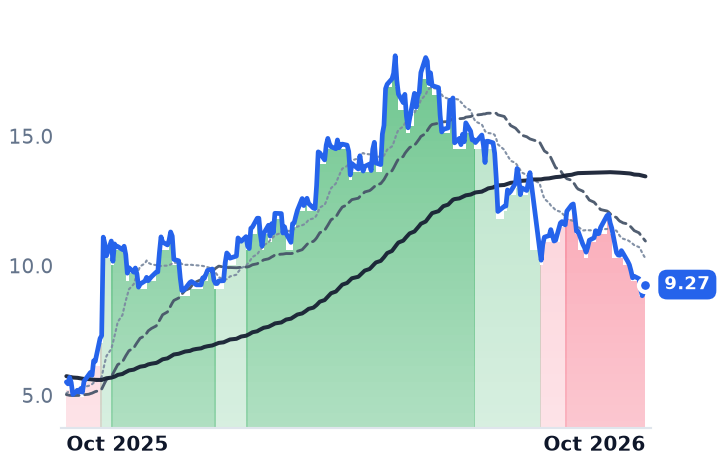
PUMP | ProPetro | Well Services & Stimulation | ⚠️ Emerging Bear | −19.2% | +68.2% |
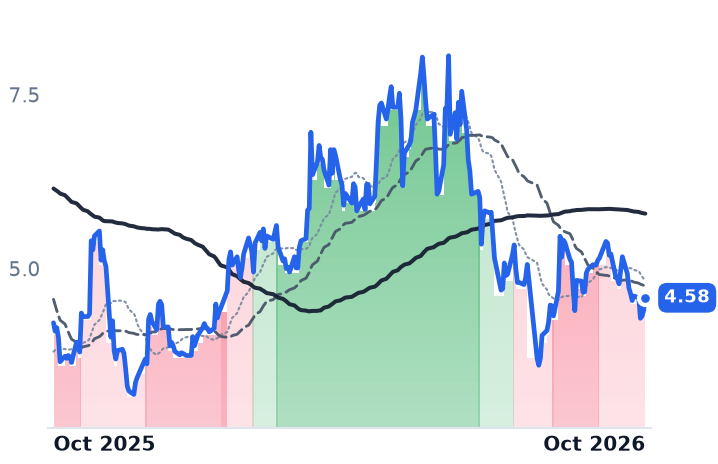
ACDC | ProFrac | Well Services & Stimulation | ⚠️ Emerging Bear | −11.1% | +8.5% |
| Compared against · context, not the story | |||||
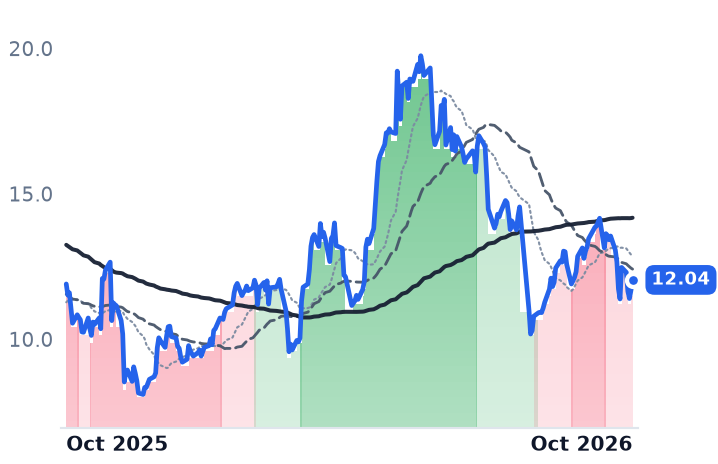
AESI | Atlas Energy Solutions | Proppant & Logistics | ⚠️ Emerging Bear | −10.5% | +1.2% |
WTTR | Select Water Solutions | Water Services & Energy Solutions | 🟢 Cont. Bull | −0.5% | +86.1% |
HAL | Halliburton | Well Services & Stimulation | ⚠️ Emerging Bear | −14.1% | +32.2% |
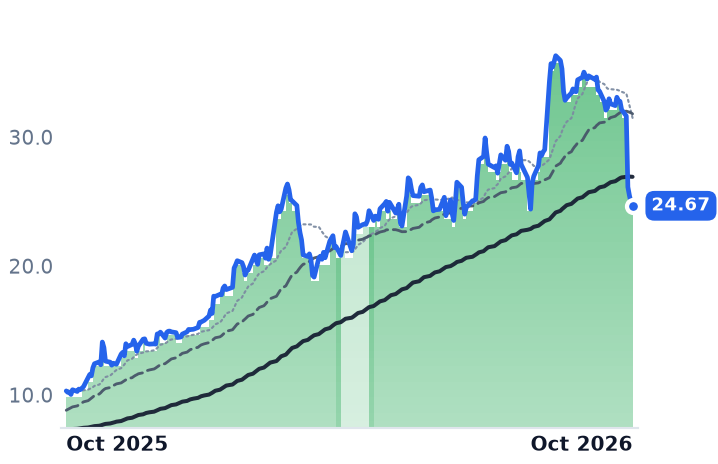
SLB | Slb | Well Services & Stimulation | 🟢 Cont. Bull | −15.2% | +42.9% |
BKR | Baker Hughes | Well Services & Stimulation | ⚠️ Emerging Bear | −11.8% | +15.1% |
RES | RPC | Well Services & Stimulation | ⚠️ Emerging Bear | −9.8% | +24.1% |
NESR | National Energy Services Reunited | Well Services & Stimulation | 🟢 Cont. Bull | −29.0% | +139.3% |
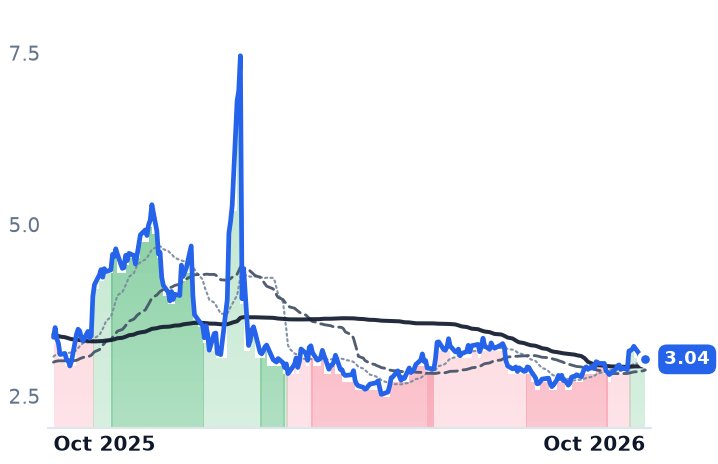
NG=F | NG=F | — | 🔴 Cont. Bear | +2.0% | −9.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LBRT | $3.2B | 25.6x | 83.1x | 0.8x | 0.7x | 5.8x | 5.4x | 6.8x | -10.0% |
PUMP | $1.1B | n/m | — | 1.0x | 0.9x | 11.8x | 11.2x | 7.2x | -2.0% |
ACDC | $828.6M | n/m | — | 0.5x | 0.4x | 10.2x | 9.1x | 15.3x | -7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AESI | $1.5B | n/m | — | 1.4x | 1.3x | 33.9x | 32.4x | 20.8x | -12.2% |
WTTR | $2.2B | 73.6x | 30.6x | 1.5x | 1.4x | 8.0x | 7.4x | 10.3x | -3.7% |
HAL | $28.1B | 17.6x | 14.4x | 1.3x | 1.3x | 8.3x | 8.3x | 8.3x | 6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
BKR | $62.0B | 19.9x | 23.7x | 2.2x | 2.2x | 9.5x | 9.4x | 13.2x | 5.0% |
RES | $1.5B | 65.8x | 26.8x | 0.8x | 0.8x | 8.6x | 8.4x | 6.1x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NESR | $2.6B | 39.7x | 15.9x | 1.8x | 1.4x | 16.0x | 12.4x | 11.0x | 4.9% |
NG=F | — | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LBRT | Revenue | +18.2% | +7.7% | +13.9% |
| EPS | −465.4% | −56.9% | +509.6% | |
PUMP | Revenue | −2.9% | +16.9% | +10.6% |
| EPS | −26.6% | −893.3% | +68.4% | |
ACDC | Revenue | +4.6% | +10.8% | −4.3% |
| EPS | −22.0% | −44.0% | −78.7% | |
AESI | Revenue | +2.6% | +16.2% | +20.0% |
| EPS | +111.3% | −76.8% | −201.2% | |
WTTR | Revenue | +12.3% | +8.4% | +4.8% |
| EPS | +166.8% | +2.6% | +55.9% | |
HAL | Revenue | +2.0% | +5.4% | +4.3% |
| EPS | +3.1% | +23.2% | +16.1% | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
BKR | Revenue | +2.3% | +10.9% | +7.5% |
| EPS | +6.7% | +14.6% | +20.0% | |
RES | Revenue | +12.5% | +2.1% | +2.7% |
| EPS | −15.0% | +4.1% | +35.2% | |
NESR | Revenue | +41.8% | +22.0% | +18.3% |
| EPS | +111.9% | +47.6% | +29.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Liberty Energy, which rents hydraulic fracturing horsepower to North American oil and gas producers, ran its pumps harder in the June quarter than at any point in its history. It set records for pump hours, horsepower hours and pump utilization, earned $151m of adjusted earnings before interest, taxes, depreciation and amortization on $1.19bn of revenue, and reported operating income of $12.7m.
The gap between those two figures — roughly $138m for the quarter — is depreciation, and in pressure pumping it is not an abstraction. The record utilization that produces the cash is the same thing that consumes the fleet, and the charge is a standing bill for replacing iron. Add ProPetro's implied $50m and ProFrac's $107m, and the three biggest independent American pumpers generated about $265m of cash earnings in the quarter against roughly $295m of wear. That arithmetic, rather than a slowing market, is what the past three months of share prices have been reckoning with: Liberty is down 19% and ProPetro 23% since early July, while the diversified service majors SLB and Baker Hughes rose 8% and 6%.
Demand got better, not worse
The completions market these companies serve expanded through the period. Primary Vision's count of working frac spreads rose by eight to 195 on October 1, against roughly 169 a year earlier, with the US rig count at 599. The Dallas Fed's third-quarter energy survey showed its index of prices received for oilfield services swing from -30.0 to 9.3 — services pricing turned up in the quarter.
Managements describe a tightening market. "We're beginning to see positive pricing momentum," ProPetro chief executive Sam Sledge told investors after the second quarter, as customers recognize the limited availability of next-generation gas-burning fleets; the industry, he said, has "consolidated through attrition," with much of the excess capacity that once weighed on pricing now gone. The one-month slide across the whole complex is better explained by crude: Brent fell from above $105 a barrel in mid-September to $97.44 on September 30 as Saudi exports recovered, and the majors fell with the pure plays.
The second claim on the same cash
What separates the pumpers is a second demand on cash that depreciation has already laid claim to. Liberty expects roughly $1.5bn of capital expenditure in 2026, mostly deposits on long-lead power-generation equipment; net debt rose $157m in the quarter to $736m. Its filings show equipment supply contracts worth about $1.3bn, with $1.1bn still committed at June 30, plus a further $801m order signed with Caterpillar on July 22. Shares fell 13.7% on a quarter that beat both revenue and earnings estimates.
That spending buys a different business. "We have line of sight to that inbound 3 gigawatts, and even beyond that, we have line of sight to our growth headed out into late 2029 and early 2030," chief executive Ron Gusek said on the July 23 call, referring to the company's power platform. UBS, which cut its price target to $31 from $35 while keeping a Buy rating, reckons the market is paying only $2 to $4 a share for that platform against its own $14 estimate, and models third-quarter EBITDA of $143m against a Street figure of $156m. Liberty trades at 6.8 times trailing cash earnings and 1.60 times book, yet 83 times forward earnings — the same depreciation fact, seen through the income statement.
ProPetro, a Permian-focused pumper, is the cleaner case. It raised its active fleet count from 11 to 12 and grew adjusted EBITDA 23% sequentially to $45m, 15% of revenue, and its shares still fell a third over six months. Annualized, its depreciation of about $199m exceeds the $186m of 2026 EBITDA analysts expect — the pumping fleet does not earn its own replacement. Its power unit, PROPWR, added roughly 230 megawatts of committed capacity through long-term contracts with a Targa Resources subsidiary signed September 22, taking contracted capacity to about 510 megawatts. The shares sit at 1.19 times book and 7.2 times cash earnings.
ProFrac, which pumps with captive proppant and its own pump manufacturing, earns its decline. Revenue of $498m and adjusted EBITDA of $69m came with a $79.7m net loss, and net debt of $1.08bn against $72m of liquidity exceeds its $829m market value. At more than 15 times cash earnings it is the most expensive of the three, with consensus 2026 earnings at -$1.34 a share.
The layers beneath split on contract tenor
The service layers around the wellbore did not move together, which rules out a simple read on completions demand. Atlas Energy Solutions, the Permian sand and conveyor-logistics supplier, sold a record 5.6m tons of proppant at $17.70 a ton against $12.39 of plant cost and has fallen 17% over three months, with third-quarter EBITDA guided to $30m-$45m. Select Water Solutions, which gathers, recycles and disposes of produced water through owned pipelines, is up 11% over the same span on 12-year dedications across more than 875,000 Northern Delaware acres and infrastructure revenue up 26% at a 58.3% gross margin. Both consume more cash than they make; what divides them is the length of the contract, not whether it is priced per ton or per hour.
What the market is actually marking down
Nothing in these businesses supports the thesis of a thinning completions market, and the pricing data points the other way. What is being repriced at Liberty and ProPetro is the claim on cash: a fleet that depreciates faster than it earns operating income, now sharing the balance sheet with turbine and engine deposits that pay back over five or six years. ProFrac has no such second story, and its leverage is doing the work there. The uncomfortable implication is that for a pumper, depreciation functions as a cash commitment, so the pricing uplift managements have promised since July only matters at the margin above the replacement bill — which is precisely why both Liberty and ProPetro are pointing capital at contracted power, where an asset earns for 15 years instead of consuming itself in three.
Liberty's third-quarter report, due around October 14, will say whether that uplift arrives in cash or only in commentary. In this business the quarter that earns the most is also the quarter that wears out the most.