

Packaging Corp Guided to $2.91 a Share After Four Quarters of Falling Operating Income
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
North America's containerboard producers finally got the two data points they wanted — the September index recognized a $70-a-ton linerboard increase, and recycled-fiber prices stopped climbing in October — and their shares broke anyway in the five sessions to 2 October: International Paper down 8.7%, Smurfit Westrock 8.3%, Packaging Corp 3.6%, against a market that barely moved. No company-specific news is discoverable in that window.
The group does not split evenly. Packaging Corp has grown revenue faster for four straight quarters while operating income fell in every one, and trades at 21.8x forward earnings. Smurfit Westrock's operating margin has roughly halved, to 3.85%, at 8.6x trailing EV/EBITDA. Packaging Corp's own guidance of $2.91 for the September quarter, reported 21 October, is the first clean test of whether the increase converts.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
IP | International Paper | Corrugated & Containerboard | 🌱 Emerging Bull | −14.2% | −28.8% |
PKG | Packaging Corporation of America | Corrugated & Containerboard | 🟢 Cont. Bull | −3.7% | +8.6% |
SW | Smurfit Westrock | Corrugated & Containerboard | 🟢 Cont. Bull | −7.2% | +6.5% |
| Compared against · context, not the story | |||||
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IP | $16.9B | n/m | 23.9x | 0.7x | 0.7x | 2.5x | 2.5x | n/m | 2.9% |
PKG | $20.4B | 29.6x | 21.8x | 2.1x | 2.0x | 10.6x | 10.0x | 13.1x | 3.6% |
SW | $22.3B | 47.3x | 19.2x | 0.7x | 0.7x | 4.2x | 3.9x | 8.6x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IP | Revenue | −0.1% | +5.9% | +1.6% |
| EPS | +455.8% | +127.8% | +15.5% | |
PKG | Revenue | +11.0% | +7.6% | +2.6% |
| EPS | +5.5% | +29.9% | +4.9% | |
SW | Revenue | +3.1% | +5.8% | +2.2% |
| EPS | −7.5% | +57.4% | +13.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A price increase landed; the shares came off
Containerboard's third price increase of 2026 showed up in the published benchmark last month. Fastmarkets RISI recognized linerboard up $70 a ton and corrugating medium up $100 month over month — the first movement of a round in which Packaging Corporation of America had announced $140, Smurfit Westrock $100 and International Paper $80. Then the cost leg turned the producers' way: old corrugated containers' eleven-month price run ended in October, flat in most regions and down $10 a ton on the Los Angeles and San Francisco docks.
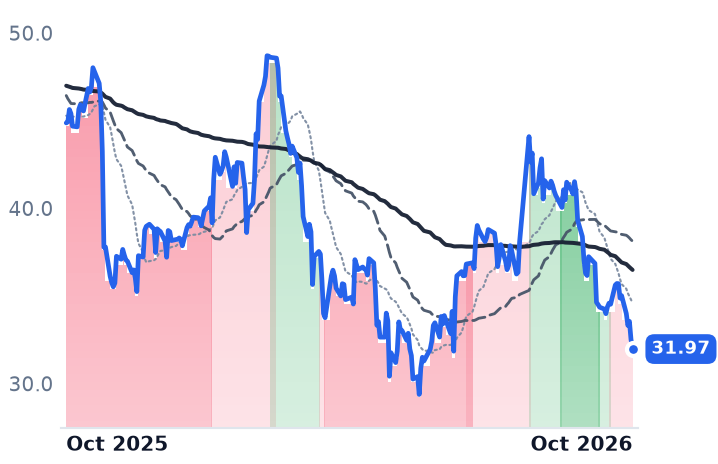
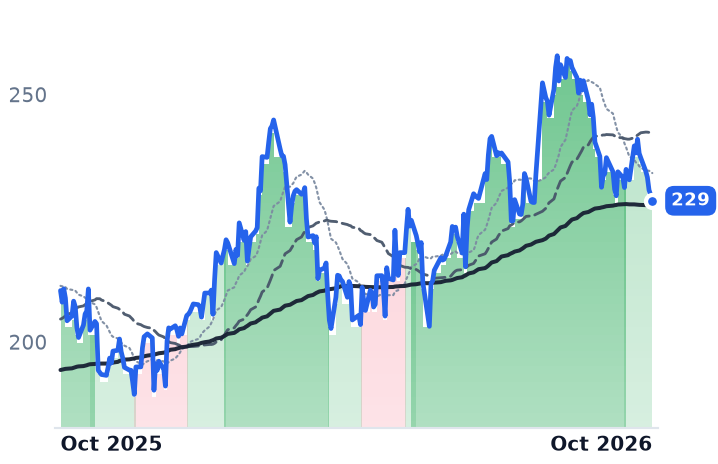
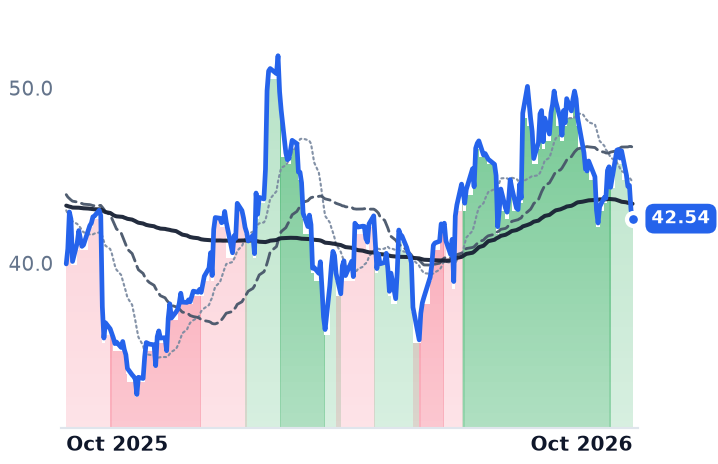
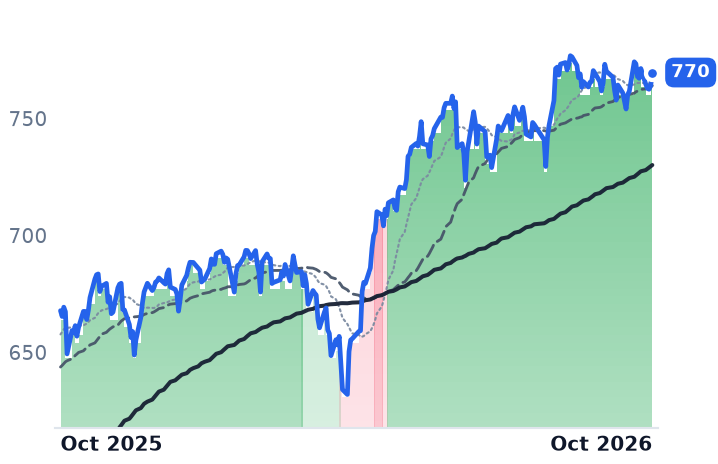
Both items widen the spread between what a mill sells a ton of board for and what it pays to make one. Yet over the five sessions to 2 October, International Paper fell 8.7% to $31.97, Smurfit Westrock 8.3% to $42.54 and Packaging Corp 3.6% to $228.54, while the S&P 500 tracker slipped 0.2% and the average change across 3,297 priced symbols was −0.9%. All three had rolled over from summer uptrends in mid-September. What settles the argument is dated: Packaging Corp reports after the close on 21 October, guided to $2.91 a share excluding special items, and International Paper on 28 October.
Revenue up, profit flat
Packaging Corp makes containerboard and converts it into shipping boxes, retail displays and protective packaging, with a smaller segment selling cut-size office paper. June-quarter revenue rose 14.7% to $2.49bn, helped by the Greif containerboard business bought for $1.8bn in September 2025; operating income was flat at $333.2m. That completes four consecutive quarters of accelerating revenue growth — 6.0%, 10.1%, 10.6%, 14.7% — in which operating income fell year over year every time. The operating margin compressed to 13.4% from 15.4%. Volumes are the best in the group: total corrugated shipments rose 24.3% per day and legacy shipments 4.1% per day to a quarterly record. At 21.8x forward earnings and 13.1x trailing EV/EBITDA it is the most expensive of the three, priced for consensus earnings of $13.61 a share in 2027 against $10.48 this year.
The two cheap ones, and why
International Paper's June quarter was the worst in the group: revenue down 11.3% to $6.00bn, operating income down 78% to $45m — an operating margin of 0.75% — and a $12m net loss. After a $3.52bn loss in 2025 its trailing earnings and enterprise multiples are unusable; the anchors are 0.70x sales, 1.17x book and roughly 10.5x 2027 consensus earnings of $3.04. The business is taking share in a shrinking market, with North American box volumes up 1.7% a day against industry shipments down 1.9%, and it is withdrawing supply it controls: five sites closing for an expected $230m earnings improvement, the Georgetown pulp mill shut, $500m of DS Smith synergies targeted by 2027. "We are taking cost and complexity out of the business," chief executive Andy Silvernail told investors on the 30 July second-quarter call, on which management also cut its second-half demand assumption to generally stable.
Smurfit Westrock, the Dublin-headquartered group formed from Smurfit Kappa and WestRock, grew June revenue 1.1% to $8.03bn while operating income fell 44% to $309m, its margin down to 3.85% from 6.95% a year earlier. Paper markets "are as strong as I have seen in my lifetime within this industry," chief executive Tony Smurfit said on the 29 July call, with the company sold out of nearly every grade. It is the cheapest of the three on capital-structure-neutral measures — 8.6x trailing EV/EBITDA, 1.34x book, a 4.4% free-cash-flow yield, about 12.2x 2027 consensus earnings of $3.50. The two dated items in its sell-off window cut the other way: a $420m agreement on 24 September for CMPC's Chilean containerboard and corrugated assets, tonnage added in South America rather than into the North American balance, and Citi trimming its target to $54 from $57 on 2 October while keeping a Buy.
What the business earns and what it does not
Twelve months do not describe one story: International Paper is down 31.5%, Packaging Corp up 6.0%, Smurfit Westrock up 1.6%. Nor does the economy explain the week — ISM manufacturing printed 54.5 in September with new orders at 55.3, a ninth straight expansion month, while box shipments fell, because boxes are paid for in units of goods shipped, not dollars of factory output. Absent discoverable company news, the likelier reading is a sector-wide de-rating ahead of the October prints.
Only one of the three declines is earned by the numbers. Packaging Corp's step down is the one four quarters of falling operating income support, against a multiple priced for a near-30% earnings jump in 2027. International Paper's and Smurfit Westrock's share declines are explained by their margins, not by anything that happened to tons, price or fiber cost in late September — both of which moved favorably. And the increases stick only because supply was withdrawn: the industry operating rate reached nearly 95% in the second quarter after roughly 3.5m to 4m tons of permanent closures since 2023, and buyers are resisting — the Association of Independent Corrugated Converters publicly opposed this round, noting producers announce large numbers and secure smaller ones.
Packaging Corp has already told investors what the September quarter is worth: $2.91 a share excluding special items, a sharp step up from what June delivered. If a confirmed price increase and a cooling fiber bill cannot produce that, the question stops being why these shares broke in five sessions and becomes what the published index is worth to the companies that set it.