

Nexans' Order Book Stalled at €7.7bn While NKT Holds €13bn and Prysmian €17bn
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Europe's three listed high-voltage cable makers all raised their 2026 guidance within three weeks this summer, and all three now trade between 17% and 20% below their 2026 highs. The operating evidence behind that uniform markdown is not uniform at all.
NKT's Transmission margin reached a record 20.2% and Prysmian booked a record €730m of adjusted EBITDA in its best quarter; Nexans' group margin did not expand and its half-year net income fell 40.8%. The market does discriminate — NKT is the most expensive of the three at 20.4x trailing EV/EBITDA, Nexans the cheapest at 12.4x — and only Nexans has a live collection problem, €1.2bn of backlog on a Cyprus link whose payments wait on a regulator. What no business explains is why the whole grid shelf sold off while Hitachi's orders nearly doubled.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
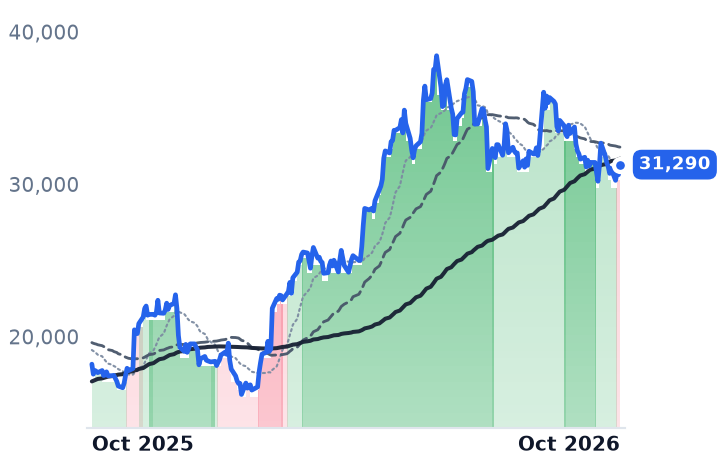
NKT.CO | NKT A/S | Electrical Equipment & Parts | ⚠️ Emerging Bear | −4.5% | +32.7% |
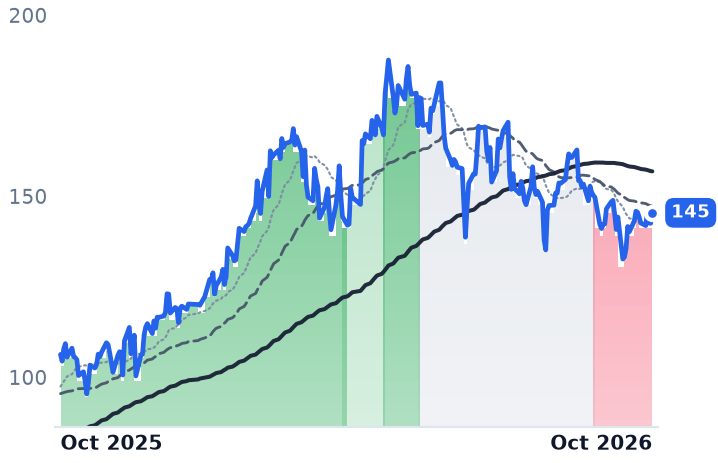
PRY.MI | Prysmian S.p.A | Electrical Equipment & Parts | 🟢 Cont. Bull | +6.2% | +47.8% |
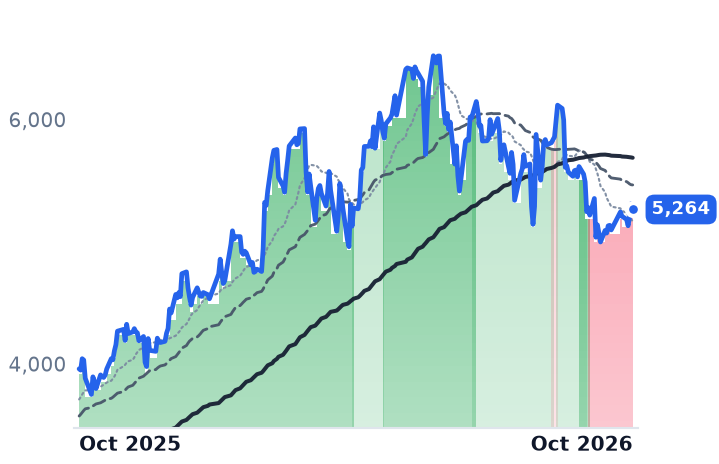
NEX.PA | Nexans | Electrical Equipment & Parts | ⚠️ Emerging Bear | −0.1% | +2.7% |
| Compared against · context, not the story | |||||
6501.T | Hitachi | Conglomerates | 🟢 Cont. Bull | +3.2% | +24.7% |
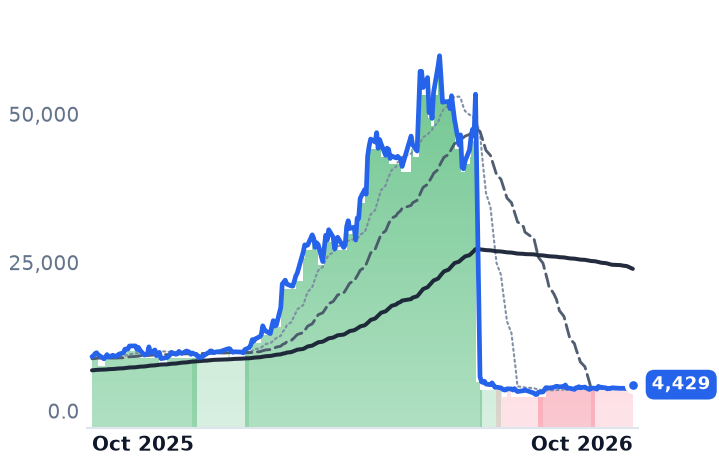
POWERINDIA.NS | Hitachi Energy India | Electrical Equipment & Parts | 🟢 Cont. Bull | −1.1% | +71.9% |
ENR.DE | Siemens Energy | Industrial - Machinery | ⚠️ Emerging Bear | −0.8% | +36.8% |
6503.T | Mitsubishi Electric | Electrical Equipment & Parts | ⚠️ Emerging Bear | +0.9% | +32.9% |
5801.T | Furukawa Electric | Electrical Equipment & Parts | 🔴 Cont. Bear | +15.2% | −51.6% |
5802.T | Sumitomo Electric Industries | Auto - Parts | ⚠️ Emerging Bear | +16.0% | +129.5% |
5333.T | NGK Insulators | Electrical Equipment & Parts | 🟢 Cont. Bull | +8.3% | +126.3% |
267260.KS | HD Hyundai Electric | Electrical Equipment & Parts | ⚠️ Emerging Bear | −5.0% | +3.2% |
298040.KS | Hyosung Heavy Industries | Electrical Equipment & Parts | ⚠️ Emerging Bear | +1.9% | +86.7% |
010120.KS | LS ELECTRIC | Electrical Equipment & Parts | 🟢 Cont. Bull | +7.3% | +248.2% |
006260.KS | LS | Electrical Equipment & Parts | ⚠️ Emerging Bear | −0.3% | +75.3% |
HPS-A.TO | Hammond Power Solutions | Electrical Equipment & Parts | ⚠️ Emerging Bear | +22.8% | +122.0% |
LAND.SW | Landis+Gyr | Electrical Equipment & Parts | 🔴 Cont. Bear | +9.6% | −18.8% |
TES.MI | Tesmec S.p.A | Industrial - Machinery | 🟢 Cont. Bull | +39.3% | +363.1% |
HEXA-B.ST | Hexagon AB (publ) | Hardware, Equipment & Parts | 🌱 Emerging Bull | +5.0% | −12.6% |
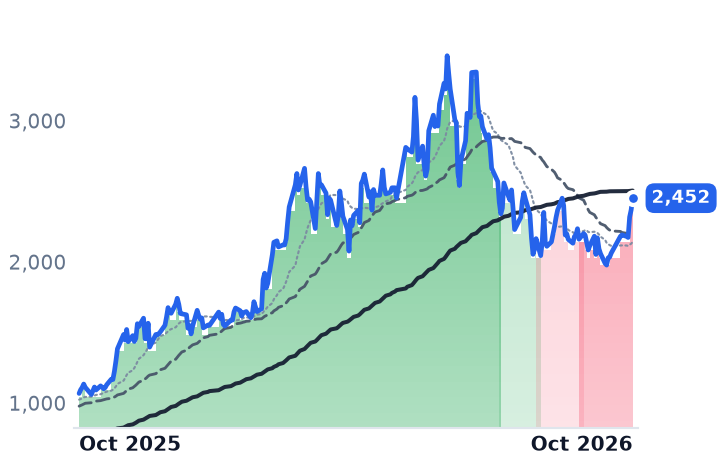
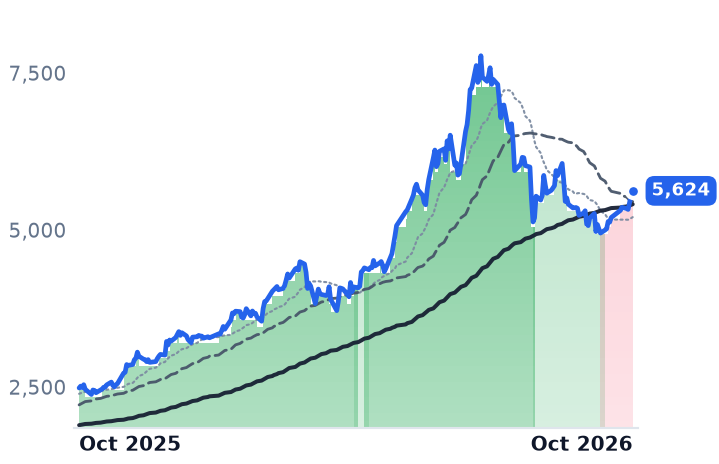
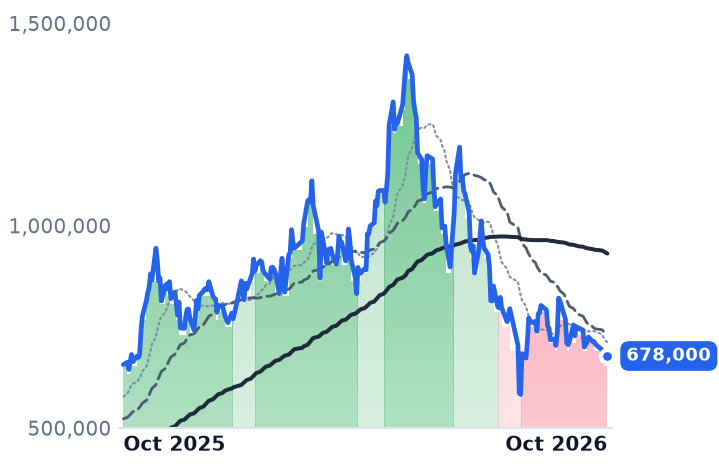
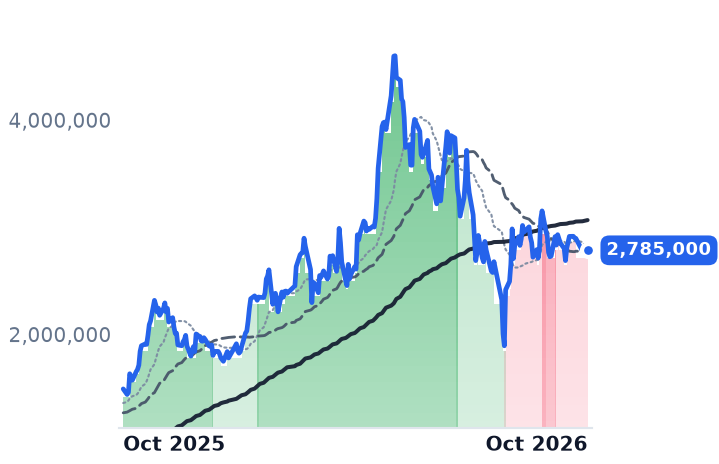
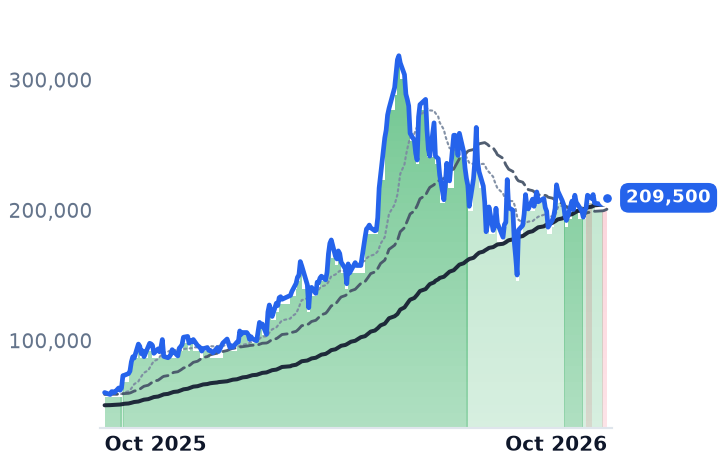
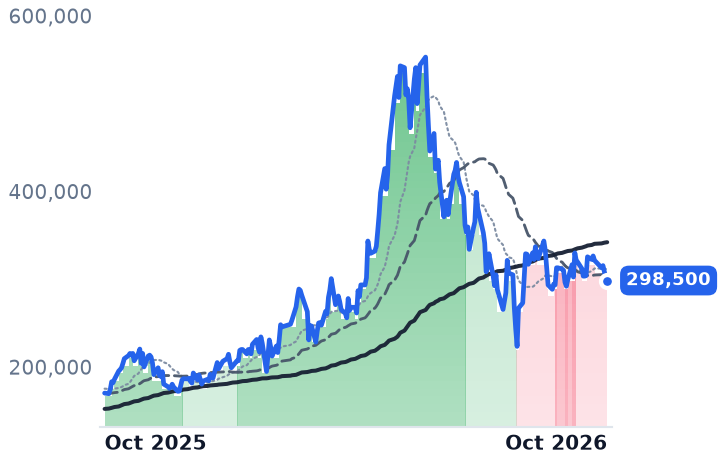
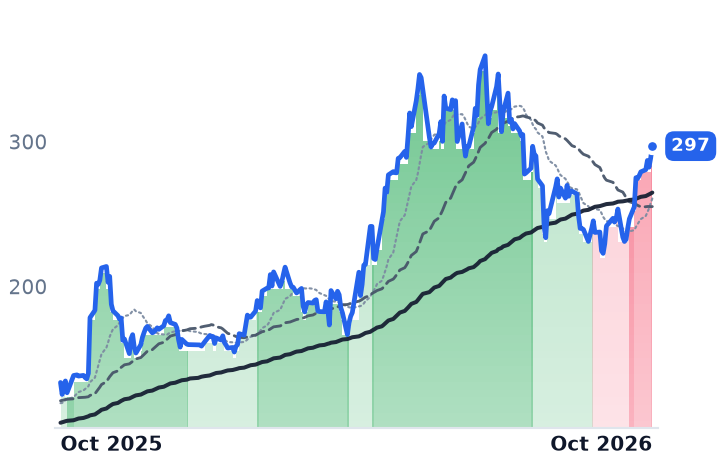
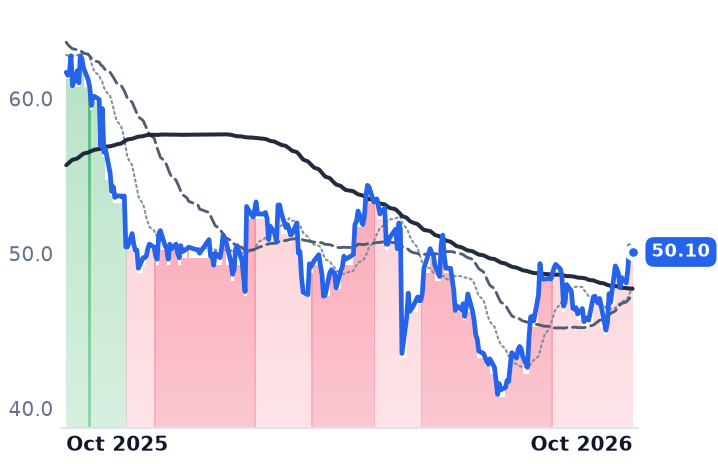
12-month price & trend
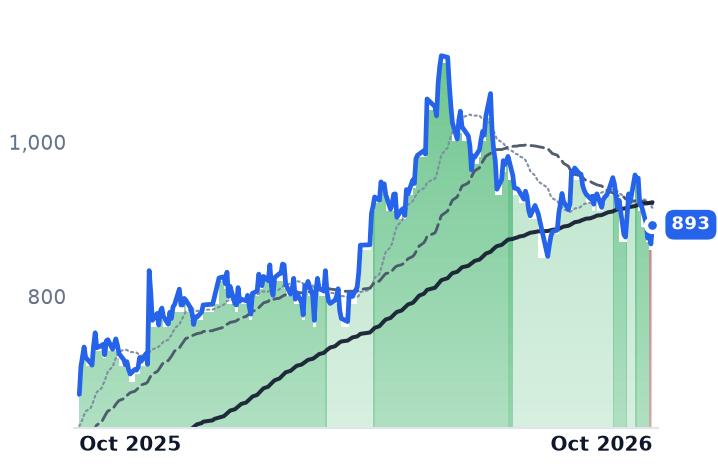
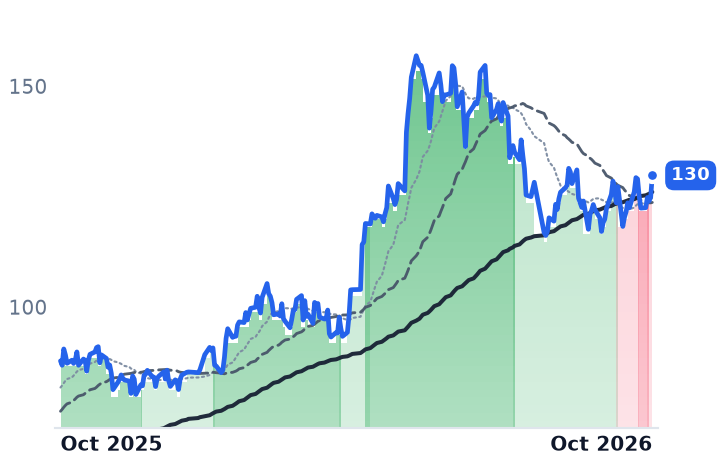
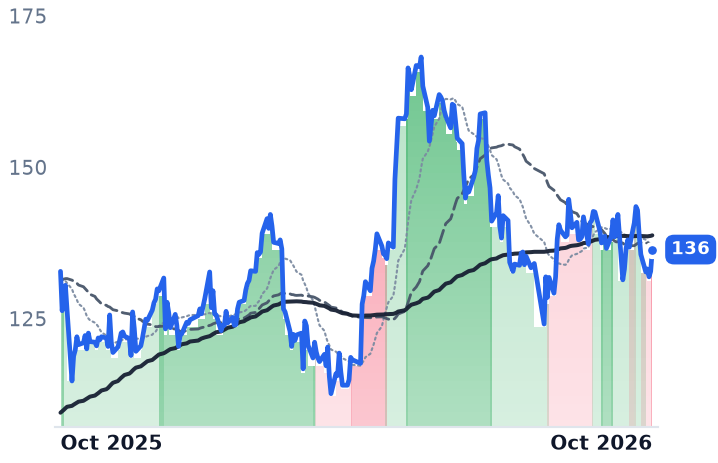
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NKT.CO | $47.7B | 23.9x | — | 1.8x | — | 8.8x | — | 20.4x | -10.0% |
PRY.MI | $37.9B | 27.3x | 27.0x | 1.8x | 1.7x | 6.7x | 6.3x | 15.3x | 2.6% |
NEX.PA | $6.0B | 71.4x | 18.4x | 0.8x | 0.7x | 7.8x | 7.5x | 12.4x | 4.7% |
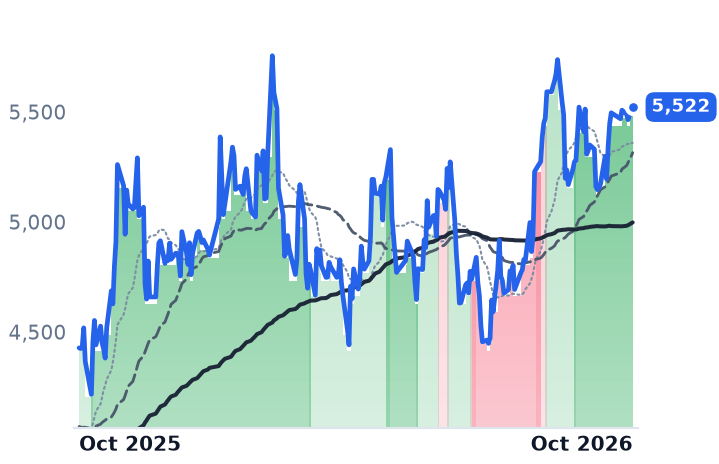
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
6501.T | $24.8T | 31.2x | 25.6x | 2.2x | 2.1x | 7.4x | 6.9x | 13.6x | 5.4% |
POWERINDIA.NS | $1.4T | 121.2x | 89.0x | 15.2x | 11.9x | 48.7x | 38.2x | 84.4x | 0.6% |
ENR.DE | $124.4B | 46.2x | 23.1x | 3.0x | 2.5x | 14.3x | 11.9x | 20.6x | 6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
6503.T | $10.8T | 25.4x | 19.8x | 1.8x | 1.7x | 5.2x | 4.9x | 13.7x | 5.0% |
5801.T | $3.1T | 34.8x | 27.7x | 2.3x | 2.0x | 12.6x | 11.3x | 19.7x | 0.0% |
5802.T | $7.6T | 19.1x | 21.1x | 1.4x | 1.4x | 7.0x | 6.8x | 10.5x | 0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
5333.T | $1.6T | 22.6x | 17.3x | 2.3x | 2.2x | 7.6x | 7.2x | 10.6x | 0.0% |
267260.KS | $24.4T | 28.7x | 25.5x | 5.6x | 5.2x | 16.2x | 15.0x | 19.7x | 2.7% |
298040.KS | $25.9T | 44.4x | 33.0x | 4.0x | 3.6x | 18.6x | 16.6x | 28.9x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
010120.KS | $31.2T | 80.2x | 58.5x | 5.5x | 4.8x | 25.5x | 22.4x | 47.3x | -0.6% |
006260.KS | $8.3T | 19.1x | 13.7x | 0.2x | 0.2x | 2.4x | 2.1x | 14.8x | -30.8% |
HPS-A.TO | $3.5B | 57.4x | 29.2x | 3.3x | 2.5x | 11.0x | 8.4x | 29.6x | -0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LAND.SW | $1.4B | n/m | 16.4x | 1.5x | 1.2x | 7.1x | 5.9x | 13.2x | 3.4% |
TES.MI | $340.0M | 161.4x | 27.6x | 1.1x | 1.1x | 7.8x | 7.8x | 11.3x | 8.5% |
HEXA-B.ST | $260.4B | 43.6x | — | 4.8x | — | 7.6x | — | 7.1x | 5.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NKT.CO | Revenue | +3.6% | +17.6% | +13.6% |
| EPS | +3.3% | +32.1% | +44.1% | |
PRY.MI | Revenue | +15.2% | +13.5% | +8.0% |
| EPS | +17.8% | +30.6% | +18.9% | |
NEX.PA | Revenue | +13.8% | +7.9% | +8.9% |
| EPS | −10.7% | +27.8% | +18.8% | |
6501.T | Revenue | +8.2% | +12.6% | +9.1% |
| EPS | +28.2% | +21.0% | +19.8% | |
POWERINDIA.NS | Revenue | +19.2% | +49.5% | +39.4% |
| EPS | +166.9% | +59.3% | +47.6% | |
ENR.DE | Revenue | +13.2% | +14.5% | +12.8% |
| EPS | +174.2% | +40.6% | +31.0% | |
6503.T | Revenue | +6.3% | +11.6% | +3.3% |
| EPS | +14.3% | +51.2% | +12.0% | |
5801.T | Revenue | +8.8% | +18.9% | +12.7% |
| EPS | +84.6% | +112.8% | +30.1% | |
5802.T | Revenue | +7.7% | +10.9% | +6.0% |
| EPS | +91.2% | +14.6% | +19.2% | |
5333.T | Revenue | +6.4% | +11.5% | +5.8% |
| EPS | +12.5% | +57.5% | +5.4% | |
267260.KS | Revenue | +16.1% | +19.2% | +14.9% |
| EPS | +36.7% | +27.7% | +21.8% | |
298040.KS | Revenue | +22.2% | +19.4% | +16.7% |
| EPS | +62.4% | +43.5% | +32.6% | |
010120.KS | Revenue | +33.7% | +22.7% | +17.3% |
| EPS | +92.7% | +43.5% | +30.4% | |
006260.KS | Revenue | +31.8% | +6.6% | +5.3% |
| EPS | +142.1% | +19.6% | +16.0% | |
HPS-A.TO | Revenue | +59.1% | +22.5% | +11.6% |
| EPS | +57.7% | +19.9% | +22.9% | |
LAND.SW | Revenue | −36.4% | +0.4% | +9.4% |
| EPS | −42.1% | +41.9% | +25.5% | |
TES.MI | Revenue | +15.3% | +8.8% | +7.8% |
| EPS | +272.7% | +34.1% | +40.0% | |
HEXA-B.ST | Revenue | −24.3% | +13.8% | +5.5% |
| EPS | −7.5% | +9.9% | +6.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Within three weeks this summer, each of Europe's three listed high-voltage cable specialists told investors the year would be better than the spring plan. Nexans raised its earnings range on 29 July, Prysmian the next day, NKT on 13 August. Since then all three have traded between 17% and 20% below their 2026 highs.
What links them is a product almost nothing else sells: the submarine and onshore cable for the direct-current links that move power between countries and bring offshore wind ashore. The order books are long — NKT's transmission book runs to €13.0bn, Prysmian's to €17bn — and that length is what is being questioned. A high-voltage contract is priced years before the copper is bought, built against factory capacity that may not exist yet, laid by a vessel that can be late, and collected from a public counterparty against progress. Signed is not collected.
The one with a real problem
Nexans, the €6.0bn French group reshaping itself around electrification, is the member whose numbers match its share price. Its adjusted backlog was €7.7bn at 30 June, unchanged from December, with visibility only to 2028, and group adjusted EBITDA margin was flat at 11.9% of standard sales against 12.0% a year earlier — the only one of the three that did not expand. First-half net income fell 40.8% to €103m as disposals and impairments from the exit of non-electrification businesses ran through. "Our first-half performance reflects the continued disciplined execution of our strategy in an environment where the structural drivers of electrification remain stronger than ever," chief executive Julien Hueber said on 29 July.
Inside that flat book sits €1.2bn tied to the Great Sea Interconnector, the Cyprus–Crete–Greece link Nexans was to supply and install. The company has withdrawn tenders on the project, and Greece's transmission operator IPTO has said it would stop paying absent remaining decrees from the Cyprus Energy Regulatory Authority. Consensus now models Nexans' 2026 EBITDA down 16.1% to €716m — the only down year in the group. It is also the cheapest, at 12.4x trailing EV/EBITDA and 18.4x forward earnings.
The two without one
NKT, the Danish pure-play that makes both cable and the ships that lay it, did the opposite. Its Transmission operational EBITDA margin hit a record 20.2% and the group margin rose to 15.7% from 14.5%, and on 13 August it lifted guidance to revenue of €2.65–2.75bn at standard metal prices and operational EBITDA of €400–430m. Backlog did slip, to €13.0bn from a record €13.5bn three months earlier — because work was delivered. "The Champlain Hudson Power Express project in North America reached commercial operation, a historic milestone for NKT," chief executive Claes Westerlind said the same day.
That delivery also shows why the revenue line misleads. NKT's reported second-quarter revenue was €946.9m, flat year on year; at standard metal prices it was €657m, down 9%. The €290m difference — roughly a third of the reported top line — is copper and aluminium passed to customers at no margin, and London Metal Exchange copper set a record $14,455 a tonne in August.
Prysmian, at €37.9bn of market value far the largest, carries the same arithmetic plus acquisitions: second-quarter revenue rose 24.1% to €6.06bn against 9.4% organic growth, the gap being metal and the Encore Wire and Channell deals, which add short-cycle American building wire and connectivity with no grid content. Transmission grew 7.3% organically in the half on a €17bn backlog, and chief executive Massimo Battaini called the quarter, with its record €730m of adjusted EBITDA, "the best quarter ever of Prysmian" on 30 July.
Both ends of the cable
If interconnection demand were cooling, the suppliers at either end would know first. Hitachi Energy builds the converter stations and transformers; inside its Tokyo parent, group orders rose 87% to ¥1,906.3bn in the June quarter and energy revenue grew 37% to ¥911.9bn with adjusted EBITA margin at 14.2%. In June it won €770m of converter-station work on the 600MW Italy–Tunisia Elmed link. Hitachi sits 5.1% below its 2026 peak, the one name here that has not been marked down, on 13.6x trailing EV/EBITDA.
What the shares did
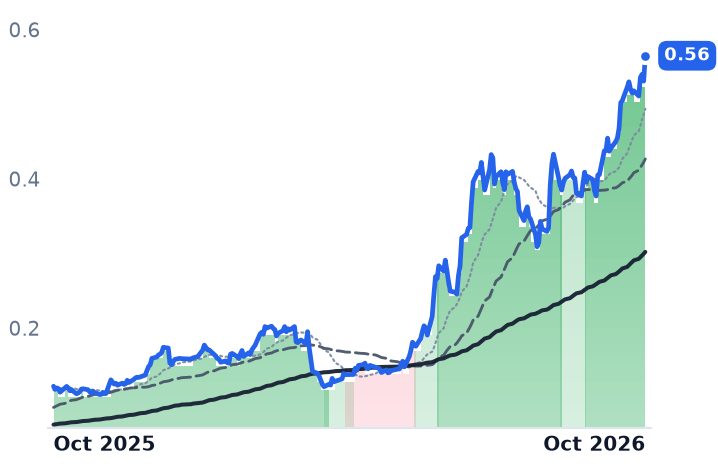
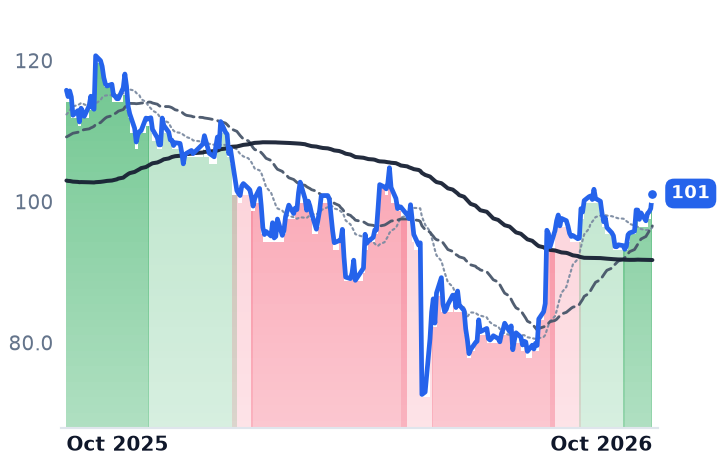
The drawdowns are broad, and the cable makers are the mild end: Prysmian 17.3% below its 2026 high, Nexans 18.9%, NKT 19.7%, against Siemens Energy at 22.5%, Sumitomo Electric at 29.8% and Korea's HD Hyundai Electric at 52.3%. Twelve-month returns remain large — NKT 39.1%, Prysmian 47.5% — which is what the unwind of a crowded position off an extended base looks like. Kepler Cheuvreux's upgrade of NKT to Hold, with a DKK 895 target, cited the roughly 23% fall since May rather than any change to estimates.
The verdict
The markdown is uniform; the businesses are not. NKT and Prysmian have handed buyers nothing to mark down — records on margin, books near highs, guidance raised, demand corroborated by the equipment at both ends — so what their shares have lost is the premium of early 2026, and NKT still carries the group's highest valuation at 20.4x trailing EV/EBITDA and about 29x consensus 2026 earnings, converting euro estimates at roughly 7.46 kroner. Nexans has earned its discount, and its Cyprus line is the live demonstration of what the whole group is being priced for: an order book is a claim on a regulator's signature and a ship's schedule, not cash. The usable consequence is that these three can no longer be read off one revenue line.
NKT is spending €2bn so that more of the chain belongs to it — the Karlskrona plant, the Cologne expansion and its own cable-laying vessel, the NKT Eleonora, now being outfitted in Norway. All three are due next year, which is also the first year consensus expects NKT's earnings to step up.