

Collegium Earns a Tenth of the Branded Price on the Nucynta Generics It Licensed Out
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A branded medicine can keep its prescriptions and still lose most of its revenue line. Collegium licensed authorized generic versions of its Nucynta painkillers to Hikma Pharmaceuticals USA, and chief executive Vikram Karnani told investors each immediate-release prescription that migrates nets Collegium 10% to 15% of the branded net price. The pain franchise's quarterly net revenue fell 24% to $35.2m, and group operating margin went from 30.4% a year earlier to 1.9%.
The acquired attention-deficit products are growing, and they were bought. Belbuca's agreed generic entry date is January 2027; the term loan financing the roll-up runs years past it. Supernus guided its year up and its shares fell anyway, because they now convert into Indivior stock at a fixed ratio. Pacira's price squeeze comes from hospital purchasing groups rather than the patent calendar.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
COLL | Collegium Pharmaceutical | Specialty Branded Pharma | 🔴 Cont. Bear | −6.4% | −34.9% |
SUPN | Supernus Pharmaceuticals | Specialty Branded Pharma | 🔴 Cont. Bear | −2.6% | −12.3% |
PCRX | Pacira BioSciences | Specialty Branded Pharma | 🟢 Cont. Bull | −4.3% | +5.6% |
| Compared against · context, not the story | |||||
INDV | Indivior Pharmaceuticals | Specialty Branded Pharma | 🟢 Cont. Bull | +2.2% | +57.1% |
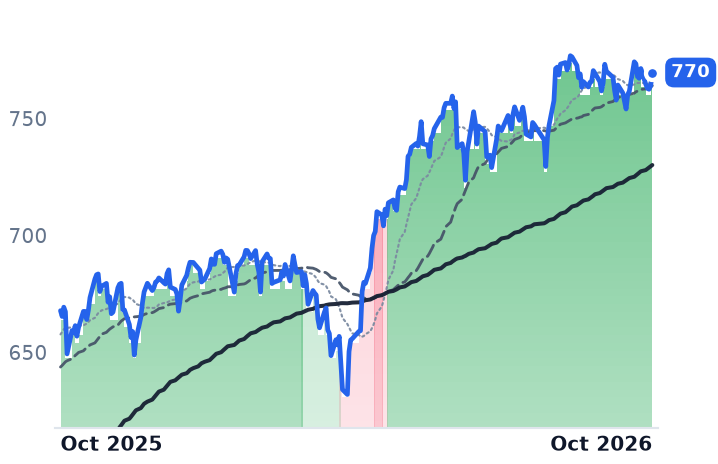
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.1% | +15.2% |
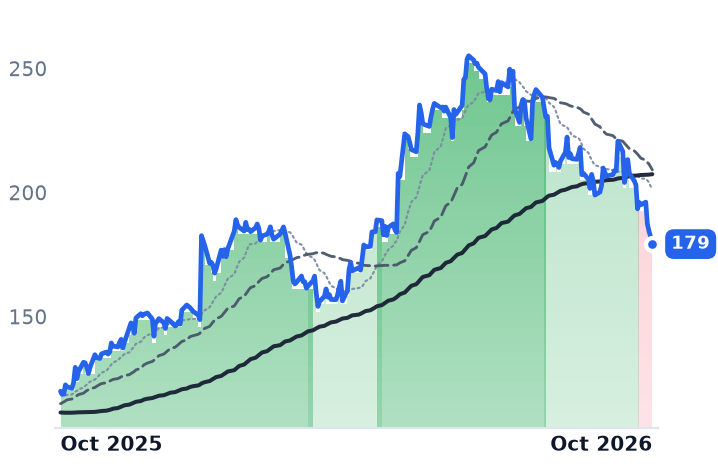
ALKS | Alkermes | Immunology & Autoimmune | 🟢 Cont. Bull | −9.4% | +34.7% |
AXSM | Axsome Therapeutics | CNS & Neurological | 🟢 Cont. Bull | −13.3% | +49.4% |
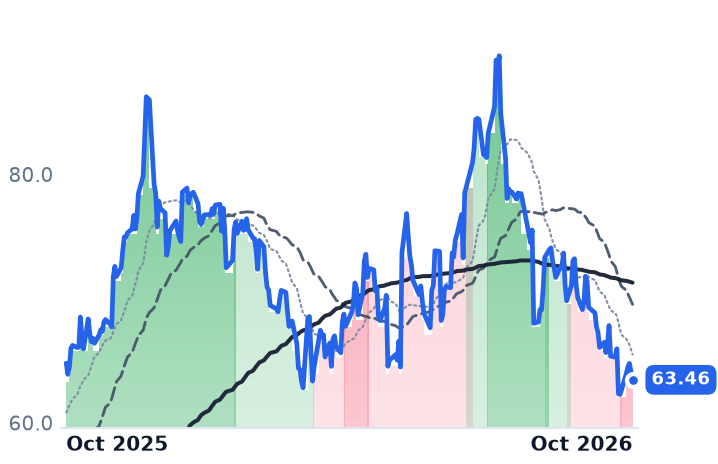
PTCT | PTC Therapeutics | Rare Genetic & Metabolic Diseases | ⚠️ Emerging Bear | −8.4% | −2.1% |
ANIP | ANI Pharmaceuticals | Generic & API Manufacturers | 🔴 Cont. Bear | +1.3% | −21.6% |
CORT | Corcept Therapeutics Incorporated | Rare Genetic & Metabolic Diseases | 🟢 Cont. Bull | +4.1% | +29.4% |
AMPH | Amphastar Pharmaceuticals | Generic & API Manufacturers | 🌱 Emerging Bull | +9.7% | −4.3% |
AMRX | Amneal Pharmaceuticals | Generic & API Manufacturers | 🟢 Cont. Bull | +16.4% | +92.4% |
TEVA | Teva Pharmaceutical Industries | Generic & API Manufacturers | 🟢 Cont. Bull | +8.7% | +98.0% |
VTRS | Viatris | Generic & API Manufacturers | 🟢 Cont. Bull | +4.3% | +77.3% |
JAZZ | Jazz Pharmaceuticals | Other | 🟢 Cont. Bull | −4.5% | +71.3% |
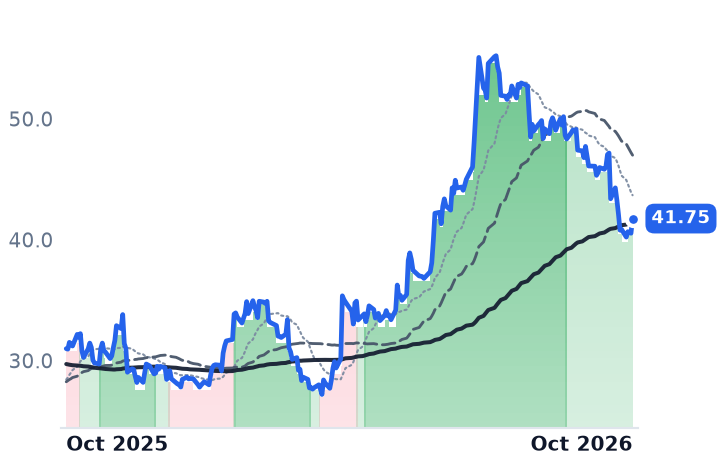
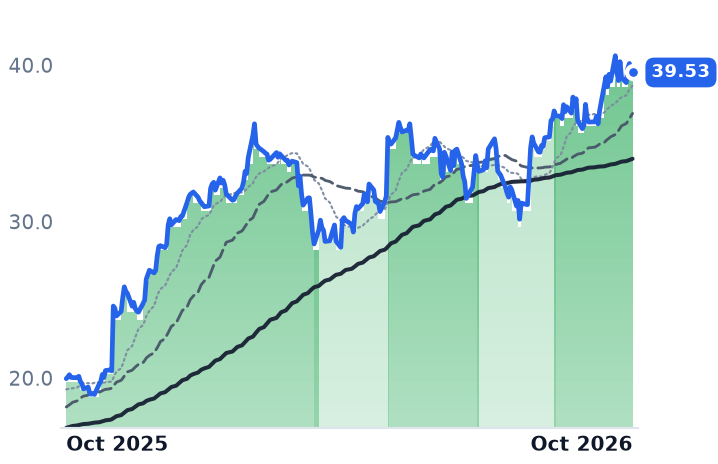
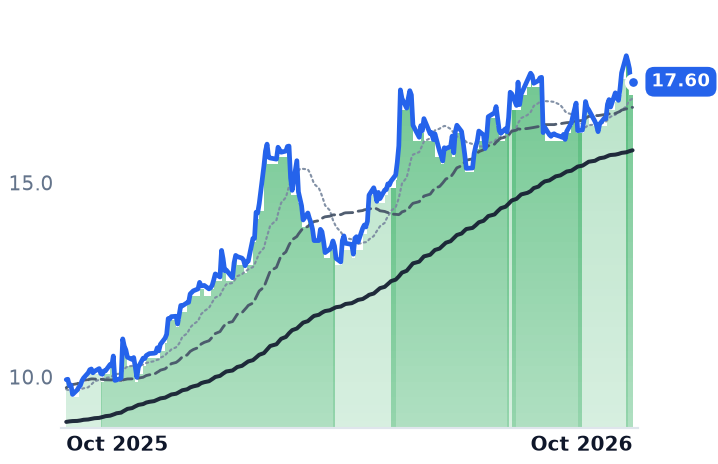
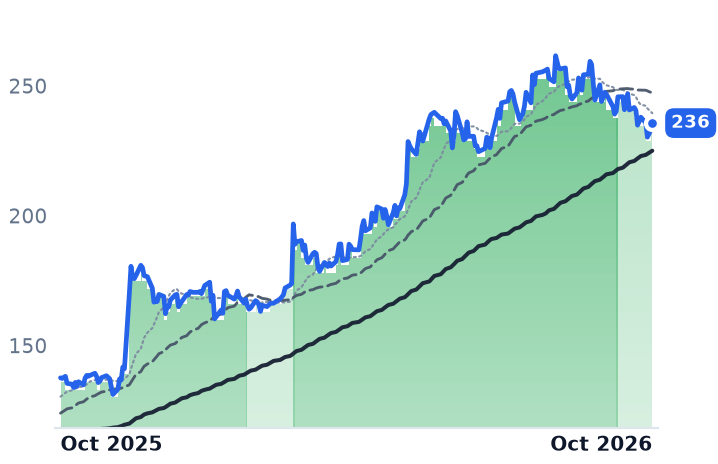
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
COLL | $714.2M | 14.4x | 3.0x | 0.9x | 0.9x | 1.5x | 1.4x | 2.5x | 46.0% |
SUPN | $2.5B | n/m | 16.5x | 3.0x | 2.8x | 3.4x | 3.2x | n/m | 0.8% |
PCRX | $991.6M | 71.6x | 8.7x | 1.3x | 1.3x | 1.7x | 1.7x | 10.4x | 18.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INDV | $4.5B | 12.6x | 8.5x | 3.3x | 3.3x | 4.0x | 4.0x | 11.0x | -2.5% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
ALKS | $6.2B | 40.8x | — | 4.0x | 3.4x | 4.6x | 4.0x | 27.1x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AXSM | $11.7B | n/m | — | 16.5x | 11.9x | 17.9x | 12.9x | n/m | -0.6% |
PTCT | $5.9B | n/m | 126.7x | 7.2x | 5.1x | 9.2x | 6.6x | n/m | -3.9% |
ANIP | $1.7B | 15.4x | 8.0x | 1.7x | 1.5x | 2.7x | 2.4x | 6.5x | 9.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CORT | $6.1B | 122.9x | 98.0x | 7.9x | 6.2x | 8.0x | 6.3x | n/m | 2.0% |
AMPH | $1.2B | 15.0x | 8.8x | 1.6x | 1.5x | 3.3x | 3.2x | 9.3x | 13.3% |
AMRX | $6.2B | 38.9x | 19.0x | 2.0x | 2.0x | 5.0x | 5.0x | 13.5x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TEVA | $45.6B | 62.9x | 19.7x | 2.7x | 2.8x | 5.1x | 5.3x | 19.2x | 5.2% |
VTRS | $20.8B | n/m | 7.1x | 1.4x | 1.4x | 4.0x | 4.0x | 12.7x | 9.0% |
JAZZ | $14.4B | 480.1x | 9.1x | 3.2x | 3.2x | 3.8x | 3.8x | 45.3x | 8.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
COLL | Revenue | +7.1% | +1.6% | −0.4% |
| EPS | −1.4% | −9.3% | −5.3% | |
SUPN | Revenue | +25.1% | +56.0% | +21.3% |
| EPS | −17.2% | +73.9% | +21.1% | |
PCRX | Revenue | +3.4% | +4.7% | +11.9% |
| EPS | −2.2% | +19.1% | +31.9% | |
INDV | Revenue | +11.8% | +5.1% | +6.4% |
| EPS | +79.4% | +9.4% | +4.8% | |
ALKS | Revenue | +23.2% | +4.2% | +9.9% |
| EPS | −114.0% | −356.5% | +117.4% | |
AXSM | Revenue | +54.8% | +62.5% | +42.5% |
| EPS | −47.8% | −394.6% | +149.2% | |
PTCT | Revenue | −37.6% | +11.2% | +18.8% |
| EPS | −94.1% | +267.1% | +5.8% | |
ANIP | Revenue | +27.1% | +11.5% | +8.4% |
| EPS | +23.2% | +12.9% | +14.2% | |
CORT | Revenue | +19.7% | +28.8% | +32.0% |
| EPS | −39.8% | +234.2% | +98.0% | |
AMPH | Revenue | +3.1% | +4.9% | +3.0% |
| EPS | −13.6% | +7.1% | +6.3% | |
AMRX | Revenue | +4.7% | +9.0% | +10.9% |
| EPS | +27.4% | +17.3% | +21.4% | |
TEVA | Revenue | −1.2% | +4.6% | +4.5% |
| EPS | −23.8% | +53.8% | +11.8% | |
VTRS | Revenue | +4.7% | +1.7% | +3.1% |
| EPS | +8.7% | +6.4% | +7.3% | |
JAZZ | Revenue | +6.2% | +7.2% | +8.8% |
| EPS | +205.3% | +2.1% | +12.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Collegium Pharmaceutical, the Stoughton, Massachusetts seller of branded pain medicines and an acquired attention-deficit portfolio, still supplies the tapentadol painkillers it markets as Nucynta, and prescribers still write them. What the company has stopped collecting is the price. The franchise produced $35.2m of net revenue in the June quarter, down 24% from a year earlier, and that figure already includes $5.1m of profit share on the authorized generic versions, with the decline attributed to lower net pricing on those generics. Chief executive Vikram Karnani put a number on it for investors: the authorized generic nets Collegium roughly 10% to 15% of branded net price for the immediate-release product and 20% to 25% for extended release.
The acquired ADHD franchise was read as the engine that replaces this. "In the second quarter, we saw strong demand across our ADHD portfolio, highlighted by record-high JORNAY PM prescriptions and prescriber adoption, alongside 41% revenue growth," Karnani said in the results release of 6 August 2026. It is growing: Jornay PM delivered $46.1m, on prescriptions up 13.1%. The same morning the company cut full-year revenue guidance from $865-895m to $825-855m and adjusted earnings before interest, taxes, depreciation and amortization to $445-470m, and the shares fell about 13.5% before the open.
The list price nobody pays
A specialty-pharma dollar is the residue of a much larger billed number. For the six months to 30 June 2025, Collegium's filings show provisions on current-period sales of $241.8m for rebates and incentives, $101.4m for trade allowances and chargebacks and $34.6m for returns — $377.8m of deductions against roughly $366m of net product revenue booked in the period. List price is approximately double what the company keeps.
That gap is where the quarter was lost. Xtampza ER's $4.5m revenue decline came from lower volume and higher gross-to-net adjustments, partly offset by a higher gross price: the sticker went up, the realization went down. Group gross margin fell to 55.2% from 62.5% two quarters earlier, operating margin to 1.9% from 30.4% a year ago, and the quarter closed with a $15.1m net loss on $199.9m of revenue. Statute is pushing the same way — the Inflation Reduction Act's Manufacturer Discount Program obliges makers to fund 10% of Part D cost in the initial phase and 20% in the catastrophic phase, a larger drag on high-priced specialty products than the program it replaced.
The calendar ends in January; the loans do not
US exclusivity for Nucynta immediate-release runs to 3 January 2027, and Belbuca's agreed generic entry date under its Teva settlement is the same month. Xtampza ER's agreed date is September 2033. Against that, $572.8m of principal was outstanding under the term loan at 31 March 2026, alongside $241.5m of 2.875% convertible notes due 2029, with the term facility maturing in November 2028 or December 2030 depending on conditions.
The replacement portfolio is purchased, not discovered. Collegium paid about $650m in cash for the Azstarys business in May 2026 — roughly $350m of balance-sheet cash plus a $300m delayed draw — and it contributed $12.9m of revenue from 12 May to 30 June. Half-year amortization of acquired intangibles ran to $118.4m against a cash cost of making the drugs of $47.4m.
Two other meters on the same dollar
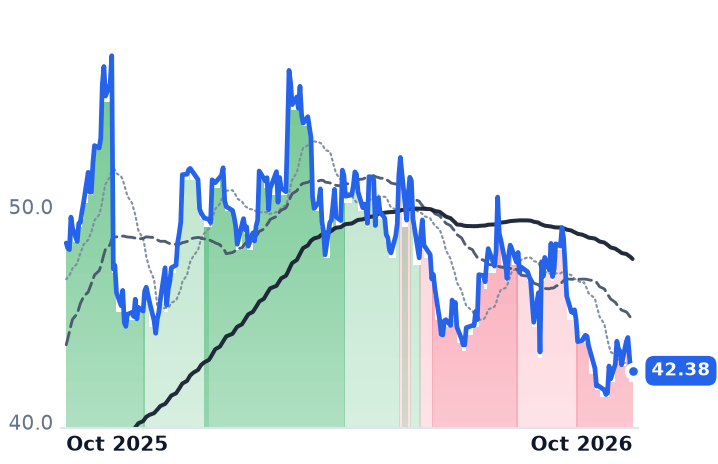
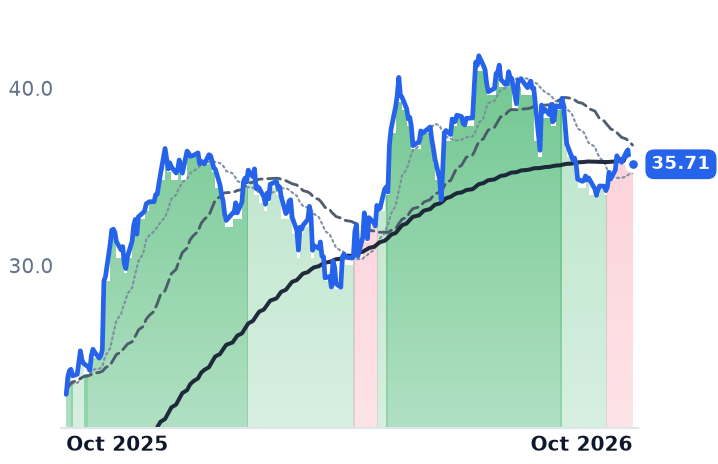
Supernus, the Rockville CNS specialist, is the control on the pricing thesis and fails it: revenue rose 32% to $219.1m, Qelbree net sales 15% to $89.2m on prescriptions up 17%, and guidance went up to $860-890m. Its shares fell 11.8% over three months because each one now converts into 1.5401 Indivior shares; the quote is Indivior's.
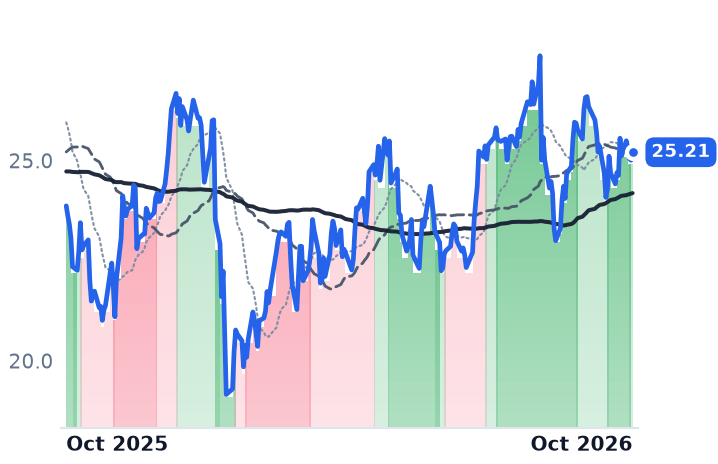
Pacira, which sells the non-opioid injectable Exparel, confirms the mechanism from the hospital side. Vials rose 4% and net sales only 3%, to $147.8m, the gap owed to vial mix and a third group-purchasing-organisation discount contract; gross margin slipped 4 points to 77.0%. Its patent fight is settled — Fresenius Kabi is licensed no earlier than a confidential 2030 date — so what moves Pacira's dollar is whether payers reimburse the drug outside the surgical bundle, and that improved in the quarter. It trades at 8.7x forward earnings and 10.4x trailing EV/EBITDA, with an 18.1% trailing free-cash-flow yield.
What the fall has already paid for
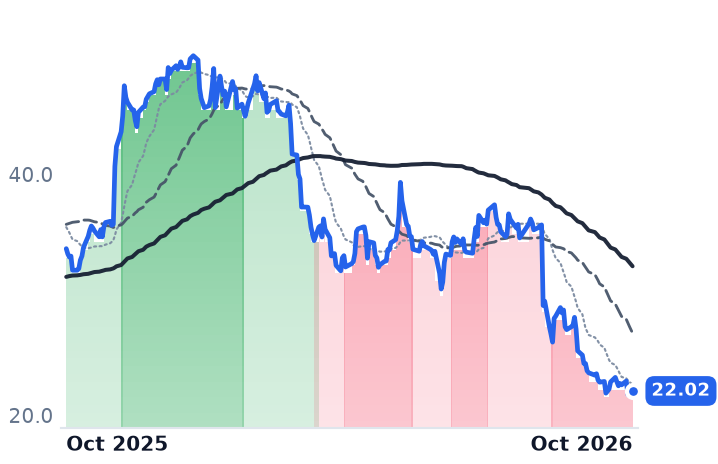
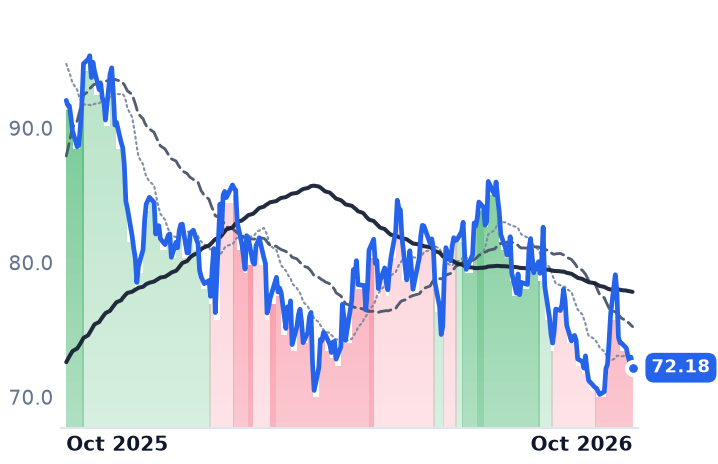
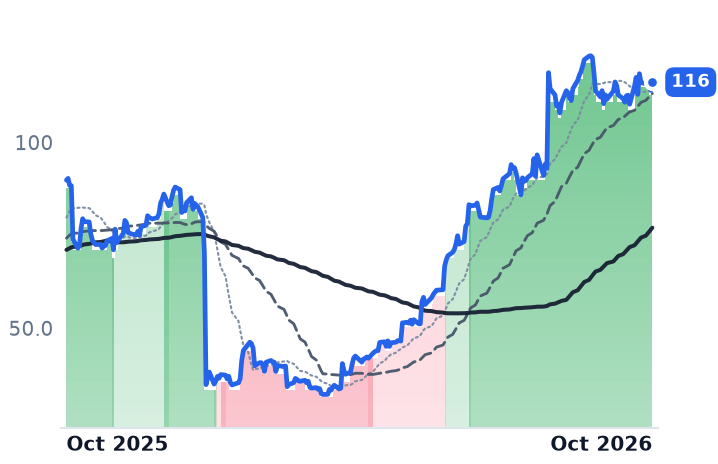
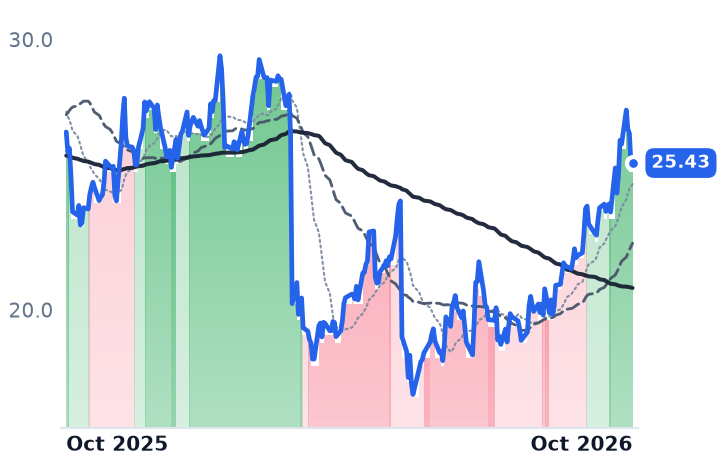
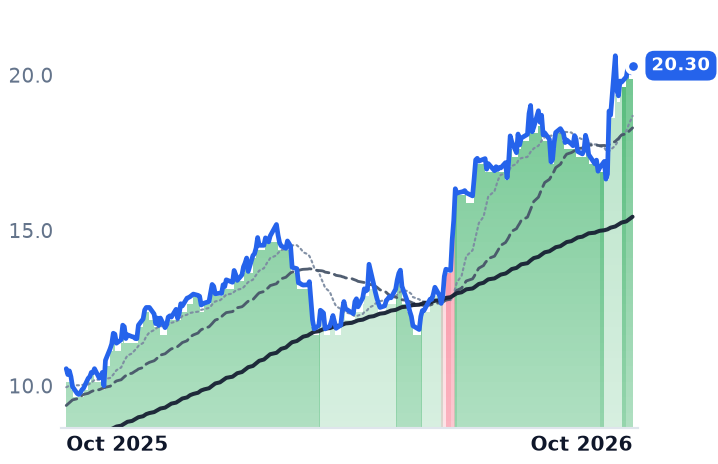
Collegium closed at $22.02 on 2 October, down 40.5% in three months and 35.8% in a year, in a declining trend since mid-August. Comparable branded small-caps went in both directions over the same stretch — Alkermes fell 23.5% and Axsome 26.6%, while Corcept rose 28.8% and Amphastar 29.5%, with the S&P 500 up 3.3% — so this is a verdict on Collegium.
The business explains the direction fully: four quarters of decelerating revenue, a 7-point gross-margin compression, a cut guide and a franchise whose price has been reset by its own licensee. What the business does not obviously explain is the level. At 2.46x trailing EV/EBITDA and a 46% trailing free-cash-flow yield, against 14.4x trailing earnings versus roughly 20-26x a year ago, the shares are priced for the cash to stop, while consensus revenue holds near $850m through 2028. One of those is wrong, and the test is whether Jornay PM and Azstarys hold their guided $190-200m and $65-75m while the pain franchise finishes going.
There is one more cost arriving at this market-cap band: the 100% tariff on certain patented pharmaceutical products took effect at the end of September and exempts the large manufacturers that signed most-favored-nation pricing agreements. Collegium's ADHD portfolio has until January to become the company.