

Valmont Raised Guidance as Utility Sales Grew 34% and Irrigation Fell 16%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Four of the five listed suppliers of America's utility poles have lost ground over three months, and nothing in their order books explains it.
Valmont raised full-year guidance in July on Infrastructure sales up 14.8%, then de-rated to 20.7x forward earnings from the 25.3x its June peak implied on the same consensus. The only deteriorating line is center-pivot irrigation, about a fifth of guided revenue, whose guidance never moved.
The cross-checks say the grid is physically shipping: galvanizing volumes at AZZ, domestic pole volumes at Koppers and wood pole volumes at Stella-Jones all grew in the same quarter. Stella-Jones is the one de-rating its business earns, with adjusted margin down to 16.0%. Arcosa's placid chart is a $150 cash bid from CRH.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
VMI | Valmont Industries | Diversified Manufacturing | ⚠️ Emerging Bear | +0.8% | +21.7% |
AZZ | AZZ | Metal Coatings & Finishing | 🟢 Cont. Bull | +1.4% | +29.3% |
SJ.TO | Stella-Jones | Paper, Lumber & Forest Products | 🔴 Cont. Bear | −4.1% | −17.9% |
KOP | Koppers | Industrial Chemicals & Additives | 🟢 Cont. Bull | −1.7% | +71.4% |
ACA | Arcosa | Construction Materials | 🟢 Cont. Bull | +0.7% | +58.9% |
| Compared against · context, not the story | |||||
CRH | CRH | Integrated Cement & Materials | 🔴 Cont. Bear | −11.0% | −31.5% |
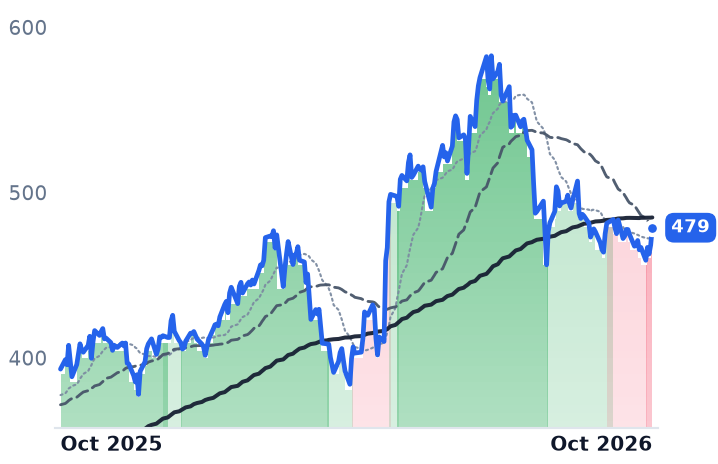
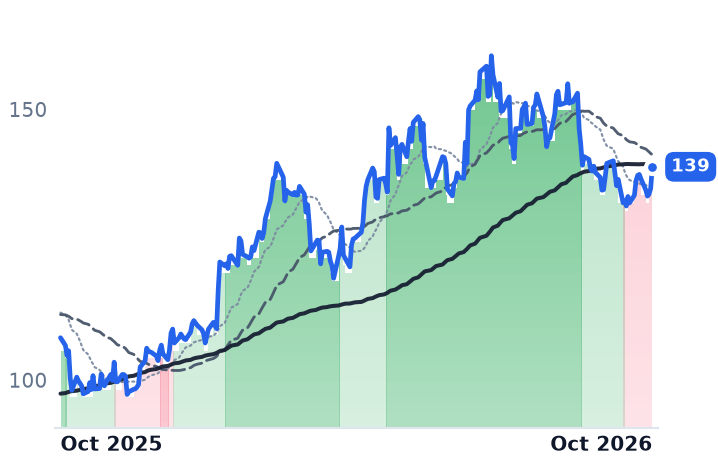
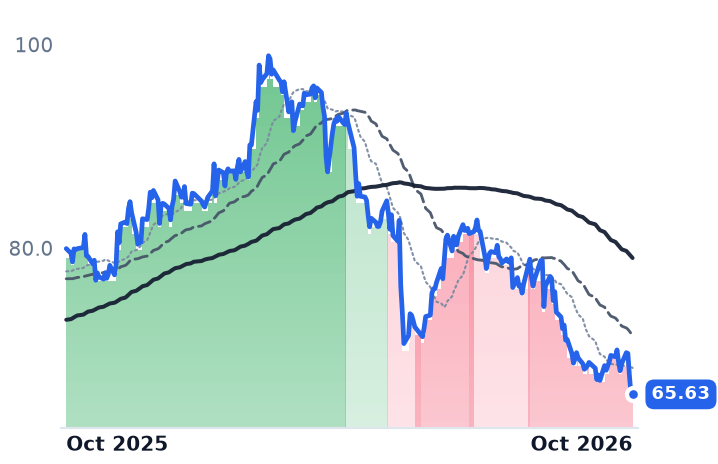
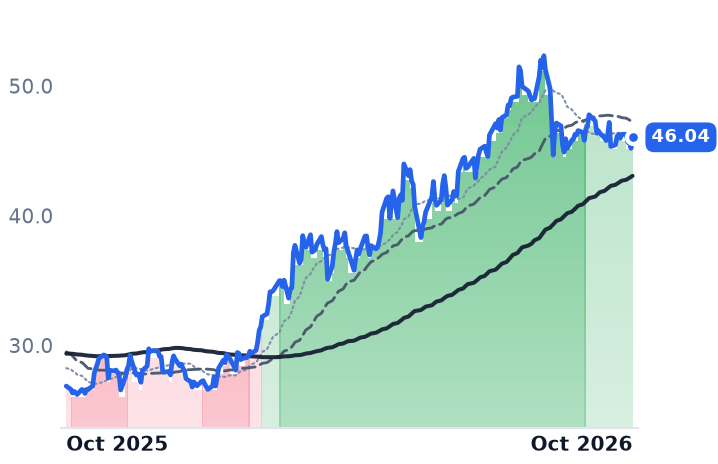
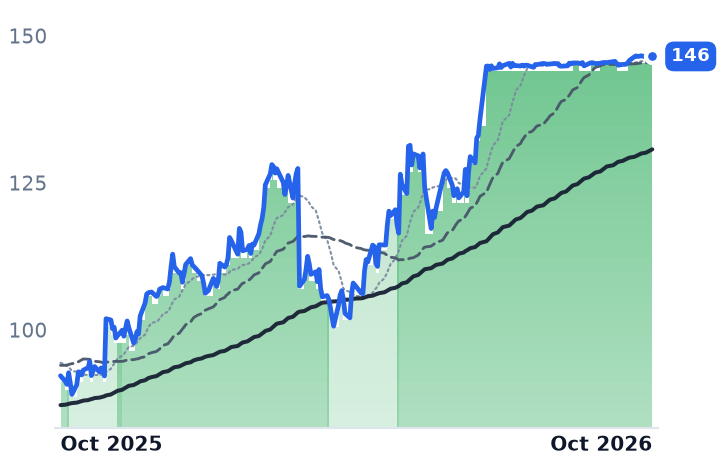
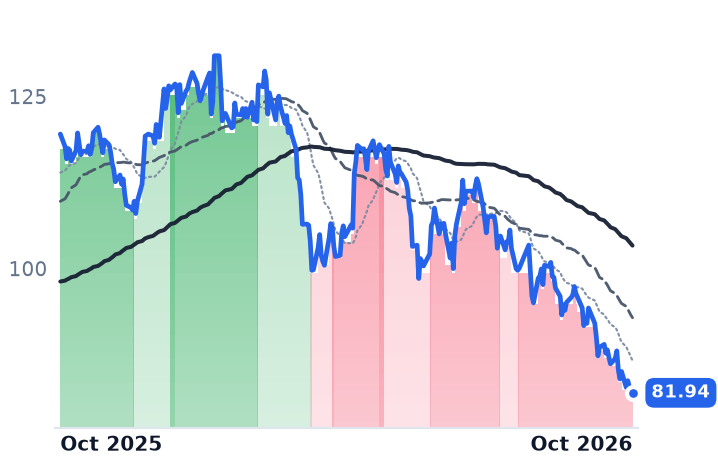
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VMI | $9.2B | 18.9x | 20.7x | 2.2x | 2.1x | 7.2x | 7.0x | 14.8x | 3.5% |
AZZ | $4.2B | 21.1x | 19.7x | 2.5x | 2.3x | 10.4x | 9.6x | 12.5x | 4.0% |
SJ.TO | $3.6B | 13.9x | 13.1x | 1.0x | 1.0x | 5.5x | 5.4x | 8.5x | 13.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KOP | $885.4M | n/m | 11.4x | 0.5x | 0.5x | 2.2x | 2.2x | 60.7x | 15.7% |
ACA | $7.2B | 14.7x | 34.2x | 2.6x | 2.8x | 11.4x | 12.0x | 13.5x | 1.9% |
CRH | $69.0B | 13.7x | 17.3x | 1.2x | 1.7x | 3.5x | 4.9x | 7.9x | 4.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VMI | Revenue | +6.4% | +6.6% | +7.7% |
| EPS | +20.6% | +12.5% | +14.2% | |
AZZ | Revenue | +3.3% | +10.5% | +4.6% |
| EPS | +15.3% | +16.6% | +10.4% | |
SJ.TO | Revenue | +2.2% | +3.3% | +7.5% |
| EPS | −17.6% | +22.3% | +18.7% | |
KOP | Revenue | +2.7% | +3.5% | +0.9% |
| EPS | +1.3% | +20.9% | +2.7% | |
ACA | Revenue | −9.8% | +9.3% | +2.7% |
| EPS | +1.5% | +13.7% | +3.5% | |
CRH | Revenue | +5.9% | +5.1% | +6.8% |
| EPS | +6.8% | +12.7% | +12.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A raise that traded like a cut
Valmont Industries, the Omaha fabricator of steel, concrete and composite poles for electric utilities that also builds Valley-brand center-pivot irrigation machines for farmers, lifted its full-year outlook on July 21, and the shares fell in the two sessions that followed. Infrastructure sales rose 14.8% to $878.9m in the June quarter, with North America utility up 34%. Guidance went to $4.3–4.45bn of sales and $22.25–23.50 a share. Infrastructure backlog stood at $1,583.6m on June 27, above the $1,548.3m carried at the December year-end.
"The demand environment continues to be robust and strong across all parts of the utility business, transmission, distribution, and substations, evident by our backlog," president and chief executive Avner Applbaum told investors on the July 21 call, where management described capacity rather than orders as the limit on how fast the utility business can grow.
The money at issue is a budget expansion. S&P Global Market Intelligence's regulatory research arm puts 2026 US energy-utility capital spending near $259bn, roughly 29% above 2025, and about $1.3 trillion across 2026–2030, aimed at new artificial-intelligence data-center load as well as aging plant. The suppliers collecting it are paid by incompatible meters: Valmont books fabrication against utility awards placed quarters before the steel is bought; AZZ charges a toll per pound to galvanize steel it never owns; Stella-Jones and Koppers treat wood poles and sell the chemistry that preserves them. In the June quarter every meter ran faster, and the shares split anyway.
What the farm half costs
Valmont's Agriculture sales fell 16% to $243.7m on low grain prices and trade-policy uncertainty, and that segment's guidance was left untouched at $0.9–0.95bn, about a fifth of guided revenue. The stock went from $583.55 on June 25 to $478.74 on October 2, down 14.4% over three months and still up 21.3% over twelve. At the June peak, consensus 2026 earnings of $23.10 implied 25.3x; the shares now trade at 20.7x forward against 18.9x trailing, roughly four turns of de-rating delivered into a guidance raise. What the price no longer pays for is the bar inside that consensus: an operating cash margin near 17.5% of sales, against 12.7% last year.
The toll per pound
AZZ, the Fort Worth galvanizer, gives the cleanest physical read, because it is paid by the pound whoever owns the steel. Metal Coatings sales rose 12.3% to $210.3m on volume in the quarter to May 31, while segment adjusted EBITDA margin fell 260 basis points to 30.3%, which management attributed to a prior-year land sale in the comparison and a heavier mix of large projects. AZZ's own release noted that one of its largest galvanizing customers had just reported 35% growth in utility-related structures backlog. Chief executive Tom Ferguson raised fiscal 2027 guidance to $1.8–1.85bn of sales and $6.75–7.15 a share. The stock is down 7.1% over three months and trades at 19.7x forward against 21.1x trailing.
Zinc is the forward risk no reported quarter contains. London Metal Exchange three-month zinc hit a four-year high of $3,949.50 a tonne on August 26, after AZZ's quarter closed, on the biggest squeeze in decades as exchange inventories ran near dry. A supply shortage raises the cost of the coating without putting another structure through the kettle.
Wood volumes grew; one multiple did not survive it
Stella-Jones, the Quebec pressure-treater, sold $510m of utility products against $476m a year earlier, with wood pole volumes up 2% and pricing down 1%. Its damage sits elsewhere: residential lumber fell $12m, railway ties fell $5m on reduced Class I railroad capital spending, and adjusted EBITDA margin compressed to 16.0% from 18.3%. The shares are down 30.6% over six months, the only member of the group lower over twelve, at 13.1x forward earnings, 8.5x trailing EV/EBITDA and a 13.8% trailing free-cash-flow yield. Analysts cut 2026 earnings 17.6%; the price fell nearly twice that.
Koppers, the Pittsburgh treater and maker of the copper-based preservatives pole plants consume, grew domestic utility pole volumes 16% and Performance Chemicals sales 11.5% to $168.2m on 11% Americas volume, with prices lower in Europe and crossties weaker. Its $147.5m quarterly loss carried $215.8m of impairment and closure costs; chief executive Leroy Ball called shutting distillation at the Stickney, Illinois plant "exactly the type of difficult but disciplined decision required to optimize our asset network". It trades at 11.4x forward earnings against that cost-out plan.
Arcosa belongs in the evidence and outside the price comparison. Its record utility-structures backlog of $648.1m, up 49% since the start of the year, with Engineered Structures margin up 180 basis points to 20.4%, corroborates everything above. Its chart has been flat by contract: CRH agreed on June 22 to buy the company for $150 a share in cash in a transaction valued at $8.5bn, shareholders approved it on September 4, and the stock has since traded in a 1.5% range near the bid. A deal spread wearing the costume of an uptrend.
Everything shipped more; two multiples fell anyway
Nothing in the group shipped less. Steel and concrete structures, galvanized pounds and treated poles all grew in the same quarter, which disposes of the idea that either de-rating is a grid-volume event, and of the notion that wood is being displaced today. The displacement is real on a longer clock: utilities hardening networks against wildfire are specifying non-combustible poles in high-risk zones, a slow transfer of socket from wood to steel that no single quarter will show.
Stella-Jones's fall is earned by its own margin, and the cheap cash flow underneath it is the open question. Valmont's order book earns none of its fall; the likelier reading is an expectations reset after a June investor presentation, with irrigation supplying the only line going backwards, on guidance that has not moved either way. For AZZ the squeeze is ahead of it in the metal, not behind it in the volumes.
That makes the next two prints unusually legible. The backlog number tests the utility claim and the irrigation number tests the farm excuse, and whatever August's zinc price does to the galvanizing toll will show up in neither.