

Air Products Wrote Off $2.9bn, Then Booked $2.4bn of Electronics Gas Contracts
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Air Products has spent two years taking charges on clean-energy plants it will never build, and the market is still pricing that record. The book that replaced it is semiconductor work: 80% of a $3.0bn industrial-gas backlog, on on-site contracts that typically run fifteen years and phase in from 2028, with full-year guidance raised twice, to $13.39-$13.49.
The shares fell a tenth over thirty days anyway and go into the November report at 19.2x fiscal-2027 consensus earnings, against 26.8x forward for Linde. Linde still earns its premium on margin, though the results gap narrowed over the year while the price gap widened. Air Liquide, with a record backlog of its own, has the worst twelve-month return of the three.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
APD | Air Products and Chemicals | Industrial Gases | 🌱 Emerging Bull | −8.8% | +3.6% |
LIN | Linde | Industrial Gases | ⚠️ Emerging Bear | −0.6% | +3.5% |
| Compared against · context, not the story | |||||
AI.PA | L'Air Liquide | Chemicals - Specialty | 🔴 Cont. Bear | −1.3% | −0.9% |
AMAT | Applied Materials | Semiconduct Equipment | 🟢 Cont. Bull | +23.9% | +149.1% |
LRCX | Lam Research | Semiconduct Equipment | 🟢 Cont. Bull | +18.7% | +139.0% |
ASML | ASML | Semiconduct Equipment | 🟢 Cont. Bull | +13.4% | +81.9% |
ONTO | Onto Innovation | Semiconduct Equipment | 🟢 Cont. Bull | +29.8% | +128.1% |
AMKR | Amkor Technology | Packaging & Assembly | ⚠️ Emerging Bear | +19.3% | +91.4% |
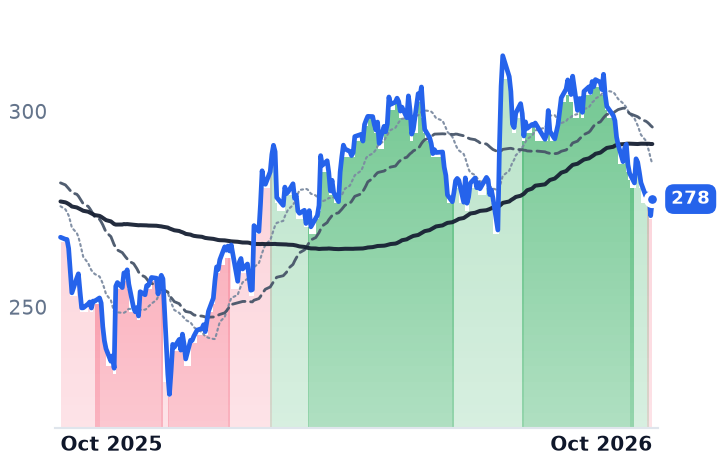
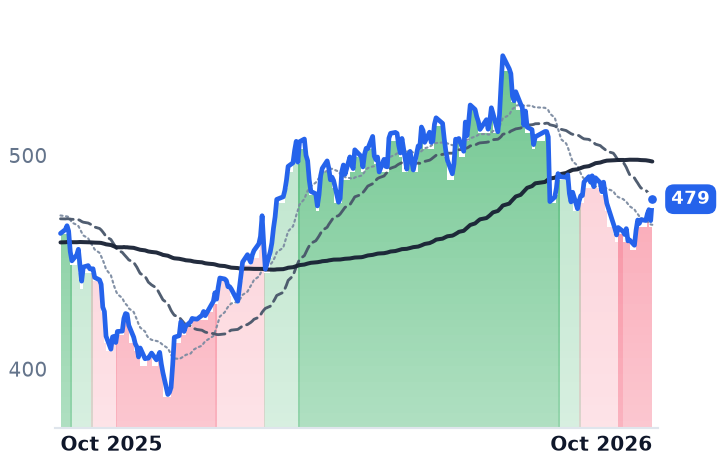
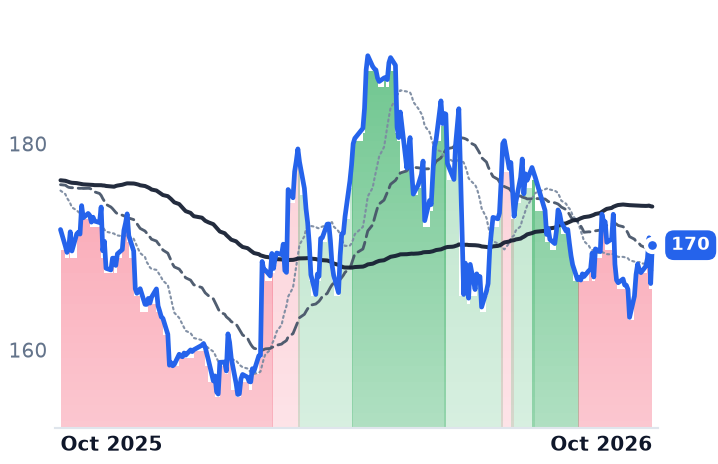
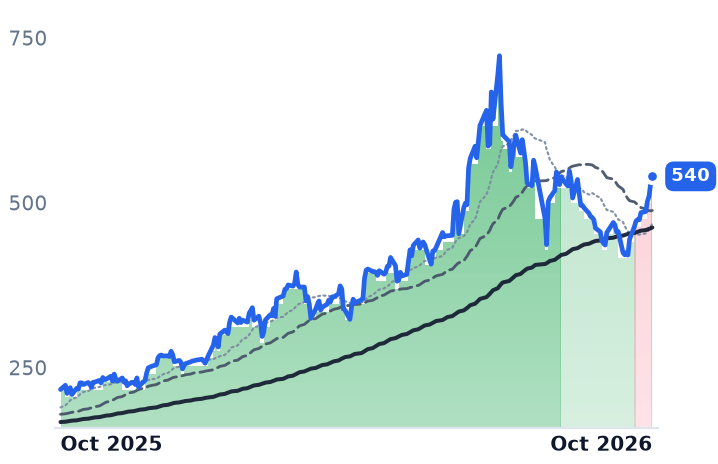
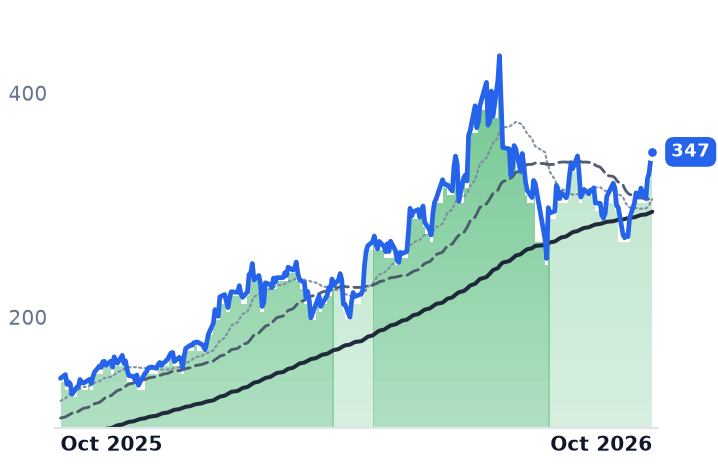
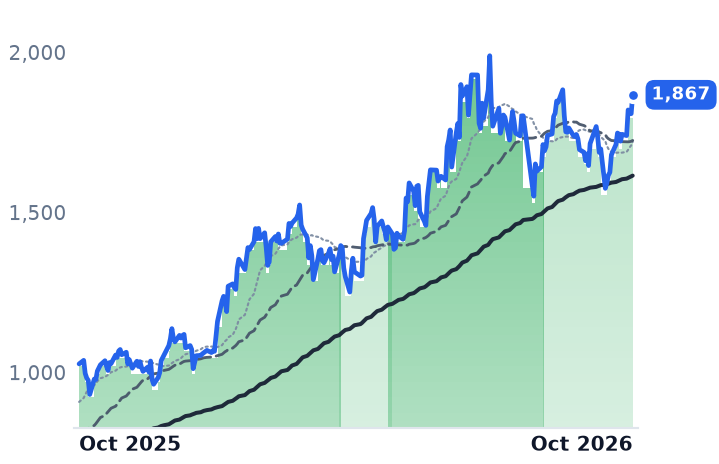
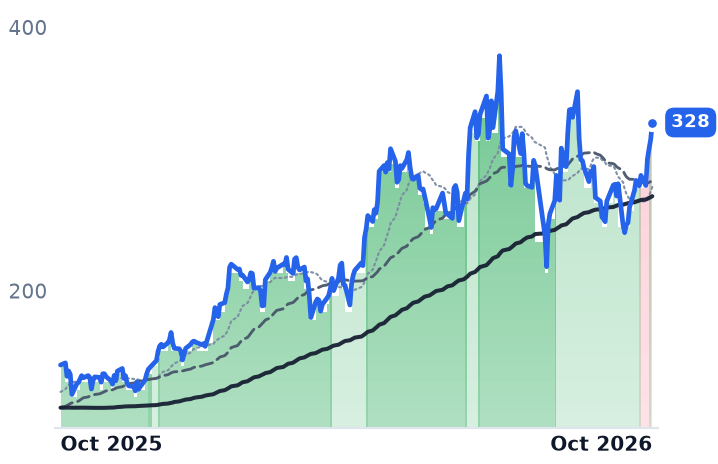
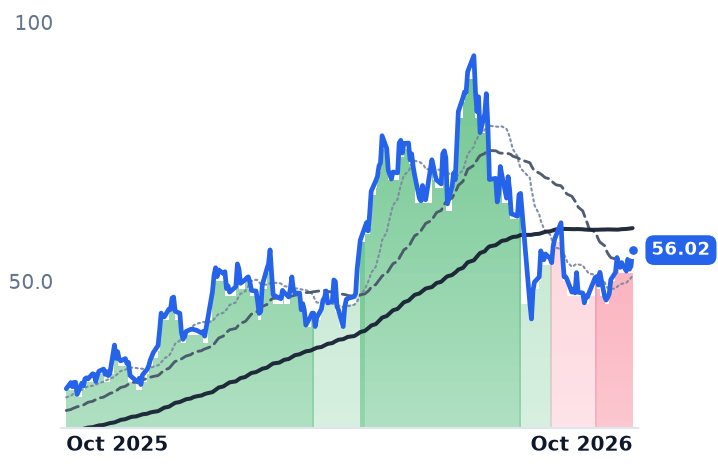
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APD | $61.8B | n/m | 19.2x | 4.9x | 4.6x | 15.3x | 14.3x | 60.9x | 3.3% |
LIN | $221.8B | 30.8x | 26.8x | 6.3x | 6.1x | 16.7x | 16.3x | 18.2x | 2.2% |
AI.PA | $108.2B | 29.1x | 26.5x | 4.0x | 3.8x | 11.0x | 10.6x | 14.8x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMAT | $425.0B | 45.9x | 43.6x | 13.8x | 12.7x | 27.9x | 25.7x | 37.3x | 1.5% |
LRCX | $430.0B | 59.4x | 36.7x | 18.5x | 12.4x | 36.7x | 24.6x | 49.2x | 1.1% |
ASML | $725.8B | 56.9x | 49.4x | 17.1x | 16.8x | 32.4x | 31.8x | 43.4x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ONTO | $13.4B | 100.3x | 33.2x | 11.9x | 9.3x | 23.7x | 18.5x | 51.4x | 1.9% |
AMKR | $13.4B | 24.2x | 21.1x | 1.8x | 1.8x | 11.6x | 11.3x | 10.4x | 3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APD | Revenue | +6.0% | +5.8% | +6.2% |
| EPS | +12.2% | +7.4% | +8.1% | |
LIN | Revenue | +7.2% | +4.9% | +5.8% |
| EPS | +8.9% | +9.6% | +10.2% | |
AI.PA | Revenue | +4.5% | +4.6% | +4.8% |
| EPS | +10.3% | +11.2% | +8.8% | |
AMAT | Revenue | +18.3% | +28.9% | +20.8% |
| EPS | +31.2% | +38.7% | +28.8% | |
LRCX | Revenue | +27.0% | +49.0% | +18.6% |
| EPS | +41.9% | +64.7% | +25.5% | |
ASML | Revenue | +33.7% | +27.3% | +20.6% |
| EPS | +54.0% | +37.1% | +28.6% | |
ONTO | Revenue | +2.2% | +43.0% | +30.3% |
| EPS | −5.1% | +63.1% | +44.2% | |
AMKR | Revenue | +14.7% | +12.8% | +10.1% |
| EPS | +103.7% | +8.9% | +19.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Air Products has stopped building the hydrogen business it spent a decade announcing. In the June quarter the Allentown, Pennsylvania supplier of oxygen, nitrogen, argon, hydrogen, helium and specialty electronics gases booked an operating loss of $2.10bn, carrying a pre-tax charge of up to $2.9bn to exit the Louisiana Clean Energy Complex, cancel a hydrogen facility at Casa Grande, Arizona and wind up smaller clean-energy initiatives. It was the second such quarter in six: operating income was -$2.33bn in March 2025, and fiscal 2025 closed with an operating loss of $877m on revenue of $12.0bn.
What replaced those projects is what the share price has yet to acknowledge. The traditional industrial-gas backlog stands at $3.0bn, and $2.4bn of it, 80%, is electronics work: air-separation and hydrogen plants built inside a customer's fence on supply contracts that typically run fifteen years on take-or-pay terms, clearing a double-digit unlevered return and ramping over two to three years. Those plants phase in from 2028. The contract is signed years before the first dollar of revenue, which is why the backlog rather than the revenue line is the leading indicator of a fab buildout.
The sockets have names
More than $1.5bn of electronics wins were booked in the six months to July. On 16 September the company committed roughly $250m to build, own and operate dedicated gas infrastructure for a leading semiconductor manufacturer in Arizona: hydrogen generation units, carbon-dioxide purification and bulk helium. It was the second such award, taking committed investment in the segment past $900m. Earlier commitments include on-site plants for Samsung's new Pyeongtaek fab, phasing in from 2028, and supply to TSMC's 2nm line in Arizona.
"The electronics is really where the growth is, and I think we're very fortunate that we kept that capability in the company," chief executive Eduardo Menezes told investors on the July 30 call.
Underneath the charge
The operating business improved while the balance sheet absorbed the exits. Adjusted third-quarter earnings rose 12% to $3.47 a share, revenue grew 4.6% year on year after 8.8% in the March quarter, and fiscal-2026 guidance was raised to $13.39-$13.49 from the $13.00-$13.25 given a quarter earlier. "Our operating margin of 25.6% was also up compared to the same period last year, largely from volume and price improvement, partially offset by higher costs," Menezes said on the same call.
Capital spending was cut to roughly $3.5bn from about $4bn, partly on project timing and lower maintenance, partly because Louisiana and Casa Grande no longer need funding. Adjusted net debt sits at 2.2x adjusted earnings before interest, tax, depreciation and amortization, excluding debt tied to the NEOM joint venture in Saudi Arabia. The dividend went to $1.81 a quarter in January, a 44th consecutive annual increase, a 2.6% yield against a trailing free-cash-flow yield of 3.3%. Coverage is intact and tight; management put buybacks no earlier than late fiscal 2027.
Helium shows the lag in miniature
Missile strikes on Qatar's Ras Laffan complex on 18-19 March knocked out about 17% of the country's liquefied-natural-gas capacity, and because helium is co-produced with LNG, roughly a third of world supply went with it. Spot prices breached $1,000 per thousand cubic feet against long-term contracts at $500-$550. Air Products sells its helium on those contracts, so it still booked helium as a drag of about 2% on earnings in each of the last two quarters, the older, lower resets rolling through. JPMorgan upgraded the shares to Overweight on 20 March on the view that the shock becomes a tailwind as contracts reprice.
Linde's premium, Air Liquide's record
Linde, the larger rival at about $222bn of market value, raised its own sale-of-gas backlog by $1bn to a record $8.1bn, with electronics volumes up 18% and underlying growth split roughly half volume, half price. Chief executive Sanjiv Lamba said on the July 31 call the backlog would "finish the year with an 8 handle". Its gross margin still slipped about 0.9 points, dragged by a US home-oxygen business running a headwind of $130m or more this year and now under strategic review. Linde trades at 26.8x forward earnings, roughly the 28 times it has habitually commanded.
Air Liquide, the Paris operator with the same contract structure, reported a record €6bn backlog with electronics at 40% of it. It has the worst twelve-month return of the three.
Where the discount stops being defensible
Air Products fell 10.3% over thirty days and 11.7% over three months, and is up 2.6% over twelve months, a year in which Applied Materials rose 141% and Lam Research 136%. September was a grind: fifteen down sessions out of twenty-three, no gap beyond about 2%, and a 1.5% fall on the day the Arizona award was announced. The three-month leg was not gas-specific, since Applied Materials fell about a tenth over the same window.
A company that wrote off shareholder capital on plants it will never build has earned a discount. The size of this one is harder to defend. The gross-margin gap to Linde narrowed over the year, from about 5.7 points to 4.5, while the earnings discount widened to roughly a fifth: 20.6x fiscal-2026 consensus and 19.2x fiscal 2027, against a five-year median near 28x for the shares themselves. Reported trailing multiples carry no information while the charge sits inside the past year's earnings. No negative company development was discoverable in the thirty-day window, and the only news in it was the Arizona win and a Moderate Buy consensus with a $336.53 average target, so the likelier reading is compression into an information vacuum rather than a business event.
All three majors signed record or near-record electronics backlogs in the same reporting season, and all three shares went nowhere. The contracts that decide revenue in 2029 are already signed; the number due on 5 November decides how much capital Air Products spends getting there.