

A 22.5% Steel Price Rise Widened WESCO's Margin and Shrank Atkore's
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The same supplier price increase that is squeezing the company which makes electrical conduit is widening the margin of the company that resells it. WESCO International, which distributes wire, conduit, transformers and utility hardware it does not manufacture, reported gross margin of 21.8% in the June quarter, a fourth consecutive quarter of widening, with operating income up 18.6% on sales up 13.0% and a record backlog.
Atkore, which buys steel and resin and sells conduit by the foot, grew sales 8.1% and still saw its adjusted profit margin fall, because input costs outran its selling prices. Where you sit in the chain decided the sign. TE Connectivity is on the pass-through side too, with record orders of $5.7bn, and its shares have gone nowhere in twelve months.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
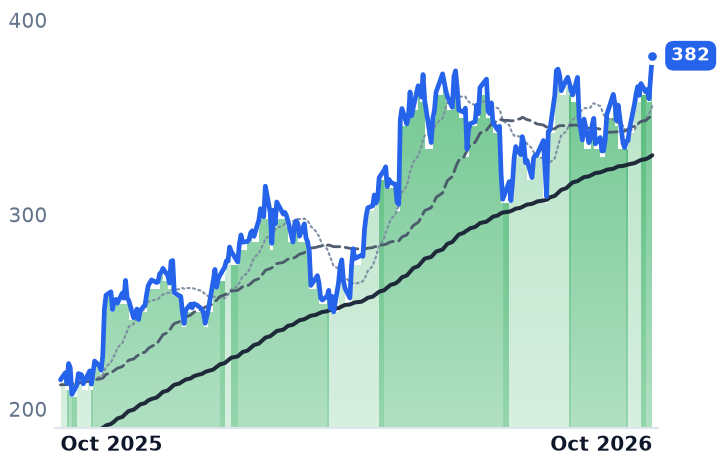
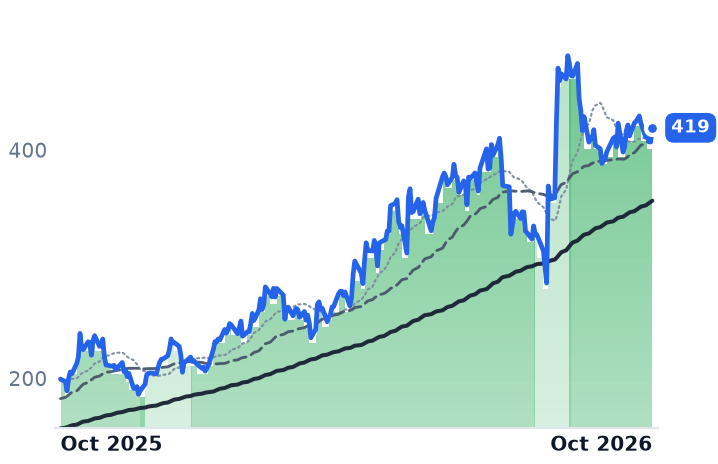
WCC | WESCO International | Electrical & HVAC Distribution | 🟢 Cont. Bull | +12.8% | +77.5% |
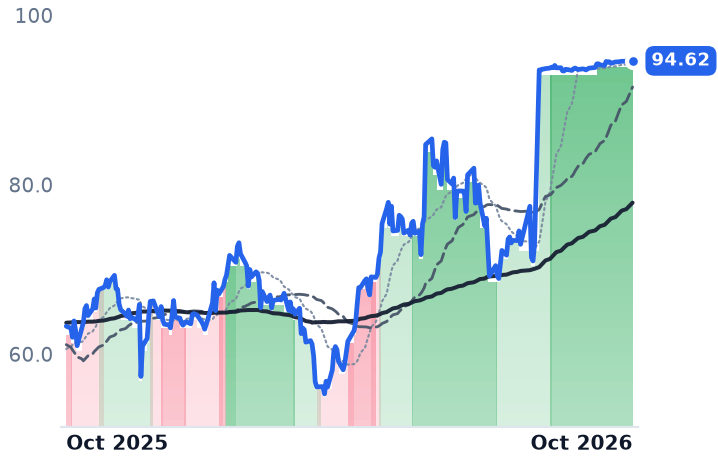
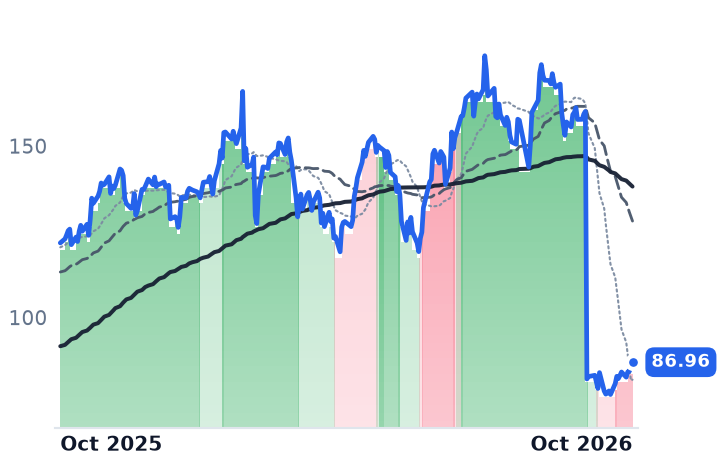
ATKR | Atkore | Electrical Infrastructure Products | 🟢 Cont. Bull | +1.0% | +49.5% |
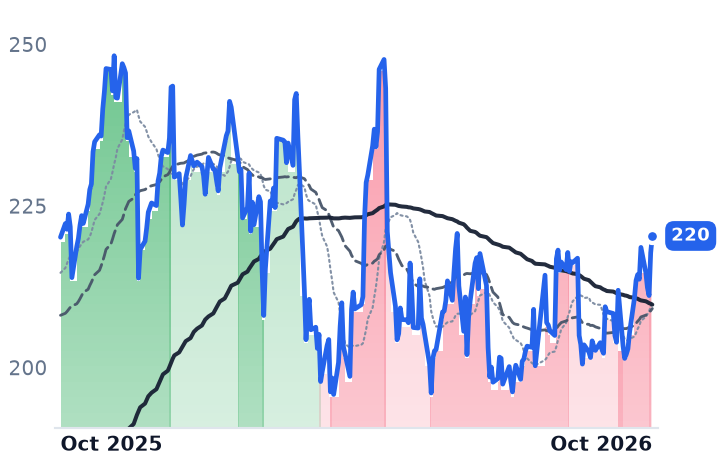
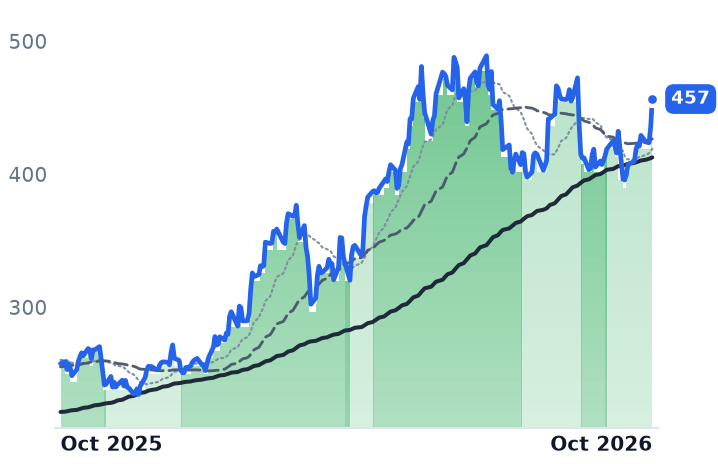
TEL | TE Connectivity | Connectors & Interconnect Systems | ⚠️ Emerging Bear | +5.2% | +0.1% |
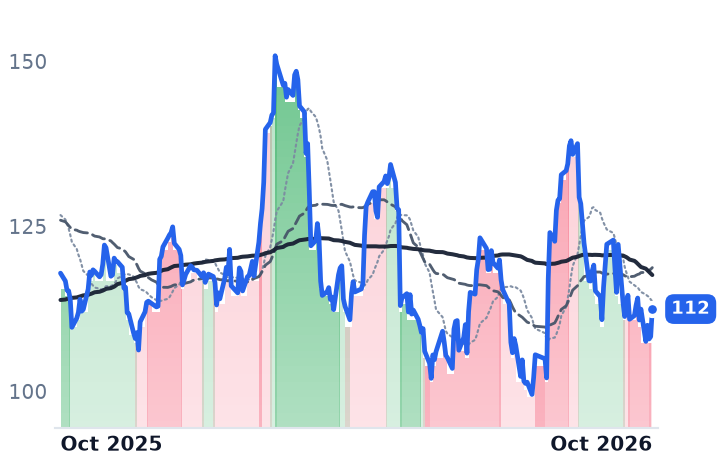
BDC | Belden | Enterprise Networking Infrastructure | 🔴 Cont. Bear | −5.4% | −4.6% |
PLPC | Preformed Line Products | Electrical Infrastructure Products | 🟢 Cont. Bull | +6.8% | +110.4% |
APH | Amphenol | Connectors & Interconnect Systems | 🟢 Cont. Bull | +6.0% | −28.6% |
LFUS | Littelfuse | Power & Circuit Protection | 🟢 Cont. Bull | +10.2% | +77.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WCC | $18.6B | 26.1x | 22.7x | 0.7x | 0.7x | 3.5x | 3.3x | 15.4x | 0.8% |
ATKR | $3.2B | n/m | 14.9x | 1.1x | 1.0x | 5.5x | 5.2x | n/m | 1.8% |
TEL | $63.9B | 21.4x | 17.0x | 3.3x | 2.9x | 9.4x | 8.3x | 13.8x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BDC | $4.4B | 18.1x | 13.0x | 1.5x | 1.3x | 4.2x | 3.6x | 11.9x | 4.8% |
PLPC | $2.1B | 47.1x | 31.6x | 2.8x | 2.5x | 8.8x | 8.0x | 24.4x | 1.7% |
APH | $214.4B | 41.4x | 32.7x | 7.4x | 6.0x | 19.2x | 15.7x | 24.4x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LFUS | $11.6B | n/m | 27.5x | 4.4x | 4.0x | 11.3x | 10.1x | 41.6x | 3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WCC | Revenue | +11.8% | +6.4% | +5.1% |
| EPS | +25.6% | +19.0% | +18.2% | |
ATKR | Revenue | +5.0% | +4.7% | +6.6% |
| EPS | −13.4% | +11.5% | +13.6% | |
TEL | Revenue | +16.1% | +9.6% | +6.8% |
| EPS | +33.1% | +13.5% | +10.8% | |
BDC | Revenue | +25.2% | +17.0% | +5.1% |
| EPS | +16.3% | +15.5% | +11.8% | |
PLPC | Revenue | +20.1% | +8.0% | +9.1% |
| EPS | +87.4% | +7.5% | +10.2% | |
APH | Revenue | +55.3% | +18.5% | +12.8% |
| EPS | +61.0% | +22.8% | +14.1% | |
LFUS | Revenue | +23.1% | +9.0% | +11.2% |
| EPS | +58.0% | +16.2% | +15.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A distributor and a manufacturer sat on opposite sides of the same price increase last quarter, and only one of them liked it. WESCO International, the Pittsburgh distributor of wire, conduit, transformers and pole-line hardware it does not make, widened its gross margin to 21.8% in the June quarter. Atkore, which buys steel and resin and sells conduit by the foot, grew sales 8.1% and watched its adjusted profit margin fall anyway.
Both are selling into the same electrification build-out, and both are selling more. What separates them is who owns the conversion step — the point where a raw commodity becomes a finished foot of product at a posted price. That is where an input shock lands, and the shock has been large: US producer prices for steel mill products rose 22.5% and copper wire and cable 17.9% in the year to July 2026, after a 50% Section 232 tariff on semi-finished copper products took effect on 6 April, with copper at $6.52 a pound in early September.
Conversion pays the bill
Atkore absorbs that as cost of goods. Its fiscal third-quarter net sales were $794.8m and adjusted EBITDA $104.7m, up $4.7m, while the margin on it fell because input cost increases outpaced increases in average selling prices. The Safety & Infrastructure segment, which sells metal framing and mechanical pipe, grew sales 1.3% and saw its adjusted EBITDA margin fall from 14.4% to 13.0%. Volumes are recovering — revenue growth went from -0.9% to 8.1% across three quarters — and gross margin has climbed off a 18.3% trough to 22.2%. Against the 41.0% of fiscal 2022, the price-per-foot collapse has not been repaired.
It will not be repaired on the public market. Prysmian agreed on 3 August to buy Atkore for $95.00 a share in cash, roughly a 30% premium; the stock closed at $94.62 on 2 October, US antitrust clearance arrived on 14 September and shareholders vote on 7 October.
Resale collects it
WESCO owns no conversion, so the supplier increase arrives as price. Its June-quarter gross margin expanded about 70 basis points to 21.8%, reflecting volume growth across all three segments and an estimated 3% price benefit — a benefit that falls to gross profit at almost no incremental cost. On reported figures the margin has widened four quarters running, and operating income grew 18.6% against sales growth of 13.0%, which is leverage rather than inflation passing through a fixed spread.
The volume evidence is the part that matters. Backlog closed the quarter at a record, up roughly 60% year on year, with communications and security up about 95% and the utility and broadband business up about 80%; data-centre sales reached about $1.5bn, up 45%, now more than a fifth of trailing sales. "Our backlog growth was fueled by multi-year customer commitments demonstrating our transformation into a leading infrastructure solutions provider," chairman and chief executive John Engel said on 30 July. On the call he pointed to mid-single-digit growth excluding data centres, which is the answer to the objection that this is one customer type. Guidance went up, to organic growth of 9–11% and adjusted earnings of $16.00 to $17.50 a share.
The shares have followed, up about 77% over twelve months, and at 22.7x forward earnings against 26.1x trailing the multiple is not demanding next to consensus of $16.83 for 2026 and $20.03 for 2027 — nor is it cheap. Preformed Line Products, which makes the formed-wire hardware that terminates and protects conductors, grew June-quarter revenue 25.4% with gross margin up to 34.3% and trades at 31.6x forward. Belden, maker of signal cable, racks and industrial switches, is the one name here actually down over the year, 4.7% lower despite revenue growth of 11.6% and a 39.1% gross margin, at 13.0x forward.
The third meter
TE Connectivity is paid per connector on design wins, with metal content largely passed through, so cost inflation is neither a windfall nor a squeeze — its fiscal third-quarter operating margin held at 19.0% on revenue growth of 13.8%. Orders were a record $5.7bn, up 27%, and chief executive Terrence Curtin said on 22 July that "our teams delivered record third quarter results above guidance, with strong growth performance in both segments" (8-K); artificial-intelligence cloud revenue is now expected to clear its $3bn fiscal-2027 target early. The shares are 0.2% lower than a year ago. At 17.0x forward against 21.4x trailing, with a 5.7% free-cash-flow yield and consensus earnings of $11.45 for fiscal 2026, up 33%, it is the widest gap here between rising estimates and a flat price; the likelier reading is that the market paid for this year some time ago. Amphenol, the larger interconnect company, grew June-quarter revenue 55%.
So the mechanism ranks these businesses rather than the demand story does. Distribution converts a supplier price increase into gross profit and needs only the volume to keep arriving; conversion needs its own posted price to catch a cost it does not control, and Atkore's answer to that question is now a fixed cash number. The uncomfortable corollary belongs to WESCO: about three points of its growth is price it did not create. If steel and copper roll over, that goes with them, and the record backlog has to deliver the units on its own.