

Vulcan and Martin Marietta's Highway Authority Runs to December 11, Not Today
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The federal deadline the aggregates producers have been discounting all quarter passed without passing. A continuing resolution signed on 2 September already extended surface transportation authority and pro-rated highway contract authority at fiscal 2026 levels to 11 December 2026, and no successor multi-year bill has been introduced.
Meanwhile the June quarter showed the opposite of a demand collapse: tons shipped rose at Vulcan, Martin Marietta and Knife River, and all three raised mix-adjusted price per ton. What broke was the conversion of price into profit. Vulcan's cash gross profit per ton moved from $11.88 to $12.02 against a roughly $40m quarterly diesel headwind, and Martin Marietta's aggregates gross profit per ton fell 17% to $6.78. Diesel turned down last week for the first time since July — still $2.63 a gallon above a year ago.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
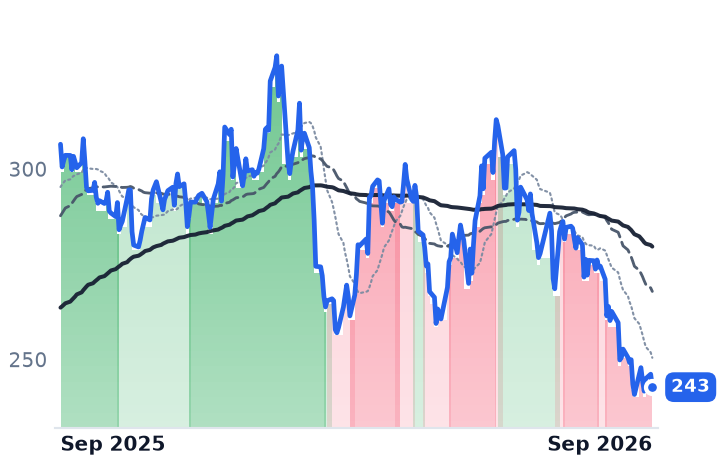
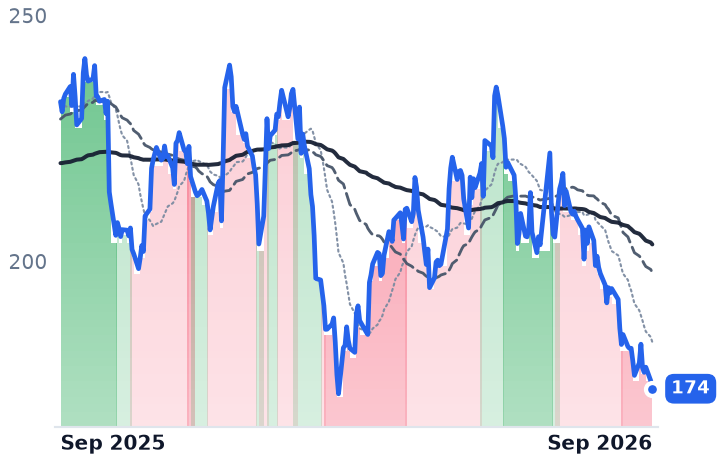
VMC | Vulcan Materials | Aggregates & Concrete | ⚠️ Emerging Bear | −10.5% | −20.8% |
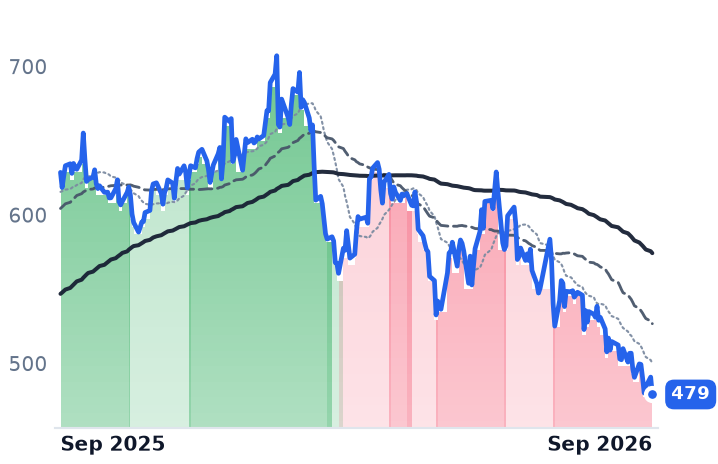
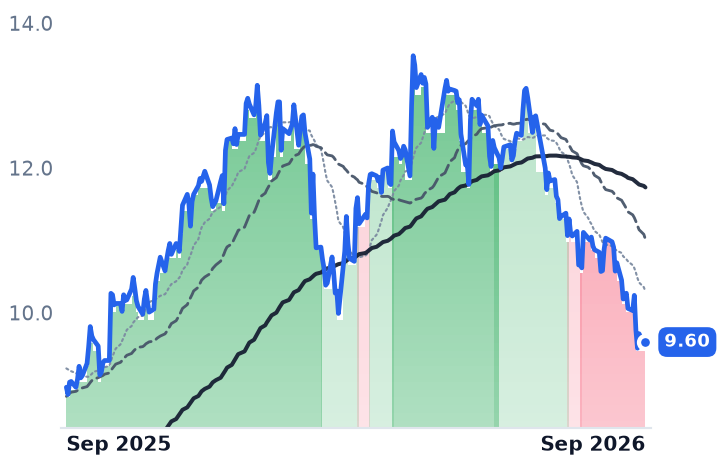
MLM | Martin Marietta Materials | Aggregates & Concrete | 🔴 Cont. Bear | −8.4% | −23.8% |
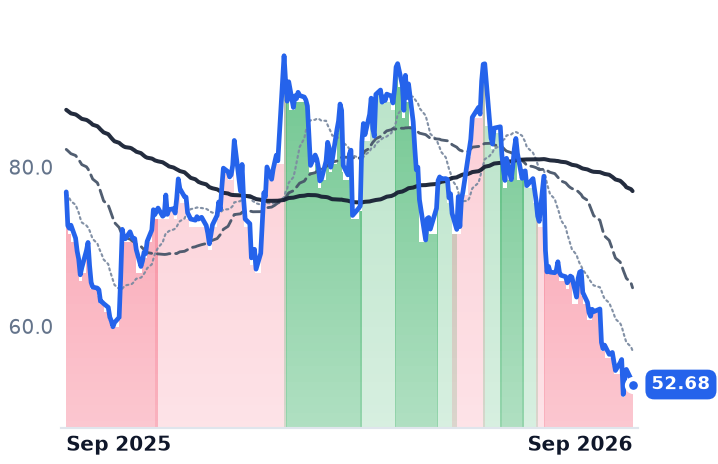
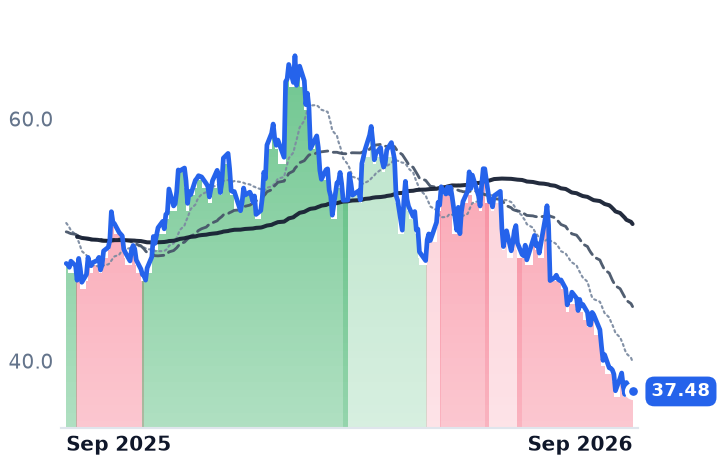
KNF | Knife River | Aggregates & Concrete | 🔴 Cont. Bear | −16.4% | −31.5% |
| Compared against · context, not the story | |||||
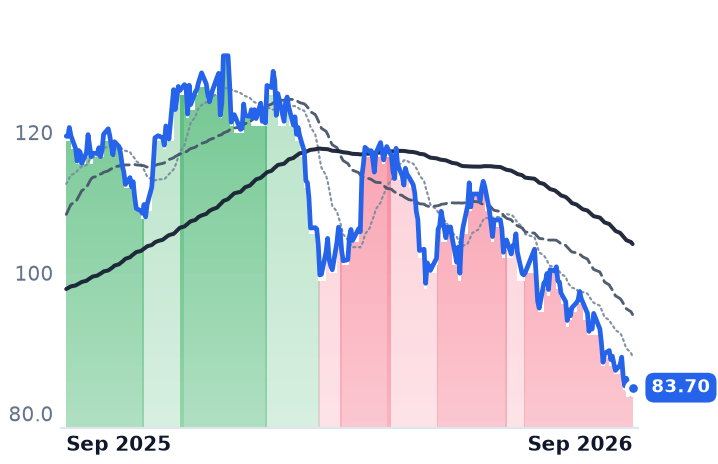
CRH | CRH | Integrated Cement & Materials | 🔴 Cont. Bear | −11.2% | −29.9% |
EXP | Eagle Materials | Specialty Building Products | 🔴 Cont. Bear | −10.8% | −25.1% |
CX | CEMEX, S.A.B. de C.V | Integrated Cement & Materials | ⚠️ Emerging Bear | −11.4% | +7.0% |
AMRZ | Amrize | Regional Building Materials | 🔴 Cont. Bear | −14.8% | −22.0% |
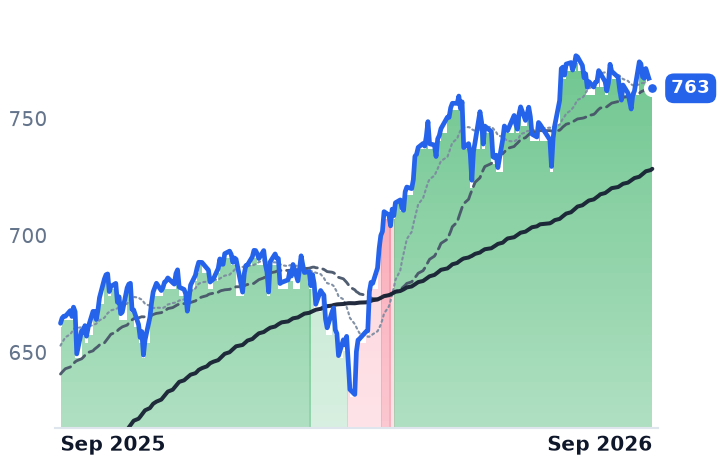
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.4% | +15.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VMC | $31.5B | 28.6x | 26.7x | 3.9x | 3.9x | 14.1x | 14.1x | 14.1x | 3.3% |
MLM | $28.8B | 11.7x | 26.4x | 4.3x | 4.0x | 15.2x | 14.1x | 16.6x | 2.8% |
KNF | $3.0B | 21.4x | 19.0x | 0.9x | 0.9x | 5.1x | 4.8x | 10.6x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRH | $69.0B | 13.7x | 17.3x | 1.2x | 1.7x | 3.5x | 4.9x | 7.9x | 4.2% |
EXP | $6.1B | 14.6x | 15.1x | 2.7x | 2.6x | 9.4x | 9.3x | 9.6x | 3.8% |
CX | $18.2B | 40.6x | 15.6x | 1.1x | 1.1x | 3.4x | 3.2x | 9.5x | 4.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMRZ | $27.1B | — | 17.6x | — | 2.2x | — | — | — | — |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VMC | Revenue | +2.3% | +5.5% | +6.2% |
| EPS | +8.4% | +15.9% | +15.4% | |
MLM | Revenue | +9.0% | +7.0% | +8.9% |
| EPS | +0.1% | +18.8% | +17.2% | |
KNF | Revenue | +10.7% | +4.1% | +4.3% |
| EPS | +6.2% | +18.8% | +10.5% | |
CRH | Revenue | +5.9% | +5.1% | +6.8% |
| EPS | +6.8% | +12.7% | +12.0% | |
EXP | Revenue | +0.5% | +1.9% | +5.8% |
| EPS | −9.4% | −0.1% | +13.5% | |
CX | Revenue | +7.1% | +4.2% | +2.8% |
| EPS | −12.0% | +13.6% | +17.0% | |
AMRZ | Revenue | +4.9% | +5.7% | +6.1% |
| EPS | +19.4% | +14.3% | +15.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The federal highway program was supposed to run out of authority today. It did not. A continuing resolution signed on 2 September extended the Infrastructure Investment and Jobs Act's surface transportation authorities and pro-rated Highway Trust Fund contract authority at fiscal 2026 levels through 11 December 2026, while cutting enacted transportation funding by a quarter in total — transit down 20%, rail down 82%. Highways were held level and given ten more weeks.
Ten weeks is not a program. No successor multi-year bill has been introduced, and county and state bodies warn that if none arrives, formula funding for highways, bridges and transit reverts to pre-IIJA levels — a $36.8bn annual shortfall — because trust fund revenues cannot carry current spending. The question the quarry operators' shares have been marking down since July was deferred, not answered.
The tons went up
The premise that demand cracked is wrong. Vulcan Materials, the largest US producer of crushed stone, sand and gravel, shipped 59.9m tons in the June quarter, up 1%, with freight-adjusted prices up 3.9% and mix-adjusted prices up 4.7%. Martin Marietta Materials, the number-two aggregates producer, which also sells magnesia chemicals and dolomitic lime, shipped a record 61.6m tons, up 17% on acquisitions and 2.3% organically, at mix-adjusted pricing up 3.7%. Knife River, which consumes its own aggregates in ready-mix and asphalt and bids heavy-civil and paving work for public agencies, lifted mix-adjusted pricing 8% on volumes up 14%.
What failed was the conversion. Vulcan's cash gross profit per ton went from $11.88 a year earlier to $12.02 — fourteen cents, against a price increase four times that size — because diesel cost it nearly $40m in the quarter. "Price is our biggest lever when it comes to overcoming headwinds like this and inflationary pressures," chief executive Ronnie Pruitt told analysts on Vulcan's 29 July call. Martin Marietta's aggregates gross profit per ton fell 17% to $6.78, of which 84 cents was the accounting charge for selling acquired inventory written up to fair value. Operating income fell at all three on revenue that grew.
The control is holding
Knife River is the check on whether project starts are deflating, and they are not: backlog rose roughly $50m sequentially to a record $1.2bn, and the company raised 2026 revenue guidance to $3.4bn-$3.6bn while trimming expected full-year aggregates margin expansion from two percentage points to about one. "With the majority of the construction season still ahead of us, we have opportunities to execute on our $1.2 billion contracting services backlog," chief executive Brian Gray said on the 4 August call. Starboard Value wrote to the board on 24 September demanding a plan for at least 22% adjusted EBITDA margins by fiscal 2029, or a look at strategic alternatives.
The de-rating has been broad and gradual. Vulcan closed at $242.75 on 29 September, down about a fifth over twelve months; Martin Marietta at $479.09, down about a quarter; Knife River at $52.68, the deepest faller. Neither pure quarry operator has a session worse than 3.8% in the last thirty. CRH, Eagle Materials and Cemex all fell roughly a tenth over the same month — this is the heavy-materials complex, not three companies.
Vulcan's price to trailing gross profit has compressed to 14.1x from 17.7x in early May, and it trades at 26.7x forward earnings — 23x the 2027 consensus. Martin Marietta is at 26.4x forward, with a trailing EV/EBITDA of 16.6x that describes a company superseded by the $13.5bn Lhoist North America combination closed on 21 August, which adds $786m of EBITDA. Knife River is the cheapest on the measure that fits a leveraged, low-margin producer, at 10.6x trailing EV/EBITDA.
What the evidence settles
Pricing power is intact and volumes are rising; neither earns the de-rating. What does earn it sits between the two: an input cost that took the entire price increase, and a funding calendar that now runs in ten-week increments. On the first there is finally movement — US on-highway diesel averaged $6.382 a gallon in the week to 28 September, down 14.7 cents and the first weekly decline in twelve weeks. One week does not undo $2.63 a gallon of year-on-year inflation, and consensus already has 2026 EBITDA below 2025 at all three names before a 2027 recovery nobody has authorized highway money for.
None of the three has announced a third-quarter date. Knife River earns its year in two quarters — it lost $84.2m at the operating line in March — and whatever that quarter shows will be public before Congress returns to the December deadline it wrote for itself.