

Ramaco's Two Share Classes Are Worth $780m Against the $8bn It Models for Brook Mine
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
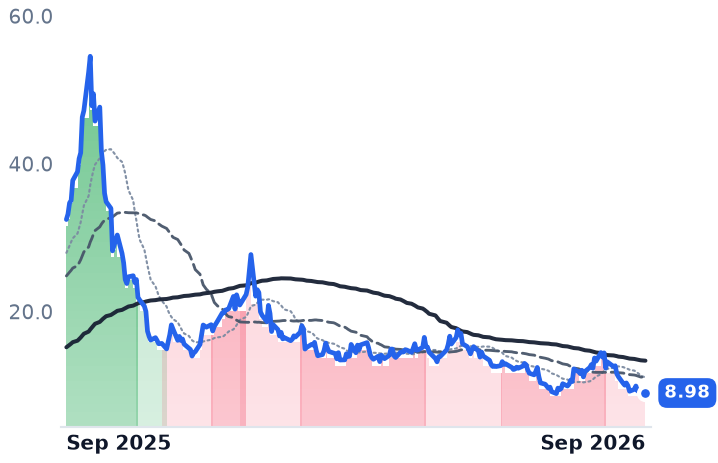
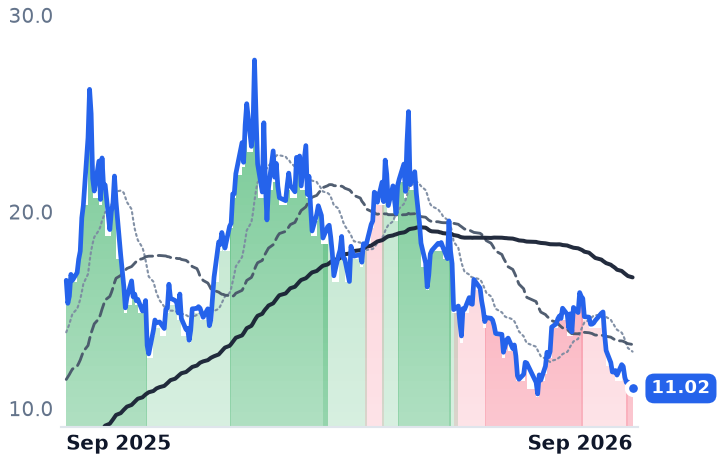
Ramaco's two listed share classes have decoupled from each other. The Class B stock is a tracking share for the company's royalties, tolling fees and its Brook Mine rare-earth project in Wyoming, and through September it fell with MP Materials and the rest of the critical-minerals complex — roughly twice as hard — while the coking coal benchmark its mines sell into sat near a 17-month high at $266.50 a tonne, up 39.5% on the year.
The coal underneath is losing money: a June-quarter realized price of $116 a ton, a -12.6% operating margin and a sixth consecutive operating loss. Warrior Met and Alpha Metallurgical, both of which steadied after mid-September, are the evidence that what is being taken back at Ramaco is not a coking-coal price but a critical-minerals premium on a mine that does not produce until 2031.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
METC | Ramaco Resources | Metallurgical Coal Producers | 🔴 Cont. Bear | −37.9% | −72.3% |
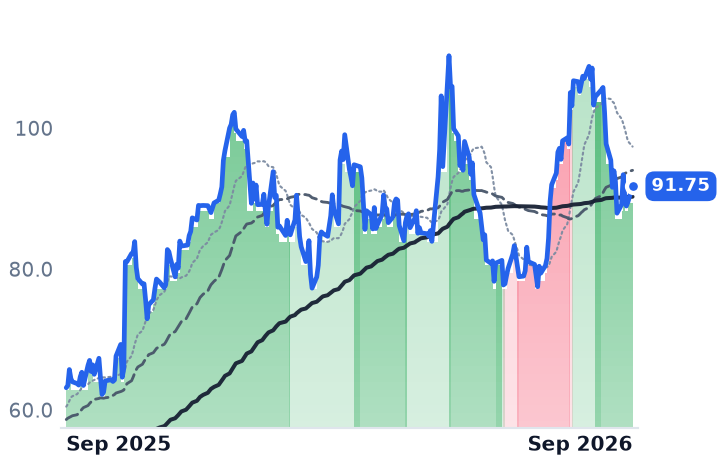
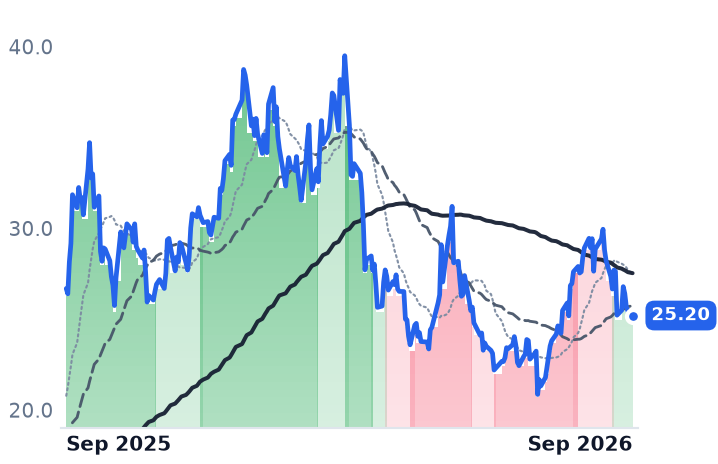
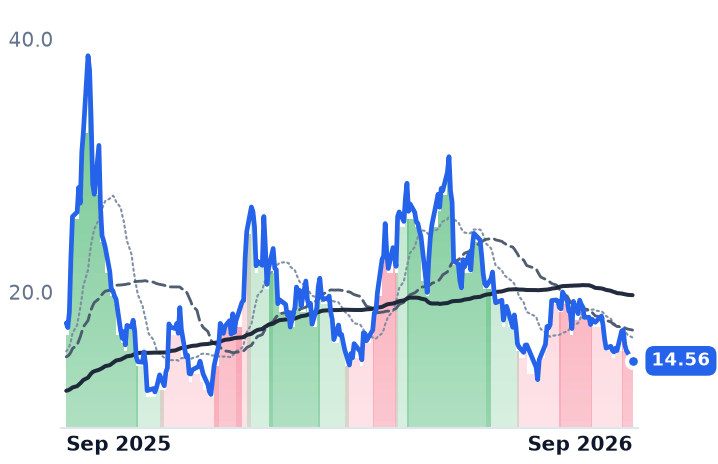
HCC | Warrior Met Coal | Metallurgical Coal Producers | 🟢 Cont. Bull | −15.6% | +45.3% |
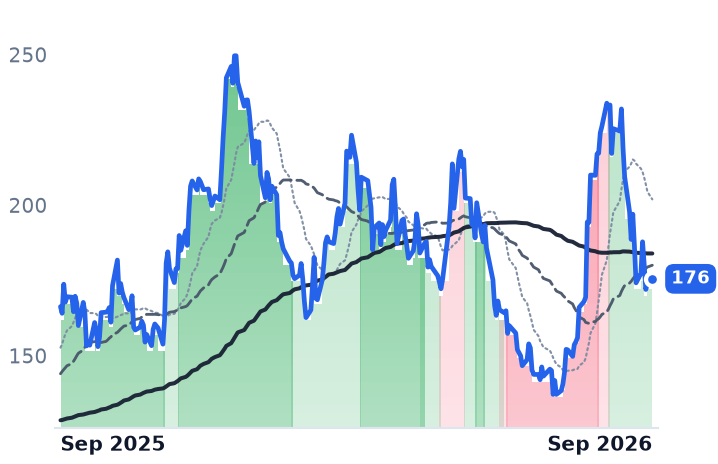
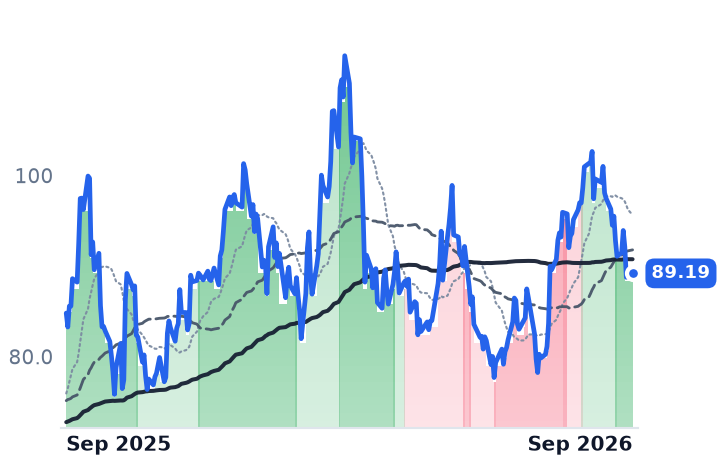
AMR | Alpha Metallurgical Resources | Metallurgical Coal Producers | ⚠️ Emerging Bear | −24.9% | +5.5% |
| Compared against · context, not the story | |||||
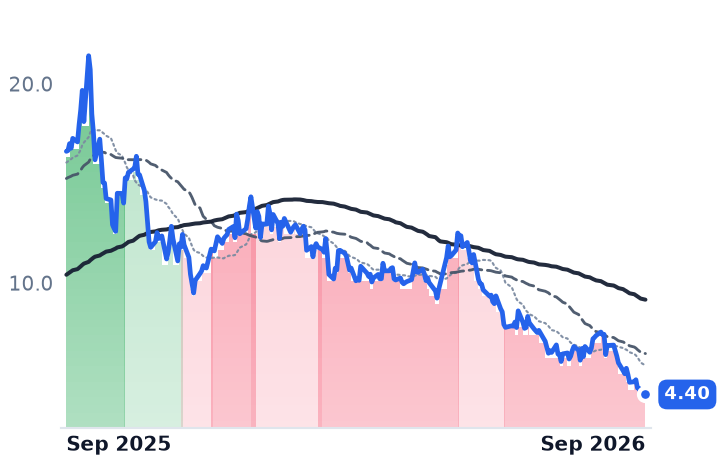
METCB | Ramaco Resources | Metallurgical Coal Producers | 🔴 Cont. Bear | −41.6% | −73.5% |
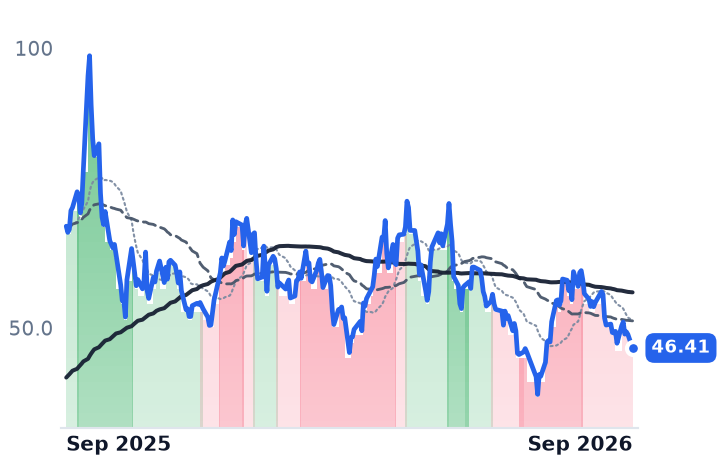
BTU | Peabody Energy | Thermal Coal Producers | ⚠️ Emerging Bear | −14.4% | −5.6% |
CNR | Core Natural Resources | Diversified Coal & Royalties | 🟢 Cont. Bull | −12.0% | +5.2% |
MP | MP Materials | Rare Earth & Magnets | 🔴 Cont. Bear | −15.8% | −31.9% |
USAR | USA Rare Earth | Rare Earth & Magnets | ⚠️ Emerging Bear | −19.2% | −17.0% |
UUUU | Energy Fuels | Uranium | 🔴 Cont. Bear | −24.8% | −33.3% |
TMC | TMC the metals | Deep-Sea & Alternative Sources | 🔴 Cont. Bear | −20.0% | −41.5% |
NB | NioCorp Developments | Deep-Sea & Alternative Sources | 🔴 Cont. Bear | −16.8% | −47.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
METC | $483.2M | n/m | — | 0.9x | 0.8x | 21.9x | 19.7x | n/m | -28.1% |
METCB | $855.1M | n/m | — | 1.5x | 1.4x | 115.7x | 109.7x | 148.4x | -17.8% |
HCC | $4.8B | 22.1x | 14.6x | 2.9x | 2.4x | 6.9x | 5.8x | 10.5x | 0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMR | $2.2B | n/m | — | 1.1x | 1.1x | 33.4x | 32.5x | 17.7x | -0.1% |
BTU | $3.5B | n/m | — | 0.9x | 0.8x | 39.6x | 37.1x | 11.8x | 13.0% |
CNR | $4.2B | n/m | 25.6x | 1.0x | 0.9x | 129.8x | 124.9x | 7.7x | 5.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MP | $10.5B | n/m | 522.6x | 34.2x | 23.4x | — | — | 177.5x | -4.8% |
USAR | $2.6B | n/m | — | 194.4x | 32.3x | — | — | n/m | -9.6% |
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TMC | $2.3B | n/m | — | n/m | 6.9x | — | — | n/m | -1.5% |
NB | $779.3M | n/m | — | n/m | 5.6x | — | — | n/m | -2.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
METC | Revenue | +2.9% | +21.3% | +25.3% |
| EPS | −3.8% | −94.7% | −1238.4% | |
METCB | Revenue | +8.0% | +20.5% | — |
| EPS | — | — | — | |
HCC | Revenue | +54.0% | +9.9% | +4.9% |
| EPS | +524.3% | +30.3% | +13.3% | |
AMR | Revenue | −0.5% | +21.6% | +5.0% |
| EPS | −22.7% | −527.2% | +35.4% | |
BTU | Revenue | +11.1% | +8.3% | −0.7% |
| EPS | −59.9% | −1581.4% | +3.9% | |
CNR | Revenue | +6.7% | +6.1% | +2.3% |
| EPS | −278.8% | +121.1% | +25.5% | |
MP | Revenue | +90.7% | +75.5% | +24.3% |
| EPS | −129.5% | +723.3% | +57.6% | |
USAR | Revenue | +980.4% | +592.8% | +163.6% |
| EPS | −75.2% | −59.4% | −249.2% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
TMC | Revenue | −67.5% | −61.6% | +348.3% |
| EPS | −71.5% | −25.4% | −305.1% | |
NB | Revenue | — | −50.0% | +100.0% |
| EPS | +79.1% | −42.3% | +38.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ramaco Resources has two listed share classes, and only one of them is about coal. The Class B stock is a tracking share covering the company's coal royalties, logistical tolling fees, intellectual property and possible revenue from exploratory rare earth elements and critical minerals — in practice, the Brook Mine project in Wyoming. Through September it was marked down roughly twice as hard as the rare-earth miners it now resembles, while the seaborne coking coal benchmark that sets prices for the Class A mines sat near a 17-month high.
That split is the whole story of the equity. Ramaco's coal business — underground and surface mines at Elk Creek, Berwind, Knox Creek and the RAM Mine in West Virginia, Virginia and Pennsylvania, selling to blast-furnace steelmakers and coke producers — has posted an operating loss for six consecutive quarters. So what an investor owns here is substantially a claim on a project that will not produce until 2031 and needs $3.2bn of capital to get there. Both share classes together are worth about $780m.
The coal book is a cost story, not an earnings one
June-quarter revenue fell 5.3% to $144.8m, with an operating margin of -12.6% and a net loss of $15.4m. The realized coal price averaged $116 a ton, down 6% from a year earlier on weakness in US high-volatile markets, though up $2 from the March quarter. Costs are the part that is working. "Second quarter mine cost at $99 a ton represented the fourth consecutive quarter of sub 100 cash costs," chairman and chief executive Randall Atkins told investors on 5 August. Roughly $17 a ton of margin does not cover the rest of the business: consensus has Ramaco losing $0.95 a share this year, losing $0.05 next year, and reaching a first profit of $0.58 in 2028 — on an estimate range running from -$1.23 to +$3.60, which is the Brook Mine question, not the coal one.
What the market pays for Wyoming
On 29 July Ramaco released an independent conceptual study by Hatch Associates superseding an earlier Fluor report. Running its own model on Hatch's capital and operating inputs, Ramaco produced a potential net present value of $8bn and average annual adjusted earnings before interest, taxes, depreciation and amortization of $1.3bn, against capital cost of $3.2bn plus $0.8bn of contingency and first production in 2031. Hatch has since been retained to lead a Preliminary Feasibility Study, with interim revised economics expected by year-end.
Against that, the Class A stock carries a market capitalization of $483m and the Class B shares — 63.68m outstanding — $297.4m. Trailing free cash flow yield is -28.1%: this equity funds a project rather than harvesting one.
The move was a minerals move
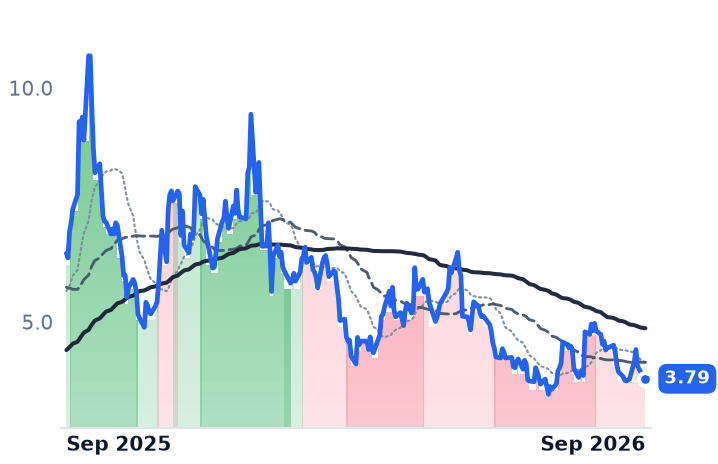
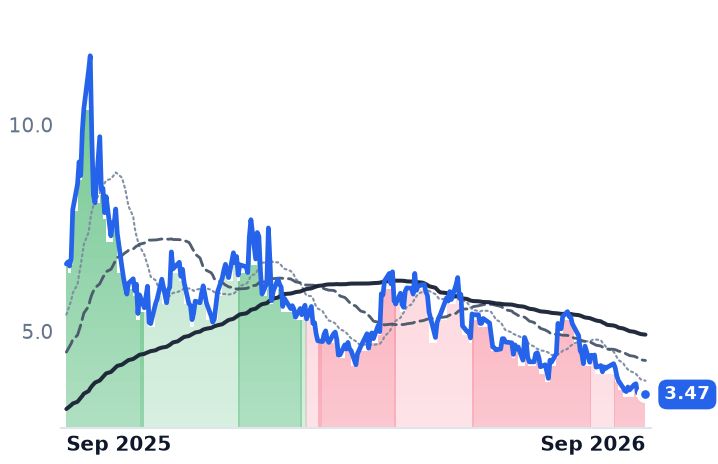
From 31 August to 28 September the Class B shares fell 41.6%. Over the same stretch MP Materials fell 15.8%, USA Rare Earth 19.2% and Energy Fuels 24.8%, as reports that a US–China summit could ease trade tensions deflated the scarcity premium that had powered the complex. A mechanical event compounded it: Ramaco said on 4 September that negative trading in its Class A stock the prior day traced to Yorktown Energy Partners distributing about one million Class A shares to its limited partners on 2 September.
The coal producers are the check. Australian premium hard coking coal was $266.50 a tonne on 28 September, down 5.5% on the month but 39.5% higher than a year earlier, after hitting a 17-month high — driven by Chinese supply, where safety checks across Shanxi after a fatal mine blast slowed restarts and pushed mills into the seaborne market. Warrior Met, which mines premium low-volatility coal in Alabama, sold a record 3.7m short tons in the June quarter at $138 a ton against cash cost near $93, generated $103.4m of free cash flow, and has finished Blue Creek at $1,022.9m with 2026 capital spending guided down to $130–150m. It trades at 14.56x forward earnings against 22.06x trailing. Alpha Metallurgical, with nineteen mines in Central Appalachia, realized $118.71 a ton against $103.07 of cost and raised its full-year cost guidance to $103.00–107.00 from $95.00–101.00; at 17.73x trailing enterprise value to EBITDA it is valued at 1.7 times Warrior's 10.52x on a fraction of the cash margin. Since 18 September Warrior has added 4.3% and Alpha 0.8%. Only Ramaco's Class B kept falling, another 12.2%.
So the September give-back in the two producers looks like the unwinding of an August squeeze the benchmark never endorsed — coal prices rose over the twelve months in which these equities were supposedly pricing collapse. At Ramaco the residual is different in kind. With coal steady and the tracking stock alone still sliding, what is being repriced is the critical-minerals option bolted onto a loss-making coal miner, and the discount to management's own $8bn — better than nine-tenths of it — is the market's price for a 2031 start date and a capital bill the coal book cannot fund.
The interim economics Hatch is due to deliver by year-end will be the first set of Brook Mine numbers Ramaco did not model itself.