

Charter Bills $117.52 a Month Where Fiber Rivals Sell a Gigabit for $30
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The equity case for cable was that a coaxial line into a house is an annuity. That case is being repriced by whoever builds the second line, and both meters — how many homes pay, and how much each pays — moved the wrong way at once in the June quarter.
Charter lost 172,000 internet customers, worse than the 116,000 it lost a year earlier, while monthly residential revenue per customer fell 1.8%; Comcast's broadband revenue per user fell 3.8%. Comcast's theme parks and Peacock did not mask it — parks earnings fell 5.1%. The business explains these declines. What it does not explain is why Comcast, the cheapest of the three at just over six times forward earnings, has no buyback running to close the gap until its NBCUniversal spin completes.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
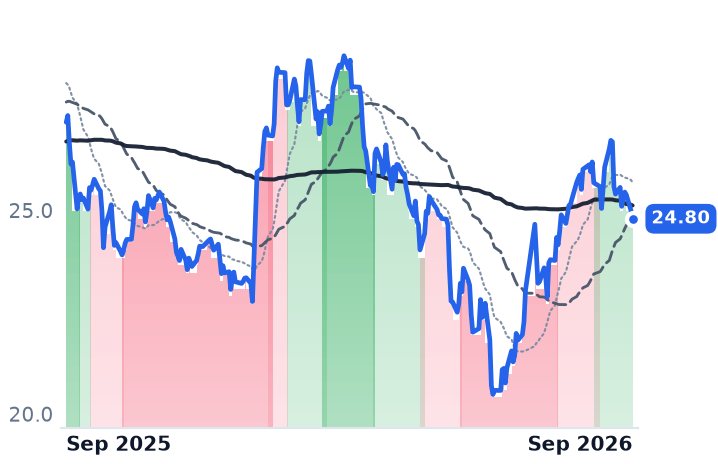
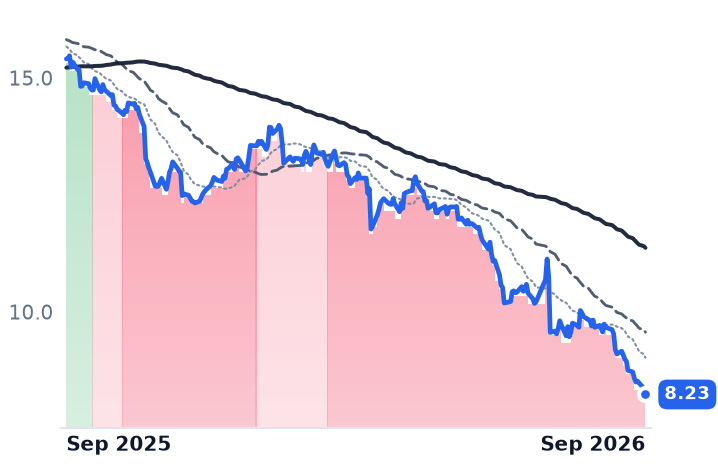
CHTR | Charter Communications | Broadband & Fixed Services | 🔴 Cont. Bear | −26.0% | −59.3% |
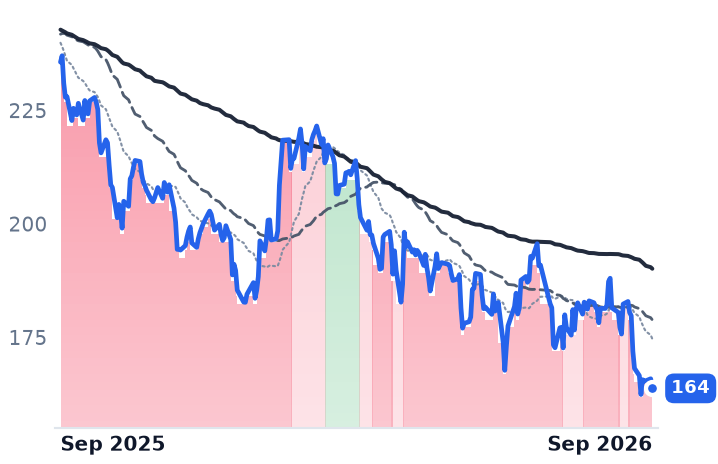
CMCSA | Comcast | Broadband & Fixed Services | 🔴 Cont. Bear | −19.1% | −24.2% |
LUMN | Lumen Technologies | Broadband & Fixed Services | ⚠️ Emerging Bear | −7.8% | −6.3% |
| Compared against · context, not the story | |||||
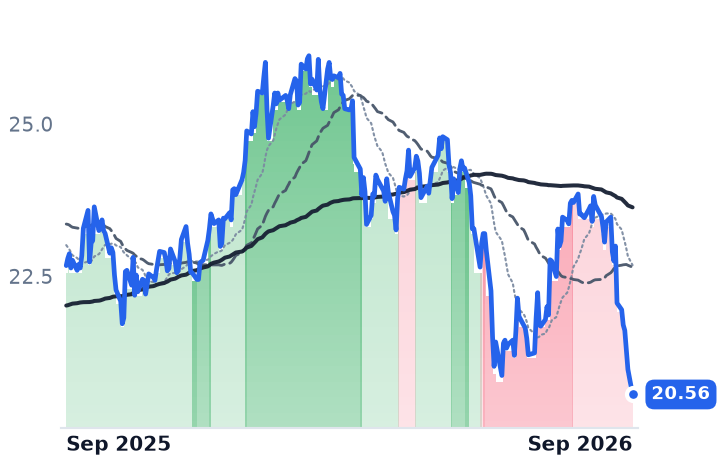
VZ | Verizon Communications | Wireless Carriers | 🌱 Emerging Bull | −7.3% | +13.0% |
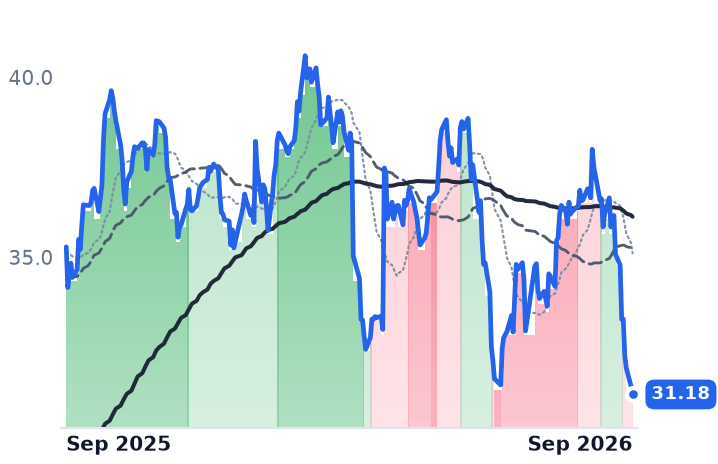
T | AT&T | Wireless Carriers | 🔴 Cont. Bear | −5.0% | −8.7% |
TMUS | T-Mobile US | Wireless Carriers | 🔴 Cont. Bear | −9.7% | −30.5% |
BCE | BCE | Broadband & Fixed Services | 🔴 Cont. Bear | −12.9% | −9.3% |
RCI | Rogers Communications | Broadband & Fixed Services | 🔴 Cont. Bear | −15.5% | −11.6% |
TU | TELUS | Broadband & Fixed Services | 🔴 Cont. Bear | −15.2% | −46.5% |
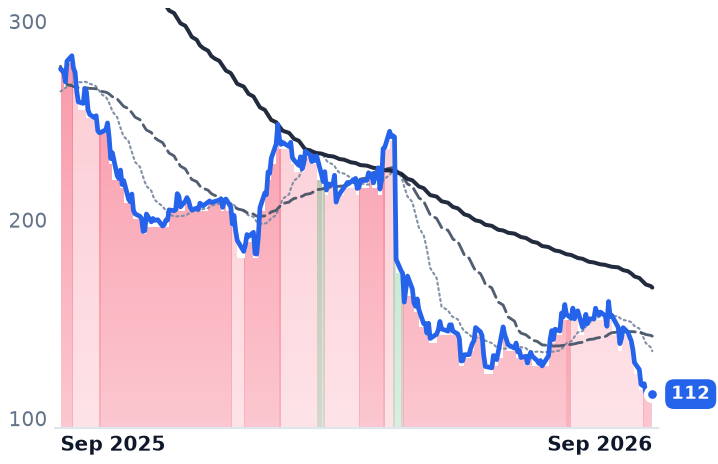
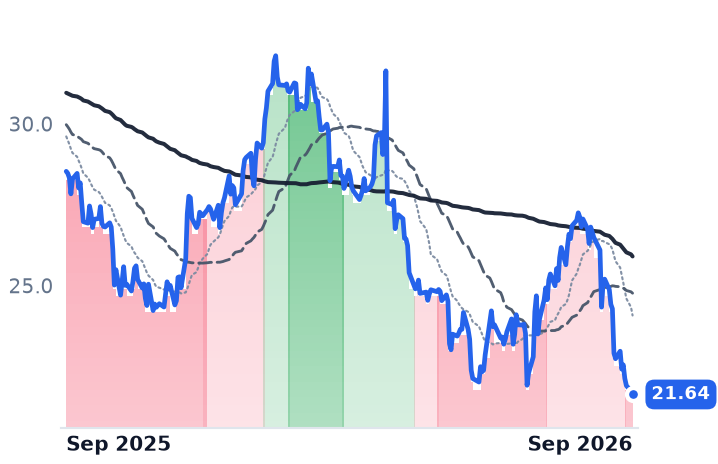
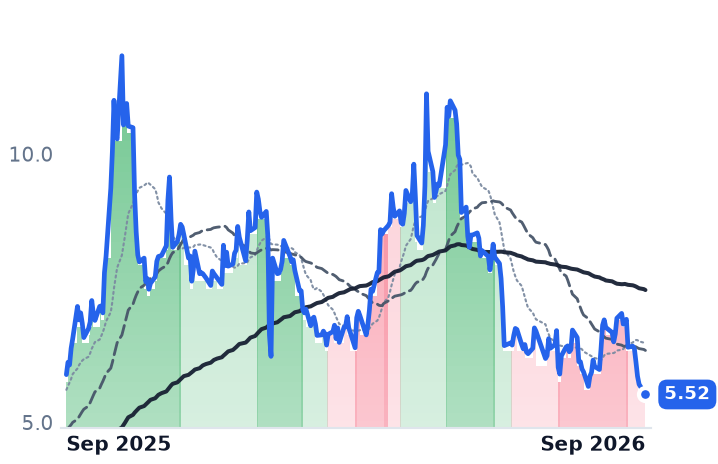
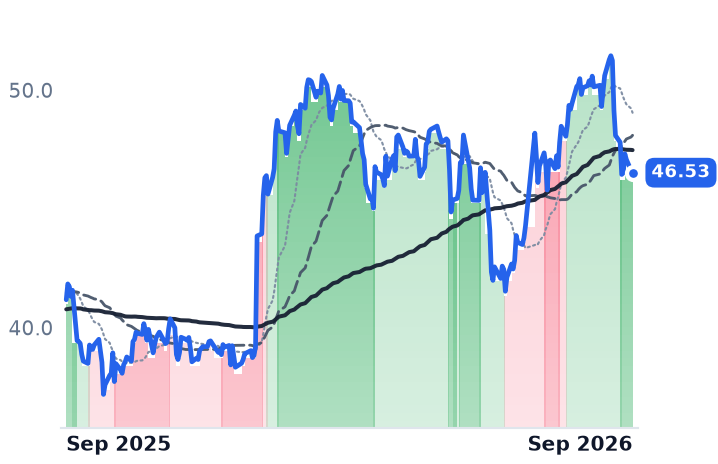
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CHTR | $14.9B | 2.8x | 2.7x | 0.3x | 0.3x | 0.5x | 0.5x | 5.5x | 29.2% |
CMCSA | $76.7B | 7.0x | 6.2x | 0.6x | 0.6x | 0.9x | 0.9x | 4.7x | 26.7% |
LUMN | $5.7B | n/m | — | 0.5x | 0.5x | 1.0x | 1.1x | 7.7x | 14.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VZ | $202.4B | 12.6x | 9.7x | 1.5x | 1.4x | 2.5x | 2.4x | 8.1x | 10.6% |
T | $170.5B | 8.2x | 10.6x | 1.3x | 1.3x | 2.2x | 2.2x | 5.9x | 10.4% |
TMUS | $195.9B | 19.1x | 16.7x | 2.1x | 2.1x | 3.9x | 3.8x | 10.9x | 7.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BCE | $22.2B | 4.7x | 9.0x | 1.2x | 0.9x | 2.1x | 1.5x | 4.9x | 9.0% |
RCI | $19.1B | 3.7x | 10.3x | 1.2x | 0.8x | 3.5x | 2.5x | 4.6x | 9.8% |
TU | $19.1B | 28.2x | 18.2x | 1.3x | 0.9x | 3.0x | 2.1x | 7.5x | 6.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CHTR | Revenue | −1.2% | −1.1% | −0.2% |
| EPS | +14.5% | +6.2% | +10.6% | |
CMCSA | Revenue | −2.9% | −2.0% | +2.2% |
| EPS | −14.2% | +2.7% | +7.5% | |
LUMN | Revenue | −10.4% | −3.8% | −1.4% |
| EPS | +41.1% | −64.4% | −30.2% | |
VZ | Revenue | +2.3% | +1.7% | +1.1% |
| EPS | +6.8% | +4.7% | +7.1% | |
T | Revenue | +3.4% | +2.1% | +2.1% |
| EPS | +13.6% | +9.4% | +13.7% | |
TMUS | Revenue | +7.1% | +4.4% | +4.0% |
| EPS | +10.2% | +27.4% | +20.0% | |
BCE | Revenue | +3.9% | +1.8% | +2.3% |
| EPS | −2.3% | +3.5% | +9.7% | |
RCI | Revenue | +6.5% | +1.3% | +1.8% |
| EPS | −4.0% | +7.7% | +6.7% | |
TU | Revenue | +2.5% | +2.4% | +2.5% |
| EPS | −5.2% | +7.1% | +12.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The price of a residential broadband connection in the United States is no longer set by the company that owns the wire into the house. Comcast's chief financial officer said so in public this month, and named the offer he will not match.
"So when we see fiber pricing, standalone fiber pricing, in the $30-$40 range for a gig, when we say irrational, that's what we mean by irrational," Jason Armstrong told the Goldman Sachs Communacopia + Technology Conference on September 9. He had already said competition "popped up a little bit in the second quarter" and "continued into the third quarter." The stake is not one quarter of subscriber numbers. It is whether an incumbent charging roughly three times the marginal fiber price can hold either its customers or its rate card, and three companies are answering that question with incompatible business models.
Charter: both meters moved
Charter, which sells Spectrum internet, video and resold mobile service to about 32 million customers across 41 states, lost 172,000 internet customers in the June quarter, against 116,000 a year earlier. The premise that price offsets volume failed in the same release: monthly residential revenue per residential customer was $117.52, down 1.8%, and residential internet revenue fell 3.2% to $5.8bn. Revenue has now fallen year over year for four straight quarters; adjusted EBITDA fell 4.3% and operating margin compressed to 22.6% from 24.4%.
Mobile is growing and not paying for it. Charter added 406,000 Spectrum Mobile lines and grew mobile service revenue 18.9% to $1.1bn on somebody else's network, while consolidated earnings still shrank. Chief executive Chris Winfrey defended the discounting on the July 24 call: "The last thing I want to do … is hamstring the ability of the company to go do some things to accelerate our growth."
The 2.71x forward earnings multiple is a distraction. At 5.53x enterprise value to EBITDA against a $14.9bn equity value, the listed stock is a stub on roughly 13% of the enterprise — implying about $100bn of net debt, before the roughly $12bn of Cox obligations that came with the $34.5bn Cox combination closed August 19-20. Consensus still models 2026 earnings up 14.5%; management guided standalone EBITDA to fall about 1%. Buybacks are paused, and chief financial officer Jessica Fischer — who told investors "Broadband ARPU will improve sequentially in Q3" — leaves on October 15.
Comcast: the conglomerate is not a hedge
Comcast's Connectivity & Platforms revenue fell 3.2% to $19.8bn with segment earnings down 5.8%, broadband revenue per user down 3.8%, and 167,000 domestic broadband customers lost — an improvement of 34,000, still a fourth consecutive quarterly loss. The theory that parks and content absorb the shock failed too: theme-park earnings fell 5.1% to $609m, and Peacock's first profitable quarter contributed $189m.
The shares now fetch 6.23x forward earnings, 4.67x EV/EBITDA and 0.86x book, on a trailing free-cash-flow yield of 26.7%. The mechanism that normally arbitrages that gap is switched off: the $15bn repurchase programme was suspended from July 1 until the NBCUniversal and Sky separation targeted for mid-2027. KeyBanc cut the stock to Underweight on September 25, modelling 2027 broadband losses of 665,000 and framing the trap plainly — match the cheap gigabit and lose revenue per user, refuse and lose customers, "Neither situation is a positive outcome".
Lumen sold the weapon
Lumen left the household altogether, selling its Quantum Fiber consumer base — over 1 million customers and more than 4 million enabled locations — to AT&T for $5.75bn, handing the buyer exactly the network type now undercutting cable. It is now paid by a different meter: hyperscalers prepay for conduit and capacity. Its Private Connectivity Fabric book reached about $13bn of contract value, and in the June quarter it took $476m of cash against $91m of recognised revenue. Reported revenue still fell 9.3%, legacy revenue 15%. Leverage is below 4x and 2026 free cash flow is guided to $1.9-2.1bn, yet Lumen carries the highest EV/EBITDA of the three at 7.75x on the fastest decline, and its forward price-to-sales multiple of 0.51x sits above the trailing 0.48x — the market pricing more shrinkage, not less.
What the shares did, and what it means
Over thirty sessions Charter fell 26.9% and Comcast 20.0%. This was a grind: strip Charter's two worst days and the remaining twenty still fall 17.7%. Verizon, on the winning side of the same price war, is up 7.6% over twelve months, so the money moved within the sector. Canada's regulated payers — BCE, Rogers, Telus — fell roughly half as much.
So the verdict splits. Charter's and Comcast's declines are earned: the price of a connection is being set by a competitor with a cost structure Comcast calls irrational, and New Street Research does not expect cable subscriber additions to turn positive this decade. Lumen's fall is a bet against a growth book no income statement makes legible. The unexplained part is Comcast's price against its own cash generation with the repurchase suspended — the cheapest of the three is also the one that cannot buy itself.
Charter reports on October 30, the first quarter consolidating Cox, which resets the denominator of every per-customer figure it publishes. The number that matters will still be set by somebody else's price list.