

Array's Order Book Hit a Record $2.5bn and Its Common Equity Is Minus $202m
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A tracker maker whose order book is at a record and whose guidance went up has lost nearly half its value since June, and the explanation sits below the operating line. Array Technologies took $500m of new bookings in the June quarter and raised 2026 revenue guidance to $1.4-1.5bn on 5 August, with trailing book-to-bill at 1.5x.
Utility-scale demand did not break the way residential did: Enphase's US installations and Sunrun's cash per new customer both fell hard, and Array's order book grew. What caps the common stock is the claim stack. $670m of convertible notes and a perpetual preferred carrying a $498.2m liquidation preference plus accrued dividends rank ahead of $589m of common, leaving book equity below zero. The cheap earnings multiple describes a residual, not the business.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
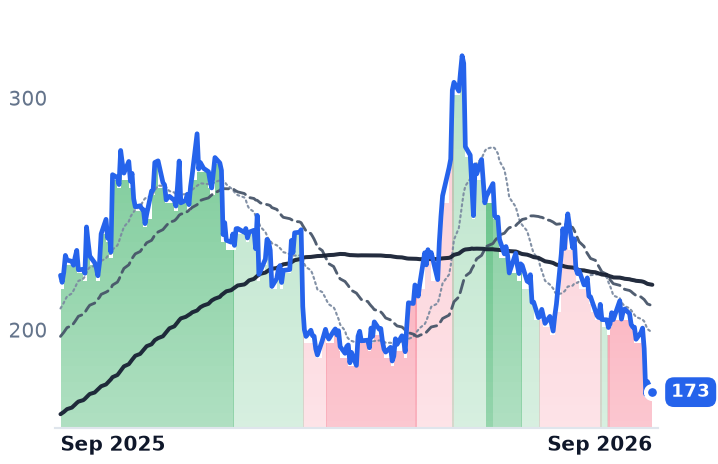
ARRY | Array Technologies | Solar Tracking Systems | 🔴 Cont. Bear | −13.5% | −52.5% |
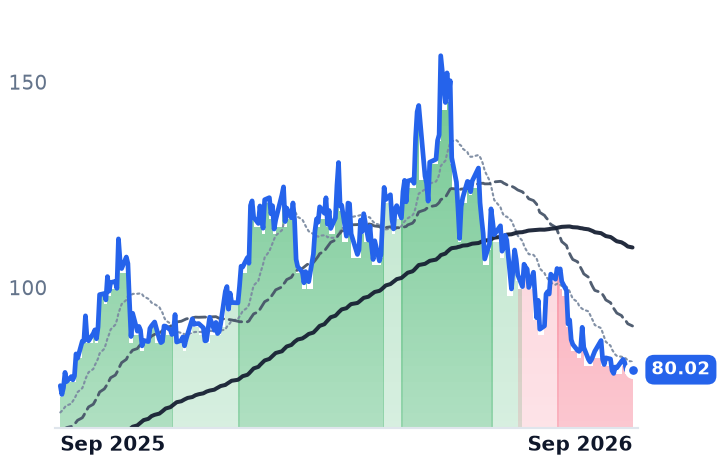
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −15.2% | −14.3% |
RUN | Sunrun | Residential Solar Installers | 🔴 Cont. Bear | −10.9% | −56.9% |
| Compared against · context, not the story | |||||
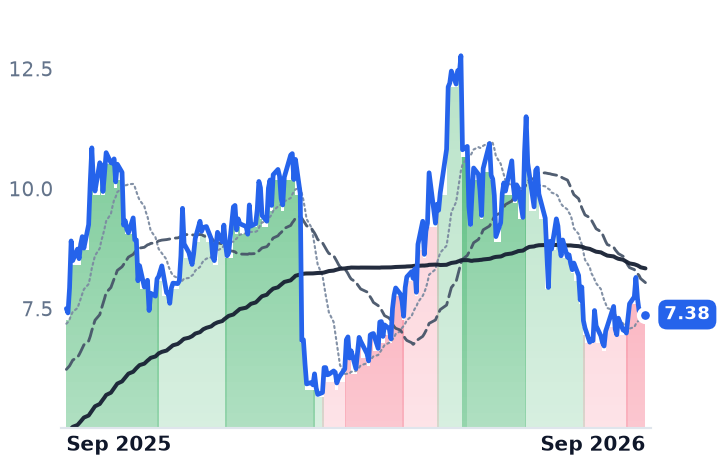
SEDG | SolarEdge Technologies | Inverters & Power Electronics | ⚠️ Emerging Bear | −0.7% | −15.7% |
FSLR | First Solar | Solar Module Manufacturers | ⚠️ Emerging Bear | −15.3% | −22.5% |
NXT | Nextpower | Other | ⚠️ Emerging Bear | −3.0% | +5.1% |
SHLS | Shoals Technologies | Solar System Components | ⚠️ Emerging Bear | +6.4% | −1.7% |
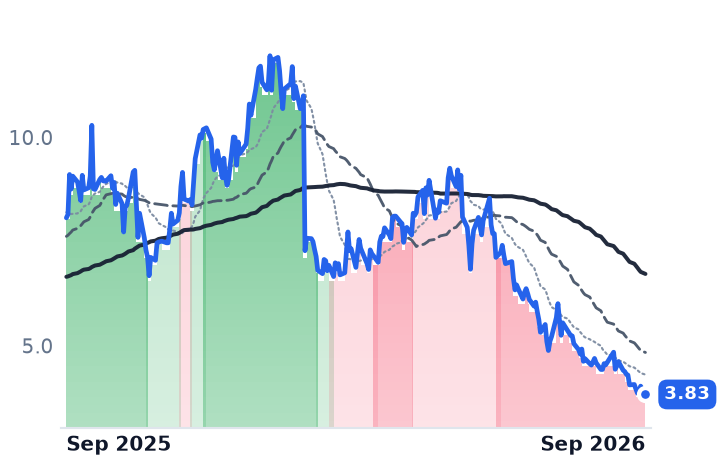
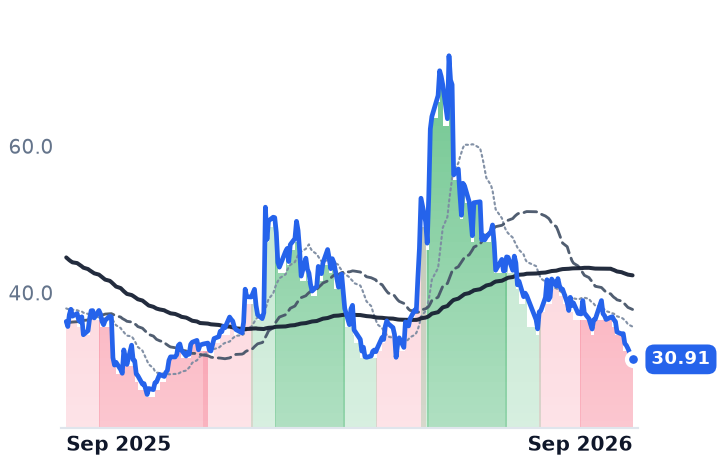
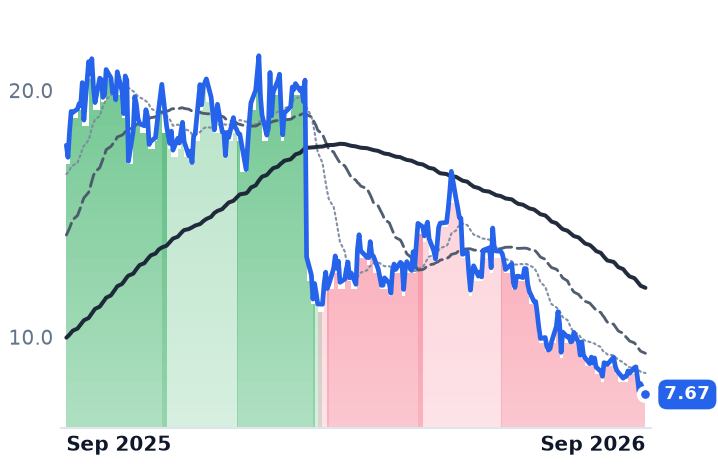
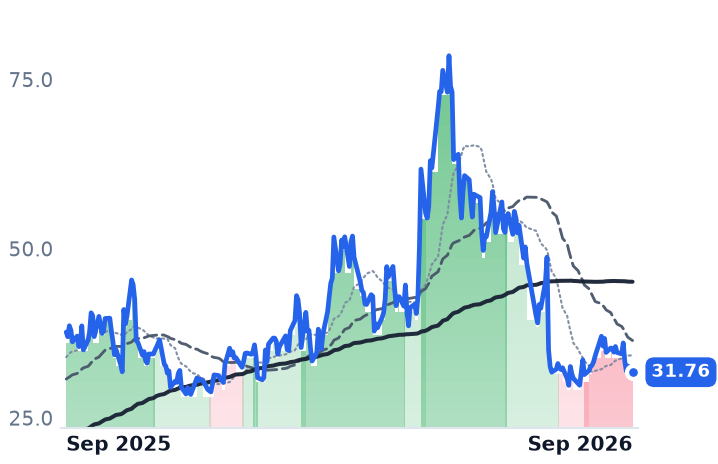
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARRY | $589.2M | n/m | 5.1x | 0.5x | 0.4x | 2.0x | 1.7x | 248.5x | 22.9% |
ENPH | $4.1B | 30.3x | 15.5x | 3.1x | 3.4x | 6.5x | 7.3x | 23.4x | 3.7% |
RUN | $1.8B | 4.5x | 6.1x | 0.5x | 0.6x | 1.5x | 1.7x | 23.0x | -74.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SEDG | $2.2B | n/m | — | 1.7x | 1.7x | 7.6x | 7.6x | n/m | 4.0% |
FSLR | $19.1B | 10.9x | 10.1x | 3.6x | 3.8x | 8.1x | 8.6x | 7.2x | 7.9% |
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ARRY | Revenue | +13.2% | +11.9% | +5.3% |
| EPS | +12.5% | +17.9% | +9.7% | |
ENPH | Revenue | −19.2% | +4.3% | +10.7% |
| EPS | −28.9% | +10.7% | +17.6% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
SEDG | Revenue | +12.0% | +11.1% | +11.4% |
| EPS | −86.2% | −370.0% | +91.7% | |
FSLR | Revenue | −1.7% | +17.1% | +11.7% |
| EPS | +20.3% | +33.1% | +26.2% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Array Technologies, the Albuquerque maker of single-axis trackers that tilt panels across utility-scale solar farms, took $500m of new bookings in the June quarter and raised its full-year outlook on 5 August. Total executed contracts and awarded orders reached $2.5bn at 30 June, up 37% year on year and the largest the company has reported. Trailing book-to-bill ran at 1.5x.
The shares fell 46% over the three months to 28 September, the steepest decline among the six US-listed solar names — worse than Enphase, worse than Sunrun, worse than First Solar. The reason is not in the order book. It is in what sits above the common stock in the capital structure, and in a date in July.
The gate that closed on 4 July
Every one of those six names closed at a local peak on 30 June and fell continuously through the first half of July. That was the week the begin-construction safe-harbour deadline for the 30% clean-electricity investment credit passed: projects underway before 4 July lock the credit with a four-year window to 2030, while anything starting later must be in service by the end of 2027 or risk losing it to permitting and interconnection delay. A statutory gate, rather than a demand signal, synchronised the break across rooftop and utility-scale alike.
Since then the two sides have delivered opposite numbers. Enphase, which sells microinverters through distributors and installers, reported June-quarter revenue down 19.6% and US sell-through down 34% — its third consecutive decline of roughly a fifth. Sunrun, the largest US residential solar financier, added 31% fewer subscribers and booked 44% less net subscriber value per customer, at $9,444, and cut its 2026 cash-generation guidance to $200-375m from $250-450m. Wood Mackenzie and the Solar Energy Industries Association now forecast a 23% contraction in US residential installations this year. Enphase trades at 7.34x forward gross profit against 6.55x trailing — the forward figure sits above the trailing one only because consensus models the gross-profit line shrinking, and both are far below 14.55x in mid-May. Sunrun trades at 0.53x book.
Array's meter moved the other way. June-quarter revenue of $342.1m was 5.6% below last year but 53% above March, gross margin widened to 29.1%, and the raised guidance put 2026 revenue at $1.4-1.5bn with adjusted earnings of $0.68-0.75 a share and adjusted gross margin a point higher than before, at 27-28%. Over "95% of the order book is domestic," chief executive Kevin Hostetler told analysts on the second-quarter call, with half the book now tied to specifications set by developers and utilities rather than contractors. Newer products account for about half the backlog, against 15% two years ago.
What the common actually owns
The company generated $91.9m of operating cash in the first half and ended June with $307.3m of cash, enough to fund the $153m base price for its AWM acquisition. It also carries $670m of convertible notes and a Series A redeemable perpetual preferred with a $498.2m liquidation preference and $106.4m of dividends already accrued. Common equity is minus $202.1m. The market capitalisation is $589m — less than the preferred claim standing in front of it.
That is why the usable anchors here are odd ones. Trailing price-to-earnings and price-to-book are both negative and meaningless; the shares change hands at 5.10x consensus 2026 earnings of $0.75, on a trailing free-cash-flow yield of 22.9%. But that yield is measured against the common alone, and the cash it counts services the notes and accrues to the preferred before any of it belongs to a shareholder.
The verdict
Very little of Array's decline is earned by the tracker business. Orders grew, revenue guidance rose, margin guidance rose with it, and 80% of the book is expected to convert within six quarters. What the price is discounting is the two things the backlog number cannot settle: whether projects safe-harboured before 4 July all reach construction, and how much of the enterprise the common stock is entitled to when they do. On the first question Array has more visibility than the residential names; on the second it has less than almost anything else in the sector.
The order book converts over six quarters. The preferred's dividends accrue in every one of them.