

Aluminum's Midwest Premium Is Back at Century's Guided $1.09; the Smelters Kept Falling
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The tariff spread that turned American smelters profitable collapsed in August on a headline, then quietly recovered — and the shares never followed it back. By 10 September the surcharge US buyers pay for duty-paid metal was assessed at $2,403 a tonne, the exact assumption Century Aluminum used to guide third-quarter profits, yet Alcoa has since lost another tenth of its value and Century nearly as much.
The businesses are not deteriorating. Century's gross margin reached 30.3% in the June quarter against 5.8% a year earlier; Alcoa's revenue rose 31.4% with operating income more than sixfold higher; Kaiser and Constellium, which charge a conversion fee and pass metal cost through, both set records.
What the market is pricing is duration, not demand: consensus already models 2027 earnings per share below 2026 for Alcoa, Kaiser and Constellium — 17.7% lower at Kaiser. Alcoa reports on 15 October.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
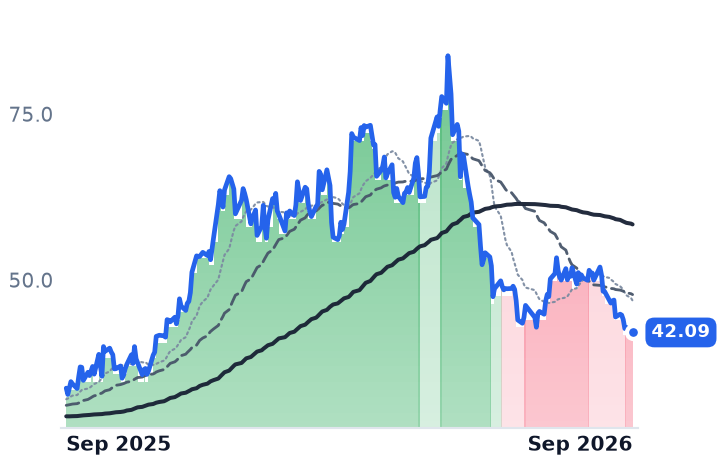
AA | Alcoa | Aluminum | ⚠️ Emerging Bear | −15.7% | +24.9% |
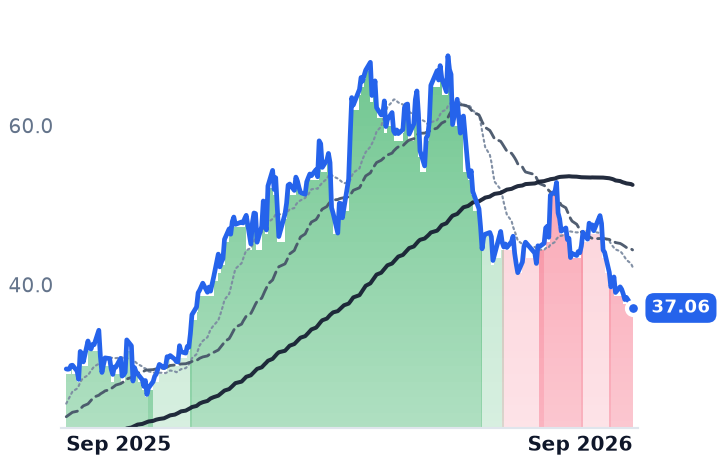
CENX | Century Aluminum | Aluminum | ⚠️ Emerging Bear | −18.9% | +26.1% |
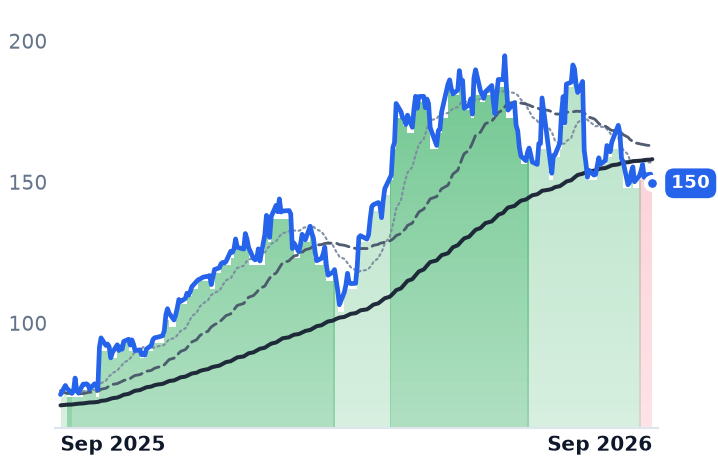
KALU | Kaiser Aluminum | Aluminum | 🟢 Cont. Bull | −5.1% | +100.2% |
| Compared against · context, not the story | |||||
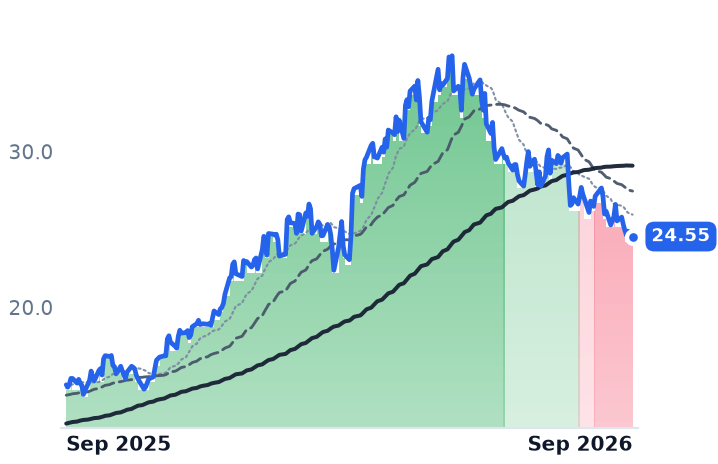
CSTM | Constellium | Aluminum | ⚠️ Emerging Bear | −5.9% | +63.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AA | $11.1B | 8.6x | 6.5x | 0.8x | 0.7x | 4.3x | 4.0x | 6.0x | 3.2% |
CENX | $3.7B | 6.1x | 3.7x | 1.4x | 1.1x | 7.1x | 5.6x | 5.3x | 4.1% |
KALU | $2.4B | 10.7x | 10.6x | 0.6x | 0.5x | 5.1x | 4.4x | 7.3x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CSTM | $3.3B | 6.1x | 6.3x | 0.3x | 0.3x | 2.6x | 2.4x | 4.8x | 6.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AA | Revenue | +17.0% | +2.2% | −4.5% |
| EPS | +82.3% | −6.9% | +7.0% | |
CENX | Revenue | +32.6% | +21.2% | −2.6% |
| EPS | +359.7% | +10.4% | +39.8% | |
KALU | Revenue | +42.9% | −0.1% | +1.3% |
| EPS | +131.2% | −17.7% | +17.5% | |
CSTM | Revenue | +24.3% | +0.5% | −1.4% |
| EPS | +162.1% | −31.8% | +3.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Alcoa's order book for the rest of 2026 is "almost completely sold out," chief financial officer Molly Beerman told the Jefferies Global Industrials Conference on 10 September, and customers in North America and Europe are "actively looking for our supply." On the same day, the surcharge American buyers pay over the London Metal Exchange price for duty-paid aluminum was assessed back at $1.09 a pound, or $2,403 a tonne. In the fortnight that followed, Alcoa shares fell a further 10.2% and Century Aluminum 7.7%.
That gap is the segment's open question going into earnings. Century, a Chicago smelter of primary aluminum in the United States and Iceland, guided third-quarter adjusted earnings before interest, taxes, depreciation and amortization to $325-345m on an assumed Midwest premium of exactly $1.09. The premium is there. Alcoa — the Pittsburgh producer of bauxite, alumina and aluminum, and the segment's first print — reports after the New York close on Thursday 15 October.
The premium round-tripped
The Midwest premium is largely a policy number. Section 232 duties on imported aluminum stand at 50%, widened in April to apply to the full customs value of derivative goods rather than only their metal content. The premium set a record near $1.19 a pound in June. Then reports on 20 August that Washington would halve the duty on Canadian metal took 8.2% out of the September assessment in one session, to 95 cents, with October and November contracts down more than 12%. The talks collapsed two days later, the duty survived, and the premium worked its way back. Beerman's arithmetic for why it holds even under a deal: the United States must import roughly 4 million tonnes of aluminum a year and Canada can supply only 3 million, leaving a million tonnes that still has to be paid to show up.
Three different meters, one tariff
Century is paid the metal price plus that premium on tonnes it smelts domestically. Its June-quarter revenue rose 19.7% to $752.1m and gross margin went from 5.8% a year earlier to 30.3%, a fourth straight expansion. "Today, both plants are producing at full capacity into a market that needs every unit we can produce," chief executive Jesse Gary said on the 6 August call, after the Mt. Holly restart finished in June. Its largest cost is contracted rather than spot: power at Mt. Holly runs through 2031 under Santee Cooper. Management guided $10-15m of summer energy cost and $20-25m of hedge settlements against the September quarter.
For Alcoa the same policy is a bill. It makes about 900,000 tonnes a year in Canada and is paying more than $1bn in Section 232 duties to bring most of it south; its second-quarter 10-Q states that at recent premium pricing, the premium earned on US production covers the tariff cost on the imports. Roughly 35% of 2026 primary shipments price off the duty-paid premium. Revenue grew 31.4% to $3.97bn with operating income of $718m.
The converters are the check. Kaiser Aluminum, which rolls and extrudes mill products for aerospace, automotive and beverage packaging, is paid a conversion fee and passes metal cost through: record conversion revenue of $437m on shipments up 6%, packaging conversion up 34%. Constellium, the Paris-headquartered and Europe-weighted roller, raised full-year guidance to $900-940m of adjusted EBITDA excluding metal-price lag, hitting its 2028 target two years early. Neither reads like weak end demand.
What the discount is actually for
Every name held an uptrend on 2 June, its 50-day average above the 200-day. Alcoa lost that by late August; Kaiser, down only 4.4% over thirty days, broke on 25 September — and much of its August drawdown came the day it named Fred Stephan chief executive from 1 November, succeeding Keith Harvey.
One caution on the longer window. LME aluminum peaked at $3,854 a tonne on 2 June — the same day Alcoa and Century topped — on Gulf smelter outages, then fell after a tentative US-Iran deal and sits near $3,250. The three-month give-back is metal and policy together. Only the last month is policy alone, with cash metal near a two-month high.
Century now trades at 6.1 times trailing and 3.7 times forward earnings, and 5.3 times trailing EV/EBITDA, against a trailing 140 times in early May; Alcoa at 8.6 and 6.5 times, against 16 times then. Kaiser's trailing and forward multiples are both about 10.7, meaning nothing is being paid for consensus 2026 earnings per share of $14.07 against $6.77 reported for 2025.
The verdict the numbers support is narrow: the market is not pricing a demand recession, and it is not pricing a premium collapse either, because the premium came back. It is pricing duration. Consensus itself has 2027 earnings per share below 2026 at Alcoa, Kaiser and Constellium — 17.7% lower at Kaiser — and only Century higher. B. Riley cut Century's target from $86 to $74 in late September. What nothing in the fundamentals explains is the further leg down since the premium recovered; the 18 September session, when all four traded three to four times normal volume with no discoverable company news, looks more like a quarterly rebalance than information.
Century's guide is the cleanest test anyone has printed, and it will not be tested until early November. Alcoa gets there three weeks earlier, with a sold-out book and a billion-dollar duty bill it says the premium already pays.