

Flex Filed to Spin Off Axiom, the Data Center Unit Growing 35% at Double Its Margin
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Contract manufacturers are booking AI server components as revenue at a few points of margin, so gross profit dollars — not the revenue line — say whether the work is being repriced. On that meter the group splits. Flex's gross profit grew 30.6% on 20.6% revenue growth in the June quarter, and Sanmina's doubled on 69.7% growth; Celestica's grew slower than its sales, with gross margin slipping to 12.29%.
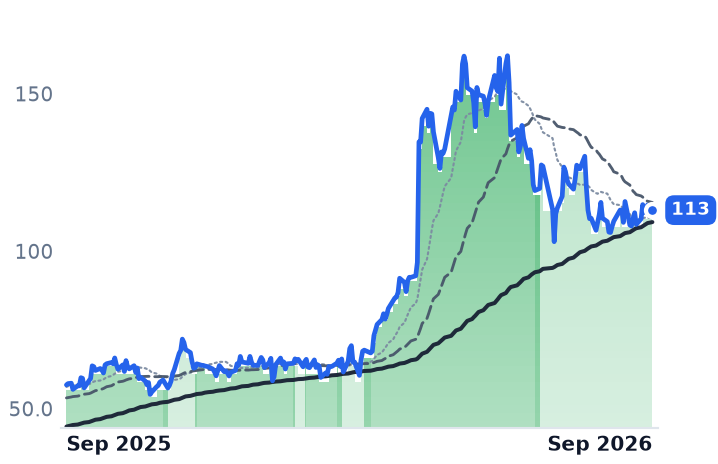
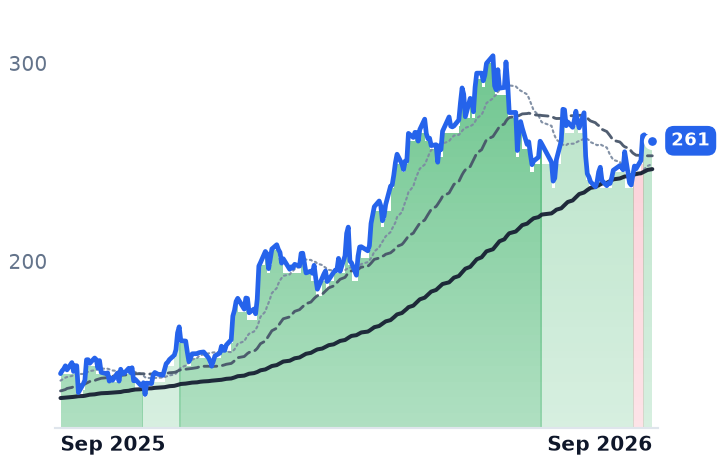
The unresolved part is Flex. Two weeks after it filed a preliminary Form 10 to separate its cloud and power business as Axiom Solutions International, the shares have barely moved while peers rebounded, and the stock sits far below its June high. Its price against trailing gross profit has fallen by roughly a third since mid-May even as that gross profit grew.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +3.3% | +96.4% |
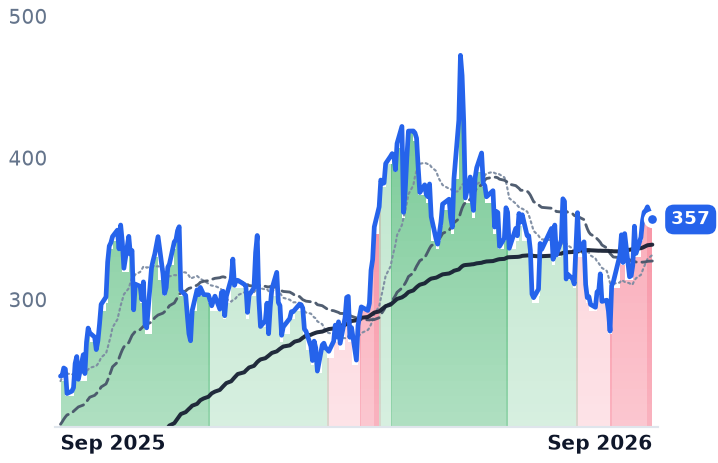
CLS | Celestica | Electronic Manufacturing Services | ⚠️ Emerging Bear | +19.0% | +45.0% |
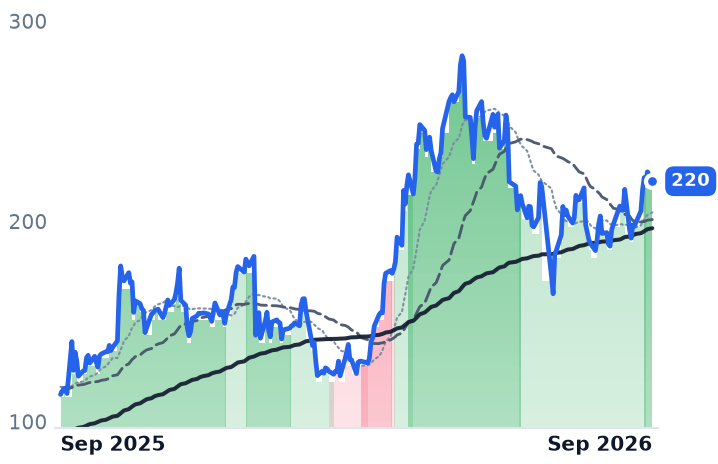
SANM | Sanmina | Electronic Manufacturing Services | 🟢 Cont. Bull | +13.2% | +93.7% |
| Compared against · context, not the story | |||||
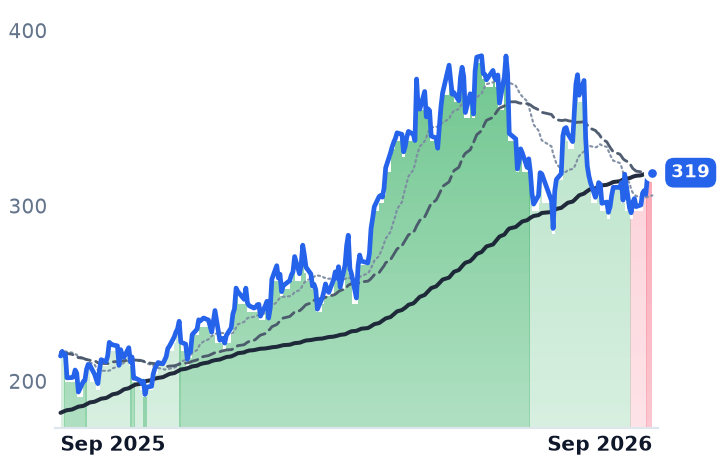
JBL | Jabil | Electronic Manufacturing Services | ⚠️ Emerging Bear | +5.5% | +48.8% |
PLXS | Plexus | Electronic Manufacturing Services | 🟢 Cont. Bull | +9.5% | +82.1% |
BHE | Benchmark Electronics | Electronic Manufacturing Services | 🟢 Cont. Bull | +15.0% | +115.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLEX | $41.8B | 43.6x | 24.0x | 1.4x | 1.2x | 15.0x | 12.7x | 23.6x | 2.6% |
CLS | $41.0B | 36.7x | 32.2x | 2.6x | 2.0x | 22.0x | 16.9x | 27.4x | 1.3% |
SANM | $11.8B | 38.6x | 15.8x | 0.9x | 0.7x | 10.3x | 8.0x | 18.5x | 5.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
JBL | $32.2B | 37.9x | 18.3x | 1.0x | 0.8x | 10.4x | 8.2x | 16.3x | 4.7% |
PLXS | $6.6B | 35.7x | 28.4x | 1.4x | 1.3x | 14.3x | 13.4x | 26.5x | 0.9% |
BHE | $2.6B | 49.1x | 24.6x | 0.9x | 0.9x | 9.0x | 8.5x | 18.0x | 4.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.8% | +50.4% | |
CLS | Revenue | +64.9% | +72.1% | +34.1% |
| EPS | +85.2% | +73.2% | +37.0% | |
SANM | Revenue | +74.9% | +15.8% | +11.8% |
| EPS | +103.4% | +15.2% | +12.7% | |
JBL | Revenue | +20.2% | +21.8% | +13.4% |
| EPS | +35.9% | +31.6% | +21.6% | |
PLXS | Revenue | +21.6% | +14.8% | +7.5% |
| EPS | +21.0% | +16.3% | +10.3% | |
BHE | Revenue | +13.3% | +7.8% | — |
| EPS | +26.7% | +13.0% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
Flex gave its planned data-center spin-off a name on 15 September and filed the paperwork to list it. The business will be called Axiom Solutions International, is expected to trade on Nasdaq under the ticker AXM, and the tax-free separation is targeted for the first quarter of calendar 2027. Flex — a Singapore-founded manufacturing-services group of 149,686 people whose plants turn out switchgear, busway, power-distribution units and liquid cooling alongside cars, medical devices and consumer goods — will be left running the assembly work.
What gets separated is the answer to the question hanging over every contract manufacturer in the artificial-intelligence build-out: whether the work is being repriced, or merely multiplied. A contract manufacturer books the customer's component cost as its own revenue and earns a few points on top. Conventional memory contract prices rose 90-95% quarter on quarter in the first quarter of 2026 and a further 58-63% in the second, and memory's share of a reference server build has climbed from about 18% to roughly 53% of the bill of materials in eighteen months. Revenue growth built out of that inflation arrives at near-zero incremental profit. Gross profit dollars are the honest meter.
The meter reads three different things
Celestica, the Toronto group that designs and builds switches, interconnects and full racks for hyperscale cloud operators, grew June-quarter revenue 62.4% to $4.70bn — the fourth straight quarter of acceleration — while gross profit rose only 55.7%, pulling gross margin to 12.29% from 12.82%. "Celestica delivered very strong performance in the second quarter, achieving revenue of $4.70 billion and adjusted EPS (non-GAAP) of $2.54, each exceeding the high end of our guidance ranges," chief executive Rob Mionis said in the 27 July results release. The dilution is mix: its owned-design Hardware Platform Solutions line reached roughly $1.9bn, up 58%, inside a cloud segment that grew 84% to $3.81bn, so owned design fell from about 58% of that segment to about half. Segment margins still widened, and operating margin hit a record 9.75%. Celestica raised 2026 guidance to $20.5bn of revenue and $11.30 of adjusted earnings, funding the ramp with a $3bn equity sale priced at $310 in August.
Sanmina did the opposite. The San Jose builder of backplanes, enclosures and cable assemblies grew revenue 69.7% to $3.46bn and gross profit 100.7%, widening gross margin to 10.49% from 8.87%. The acquired factories are the reason: inside the segment where the ZT Systems manufacturing business sits — bought from Advanced Micro Devices for $2.55bn in cash plus contingent consideration, with AMD keeping the design engineers — gross margin widened 270 basis points to 10.2%. Cloud and AI infrastructure is now 62% of Sanmina's revenue. The cost shows in cash: free cash flow of $24m on $3.46bn of sales, with inventory up 87.2%. Management told the June-quarter call that an engineering benefit helping margin ramps down after the fourth quarter and that working capital will build further.
Flex's gross profit grew 30.6% on 20.6% revenue growth, and its Cloud and Power Infrastructure unit grew 35% to $2.2bn at a 9.7% operating margin — roughly double the parent's 4.94%. Chief financial officer Kevin Krumm told the fiscal first-quarter call that segment revenues are expected to grow 65% to 75% this fiscal year.
What the rebound paid for
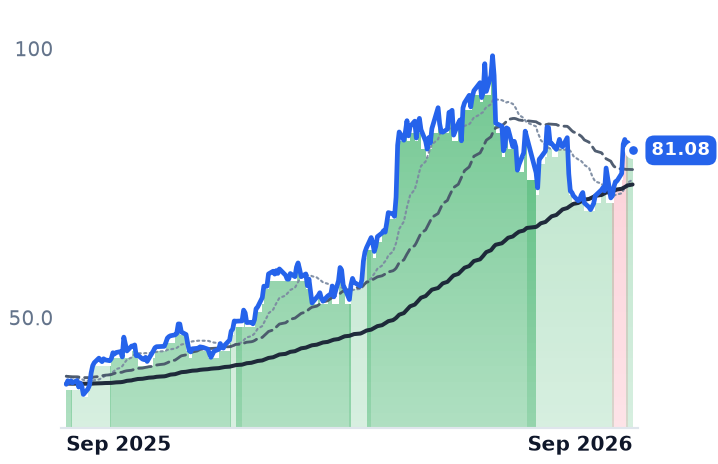
The group has recovered about a tenth over thirty days, but from a hole: on 14 September all six US contract manufacturers fell together between 6% and 9%, with no company news, the day the ten-year Treasury yield breached 5% for the first time since 2023. Celestica gained 19.4% over the month, Sanmina 13.4%, Flex 2.3%. Every one remains below its June high, Flex by 30.3%.
Judged against the gross profit each business actually earns, Celestica costs 21.99x trailing, against 26.26x in mid-May and roughly 22.4x a year ago — its twelve-month gain was earned by growth rather than by a higher multiple. Sanmina costs 10.26x, close to Jabil's 10.37x ahead of Jabil's fiscal fourth quarter on 30 September. Flex costs 15.04x, down from 21.42x in mid-May, while its gross profit grew. Its 24.04x forward earnings sit against 43.64x trailing, with consensus revenue accelerating.
So two of the three are being paid for margin and one for throughput, and the market has inverted that. Sanmina's re-rating is earned at the gross line but financed on the balance sheet. Celestica's operating record is real, while the designed content its premium assumes is shrinking as a share of the work. Flex is the only one where the de-rating has no equivalent in the numbers — the likelier explanation is the shrinking automotive and consumer book dragging on a business whose fastest, richest unit is about to leave it.
That is what the separation ends. Once Axiom lists, power and cooling will carry its own price and assembly will carry its own, and neither can be averaged into the other. Flex has promised the strategy detail at an innovation day in Austin on 10 November.