

Newmark Grew Its Servicing Book 16.8% to a Record $81.2bn as the Ten-Year Hit 5.17%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Newmark is the property brokerage most levered to deals getting done, and it spent the past year building the one asset that pays whether or not they do. Its primary loan-servicing portfolio ended June at a company record, with a 4.8-year weighted-average maturity, and management-and-servicing revenue rose 18%.
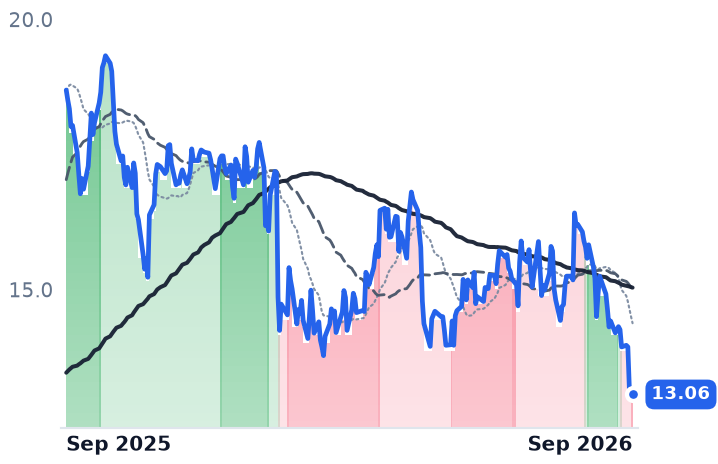
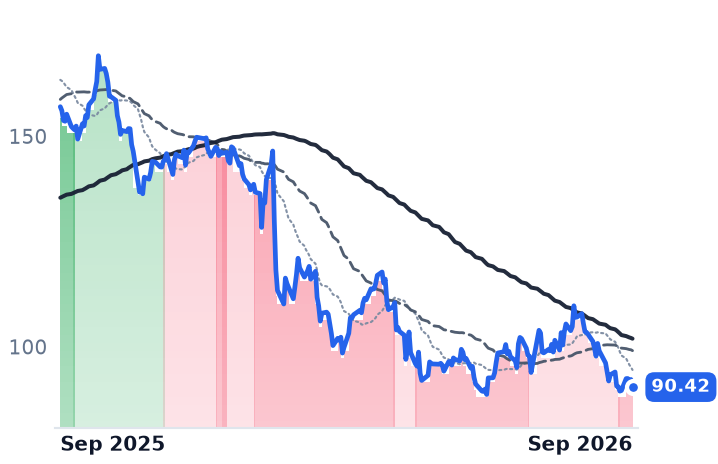
What the disclosure does not show is profit. June-quarter revenue grew 17.0% while operating income fell 5.5% and the operating margin slipped to 4.6% from 5.6%, because producer pay absorbed the whole revenue gain. Newmark is the cheapest of the five listed brokerages on enterprise value to earnings before interest, tax, depreciation and amortization, at 7.9x against CBRE's 17.8x, and sits at a 52-week low with an investment-grade rating three weeks old and no named successor to its chief executive.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
NMRK | Newmark | Commercial Real Estate Services | ⚠️ Emerging Bear | −17.5% | −30.1% |
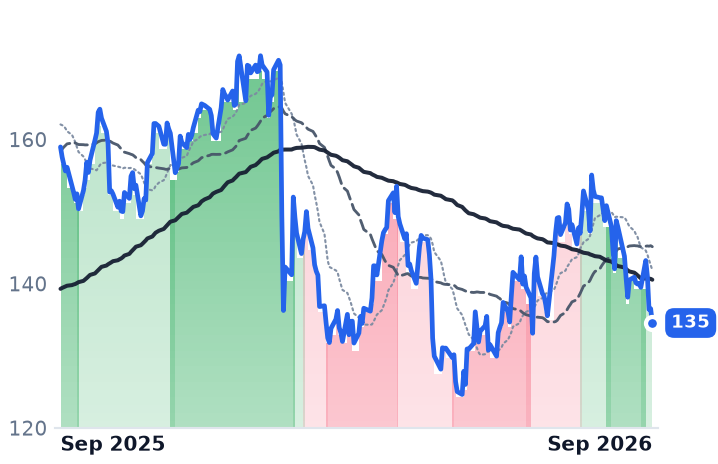
CBRE | CBRE | Commercial Real Estate Services | 🟢 Cont. Bull | −10.8% | −15.4% |
| Compared against · context, not the story | |||||
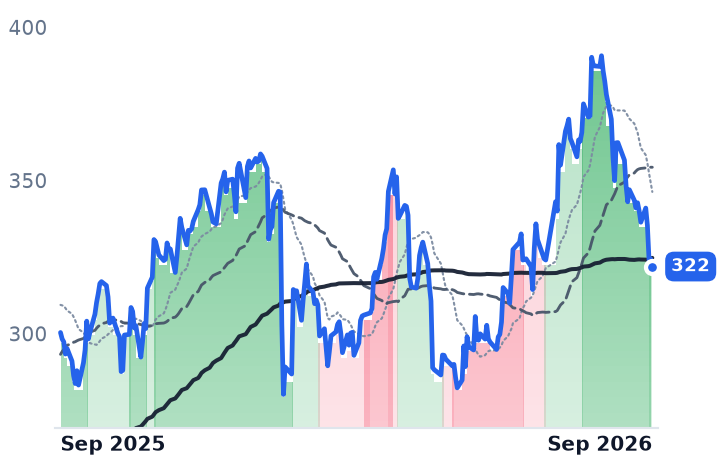
JLL | Jones Lang LaSalle Incorporated | Commercial Real Estate Services | 🟢 Cont. Bull | −14.8% | +7.2% |
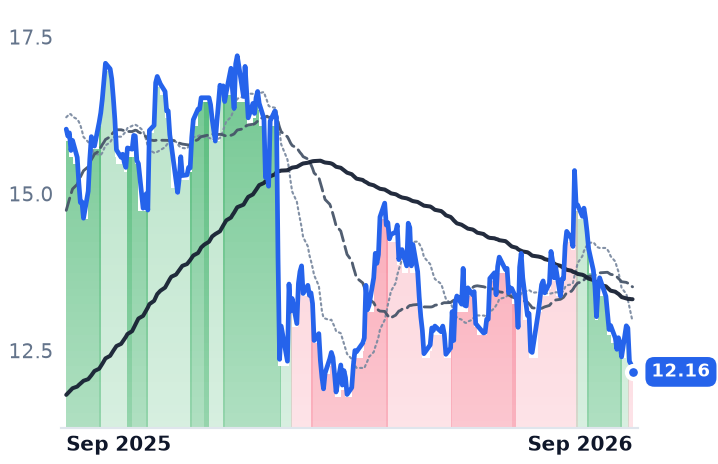
CWK | Cushman & Wakefield | Commercial Real Estate Services | ⚠️ Emerging Bear | −13.9% | −24.1% |
CIGI | Colliers International | Commercial Real Estate Services | 🔴 Cont. Bear | −12.2% | −42.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NMRK | $2.0B | 15.8x | 6.7x | 0.6x | 0.5x | 0.6x | 0.6x | 7.9x | 39.1% |
CBRE | $39.0B | 30.7x | 17.2x | 0.9x | 0.8x | 5.1x | 4.7x | 17.8x | 2.4% |
JLL | $14.9B | 15.2x | 13.0x | 0.5x | 0.5x | 0.6x | 0.6x | 11.1x | 8.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWK | $2.8B | 41.7x | 8.3x | 0.3x | 0.3x | 1.6x | 1.6x | 12.6x | 10.6% |
CIGI | $4.5B | 41.9x | 12.2x | 0.7x | 0.7x | 2.8x | 2.6x | 11.2x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NMRK | Revenue | +16.8% | +9.2% | +8.4% |
| EPS | +22.2% | +13.0% | +9.7% | |
CBRE | Revenue | +15.4% | +11.3% | +9.7% |
| EPS | +23.7% | +14.8% | +13.0% | |
JLL | Revenue | +11.9% | +7.5% | +6.8% |
| EPS | +43.4% | +12.2% | +14.0% | |
CWK | Revenue | +58.6% | +6.5% | +6.1% |
| EPS | +20.5% | +17.4% | +15.4% | |
CIGI | Revenue | +14.2% | +8.6% | +3.0% |
| EPS | +11.2% | +13.5% | +10.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Newmark Group, the New York firm that brokers property sales and leases, originates government-agency multifamily loans and then services them, ended June with a record primary servicing portfolio of $81.2bn, up 16.8% from a year earlier, according to its quarterly filing. That book bills monthly on loans outstanding, whether or not a single building changes hands. Weeks later the long end of the bond market did the thing that stops buildings from changing hands.
Newmark is the cleanest place in commercial real estate services to ask which of those two forces is winning, because it is built deliberately the opposite way from the industry's scale names: capital-markets advisory and agency origination on one side, a servicing asset that marks on rates rather than on deal count on the other. The total servicing and asset-management portfolio stood at $219.3bn, of which Fannie Mae, Freddie Mac and Federal Housing Administration loans are 30.6%, and mortgage servicing rights carried a $514.0m balance after $28.2m of additions in the quarter.
The broken rate assumption
The ten-year Treasury yield closed at 5.17% on 25 September, its highest since June 2007, after a three-session, 23-basis-point selloff — a further leg beyond the 5.04% reading this page cited a week earlier. The consequence for brokerage fees runs through a forecast, not through observed weakness. The Mortgage Bankers Association projected commercial mortgage originations rising 27% to $805.5bn in 2026, multifamily at $399.2bn; that forecast assumed a 4.2% average ten-year yield, roughly 100 basis points below what actually printed. Tenant demand is not the problem: national office net absorption ran a ninth consecutive positive quarter, and first-half absorption of 40.7m sq ft was the strongest first half since 2019, with vacancy at 15.8%.
A servicing book behaves opposite to a brokerage book when yields rise. Higher rates slow expected prepayments, lengthening the life of cash flows carried at fair value and lifting escrow earnings. With 4.8 years of weighted-average maturity on a record portfolio, the same bond move squeezing Newmark's transaction fees should be marking its servicing asset up — an inference from the June disclosure, which Newmark has not quantified for the September quarter.
What the June quarter actually cost
Revenue grew 17.0% to $888.4m, a fourth straight double-digit quarter, with management and servicing up 18% in its fourth consecutive record quarter. Operating income nonetheless fell 5.5% to $40.4m and the margin compressed to 4.55% from 5.63%. Newmark held, rather than raised, its full-year guide of roughly 16% revenue and 19% adjusted earnings-per-share growth, management citing tougher second-half comparisons and uncertain timing on large transactions. S&P Global Ratings then raised the company to investment grade at BBB- on adjusted leverage of 1.2x. Set against that, the succession is open: Newmark said on 7 August that Barry Gosin will step down as chief executive on 31 December 2026 after holding the job since 1979, with a successor expected by year end.
CBRE, the larger rival that ranks first or second globally alongside JLL, spent the drawdown winning contractual work rather than losing it: Fermi disclosed on 24 September that CBRE had been signed as exclusive operations-and-maintenance provider for the first building at Project Matador in the Texas Panhandle, a five-year deal with five-year renewal options. Its contracted revenue grew 15% in the June quarter against 19% transactional, and it raised full-year core earnings guidance to $7.80–$7.90 a share on 29 July, about 23% growth. Nobody has revisited that, for the simple reason that no company in this group has spoken since early August; the next prints land in late October. JLL, which grew June-quarter revenue 10.8% to $6.93bn with operating income up 33% and trades at 13.0x forward earnings, is the only one of the five higher over twelve months, up 7%.
Where the group trades
On trailing enterprise value to operating earnings before depreciation, CBRE at 17.8x is the most expensive of the five, against Cushman & Wakefield at 12.7x, Colliers at 11.2x, JLL at 11.1x and Newmark at 7.9x. Part of CBRE's fall is a premium being taken back from the group's premium name, and its 17.2x forward core earnings against consensus growth near 24% is the anchor that has not moved. Newmark's case is genuinely contested rather than clean: cheapest asset, record recurring book, investment grade — and a margin that went backwards while revenue grew.
The verdict the evidence supports is narrow. Falling transaction volume is a forecast that has been invalidated, not a result that has been reported; what the filings show is recurring revenue compounding and pay costs eating the increment. The de-rating is being applied to the least cyclical parts of both businesses, and for Newmark the rate move that threatens the fee line is the same one that should lengthen the servicing asset.
Which leaves one thing genuinely unhedged. Newmark will be the first of the group to be asked what a 5%-plus long end does to its origination pipeline, and it will be asked by a chief executive who has already announced he is leaving.