

Starboard Told Knife River to Reach 22% Margins by 2029 or Consider a Sale
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
An activist has put a deadline on the smallest listed US aggregates producer, and its complaint is not about the price of crushed stone. Knife River raised mix-adjusted aggregate prices 8% in the June quarter — more than either larger peer — and booked a record $1.2bn backlog, yet operating income fell 7.9%.
Starboard Value's 24 September letter disclosed a stake and demanded a credible path to at least 22% adjusted EBITDA margins by fiscal 2029, or a look at strategic alternatives. Consensus for this year implies roughly 14%.
The same squeeze runs through Vulcan and Martin Marietta: prices up, profit per ton barely moving, diesel and purchase accounting taking the difference. Pricing power is intact. Its conversion into earnings is what broke.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
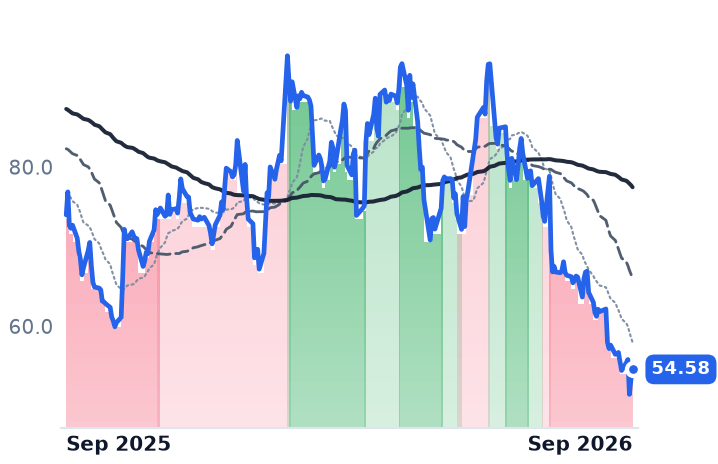
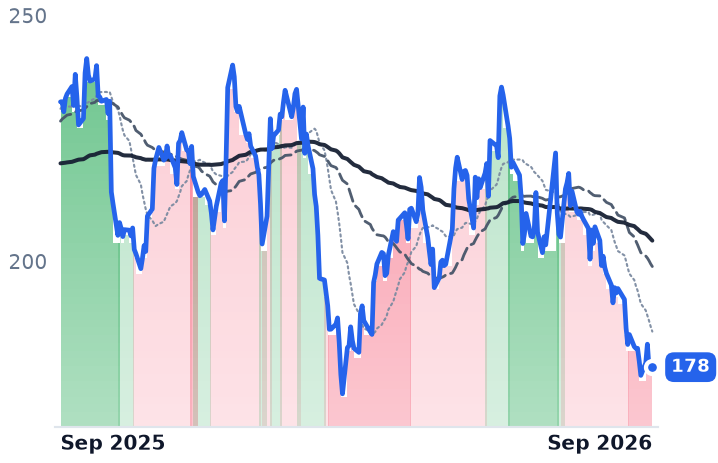
KNF | Knife River | Aggregates & Concrete | 🔴 Cont. Bear | −15.0% | −26.2% |
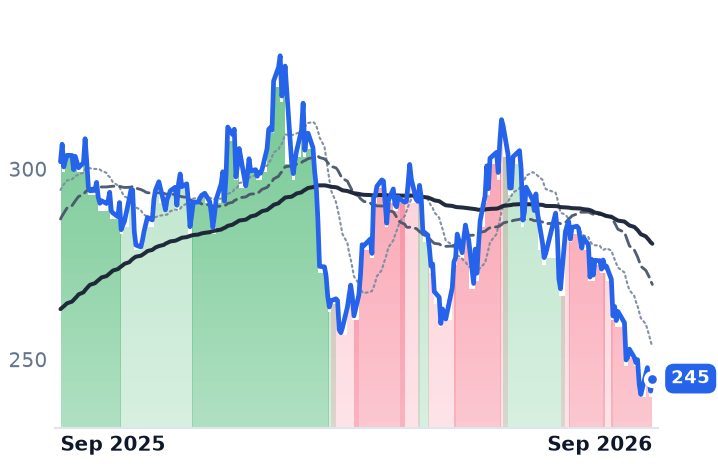
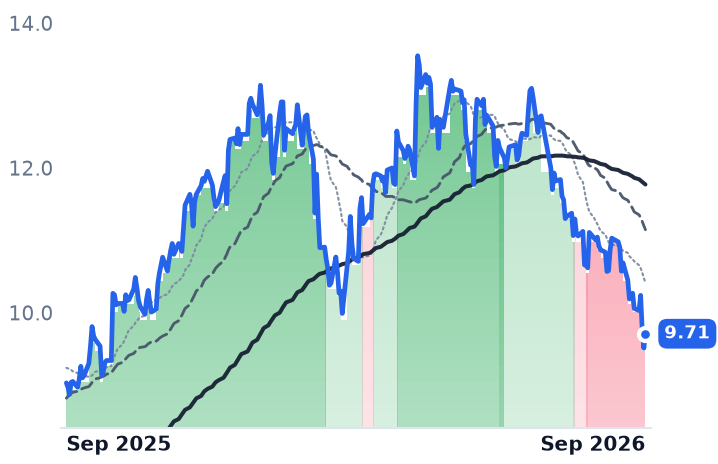
VMC | Vulcan Materials | Aggregates & Concrete | ⚠️ Emerging Bear | −10.8% | −18.9% |
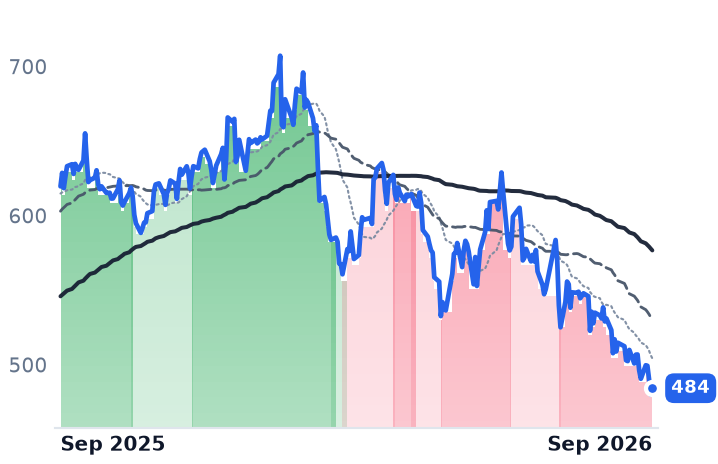
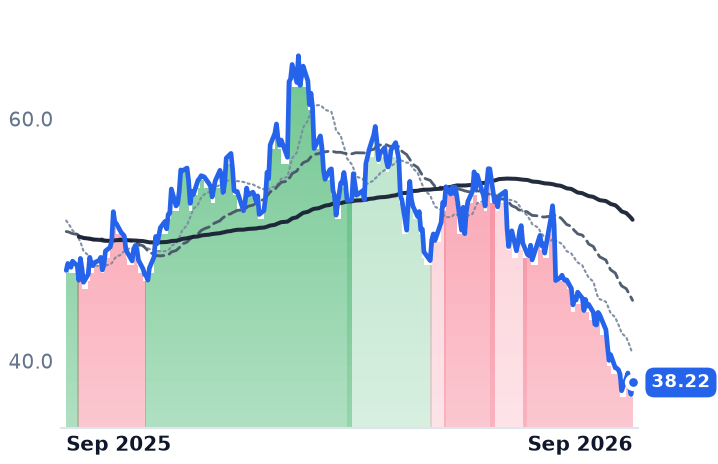
MLM | Martin Marietta Materials | Aggregates & Concrete | 🔴 Cont. Bear | −8.8% | −21.8% |
| Compared against · context, not the story | |||||
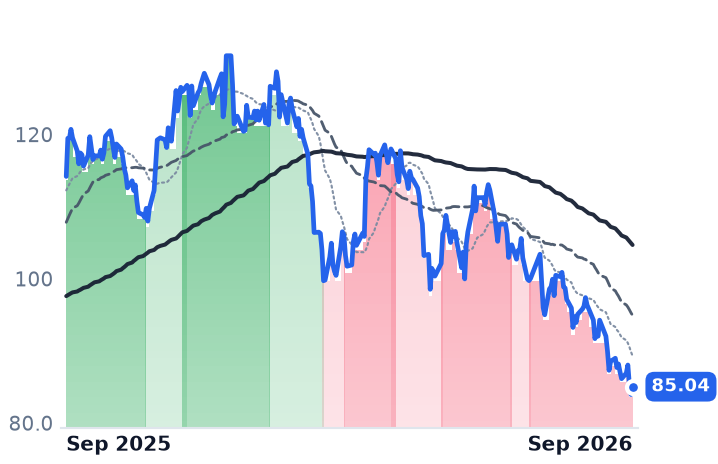
CRH | CRH | Integrated Cement & Materials | 🔴 Cont. Bear | −11.3% | −25.5% |
EXP | Eagle Materials | Specialty Building Products | 🔴 Cont. Bear | −9.7% | −23.2% |
CX | CEMEX, S.A.B. de C.V | Integrated Cement & Materials | ⚠️ Emerging Bear | −10.7% | +7.5% |
AMRZ | Amrize | Regional Building Materials | 🔴 Cont. Bear | −14.4% | −19.5% |
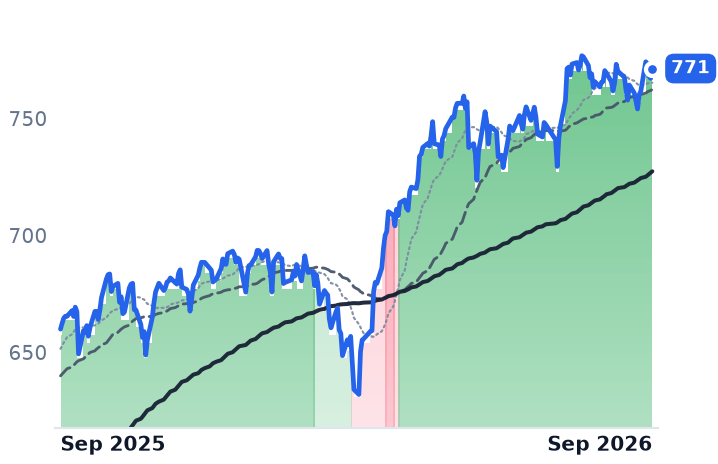
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.3% | +16.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KNF | $3.1B | 22.2x | 19.7x | 0.9x | 0.9x | 5.2x | 5.0x | 10.8x | 1.4% |
VMC | $31.7B | 28.8x | 26.9x | 3.9x | 3.9x | 14.3x | 14.2x | 14.2x | 3.2% |
MLM | $29.1B | 11.9x | 26.8x | 4.3x | 4.0x | 15.4x | 14.2x | 16.8x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRH | $69.0B | 13.7x | 17.3x | 1.2x | 1.7x | 3.5x | 4.9x | 7.9x | 4.2% |
EXP | $6.1B | 14.6x | 15.1x | 2.7x | 2.6x | 9.4x | 9.3x | 9.6x | 3.8% |
CX | $18.2B | 40.6x | 15.6x | 1.1x | 1.1x | 3.4x | 3.2x | 9.5x | 4.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMRZ | $27.1B | — | 17.6x | — | 2.2x | — | — | — | — |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
KNF | Revenue | +10.7% | +4.1% | +4.3% |
| EPS | +6.2% | +18.8% | +10.5% | |
VMC | Revenue | +2.3% | +5.5% | +6.2% |
| EPS | +8.4% | +15.9% | +15.4% | |
MLM | Revenue | +9.0% | +7.0% | +8.9% |
| EPS | −0.4% | +18.1% | +16.9% | |
CRH | Revenue | +5.9% | +5.1% | +6.8% |
| EPS | +6.8% | +12.7% | +12.0% | |
EXP | Revenue | +0.5% | +1.9% | +5.8% |
| EPS | −9.4% | −0.1% | +13.5% | |
CX | Revenue | +7.1% | +4.2% | +2.8% |
| EPS | −12.0% | +13.6% | +17.0% | |
AMRZ | Revenue | +4.9% | +5.7% | +6.1% |
| EPS | +19.4% | +14.3% | +15.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
An activist investor has taken a position in the smallest listed US aggregates producer and given its board a clock. Starboard Value delivered a letter to Knife River's board on 24 September disclosing a stake and calling for a credible plan to reach at least 22% adjusted EBITDA margins by fiscal 2029, through better aggregates pricing and cost reductions — or, failing that, for directors to consider strategic alternatives including a sale. Starboard called the company "an exceptional business in a highly attractive industry" that had "failed to realize its potential," with returns since the 2023 spin-off from MDU Resources it termed "unacceptable."
The demand lands on a company whose problem is not the price of rock. Knife River, which mines aggregates and mixes concrete across the Midwest and Northwest and also bids its own paving, grading and heavy-civil work for state and municipal customers, lifted mix-adjusted aggregate pricing 8% in the June quarter — more than either larger peer — grew contracting revenue 20% and carried a record $1.2bn backlog at 30 June. Revenue rose 12.6% to $938.6m. Operating income fell 7.9%. The company blamed energy costs, delayed projects and the timing and type of contracting work, raised its 2026 revenue guide to $3.4bn–$3.6bn, and cut expected full-year aggregates margin expansion from two percentage points to about one.
Price lands, profit doesn't
That gap between the top line and the profit line is the segment's condition, not one company's. Vulcan Materials, the largest US aggregates producer, raised freight-adjusted mix-adjusted prices 5% in the same quarter and converted it into cash gross profit of $12.02 a ton against $11.88 — fourteen cents — with almost $40m of energy inflation absorbing the rest. "Price is our biggest lever when it comes to overcoming headwinds like this and inflationary pressures," chief executive Ronnie Pruitt told analysts on Vulcan's late-July call. Martin Marietta, whose quarries and cement plants concentrate in the Sun Belt, shipped 61.6m tons, up 2.3% organically, raised organic mix-adjusted price 4%, and reported gross profit per ton down 17% to $6.78 — of which $0.84 was the charge for selling acquired inventory written up to fair value. Revenue grew 7.5%; operating income fell 17.2%. Neither company cut guidance: Martin Marietta raised its revenue range and reaffirmed $2.36bn–$2.5bn of adjusted EBITDA.
The volume question sits in 2027. Federal highway funding was extended only to 11 December 2026, and the enacting resolution cut transportation funding 25% in total. Wells Fargo cut Vulcan to Underweight in early September on slowing construction and constrained state budgets while upgrading Martin Marietta, a split verdict inside one industry.
What the discount pays for
Knife River trades at 10.8x trailing enterprise value to EBITDA against Vulcan's 14.2x and Martin Marietta's 16.8x, and at 19.7x forward earnings — cheaper than both larger peers on every measure recorded here. Vulcan's price-to-gross-profit has compressed about 20% since early May, when it stood at 17.7x, while its gross profit grew. Martin Marietta's reported multiples flatter it: the $13.5bn Lhoist lime combination closed on 21 August issued 10.95m shares, roughly 18% dilution, alongside $5.5bn of notes priced between 4.85% and 6.375%.
Shares tell the sequence. Knife River is down 41% in three months and closed at $51.43 on 23 September before recovering to $54.58 after the Starboard news; Martin Marietta and Vulcan are each off roughly a fifth over the same span, with Vulcan trading below Wells Fargo's own bearish $254 target.
So the compounder story is only half broken. Annual price increases on quarries nobody can permit a competitor into still work — all three proved it in the same quarter. What has stopped working is the translation into EBITDA, and Starboard's wager is that at Knife River the failure is self-inflicted rather than cyclical, fixable with cost discipline whatever Congress does about highways. If it is right, the segment's problem is management. If it is wrong, eight points of margin is a very long way to ask a diesel bill to travel.