

Amphastar's BAQSIMI Sales Fell 3% With No Generic Rival on the Market
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Amphastar sells the only intranasal glucagon in the United States and still got paid less for it. June-quarter net sales of the product came in at $45.5m, down 3% year on year, with no generic approved — the discount came from rebates to buyers rather than from a competitor.
That is the complex-generic premise failing its own test. Gross margin has slid from 54.5% in 2023 to 49.5% in 2025, and this year's recovery to 50.8% in the June quarter rests on three brand-new launches rather than on durable exclusivity. A July warning letter at the company's own California plant adds $2m to $3m of expense a quarter, and a $100m milestone payment to Eli Lilly falls due in the third quarter. The shares jumped 22.1% in a month with no discoverable company news behind it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AMPH | Amphastar Pharmaceuticals | Generic & API Manufacturers | 🟢 Cont. Bull | +18.7% | −2.9% |
TEVA | Teva Pharmaceutical Industries | Generic & API Manufacturers | 🟢 Cont. Bull | +7.5% | +104.3% |
VTRS | Viatris | Generic & API Manufacturers | 🟢 Cont. Bull | +9.1% | +89.1% |
| Compared against · context, not the story | |||||
AMRX | Amneal Pharmaceuticals | Generic & API Manufacturers | 🟢 Cont. Bull | +12.7% | +100.3% |
ANIP | ANI Pharmaceuticals | Generic & API Manufacturers | 🔴 Cont. Bear | +1.6% | −19.5% |
RDY | Dr. Reddy's Laboratories | Generic & API Manufacturers | 🔴 Cont. Bear | +0.6% | −12.3% |
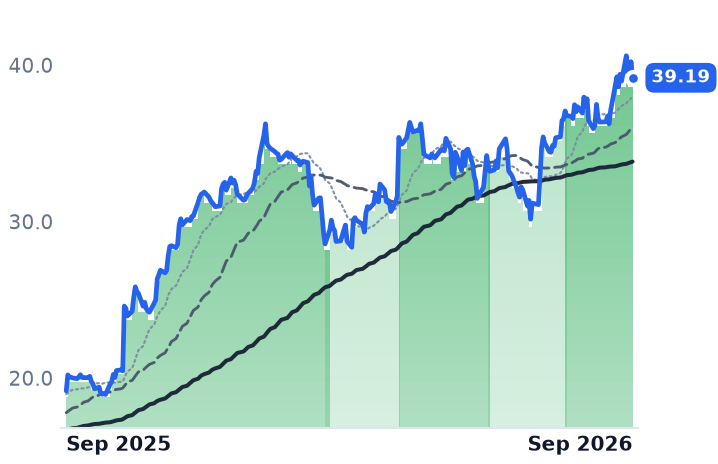
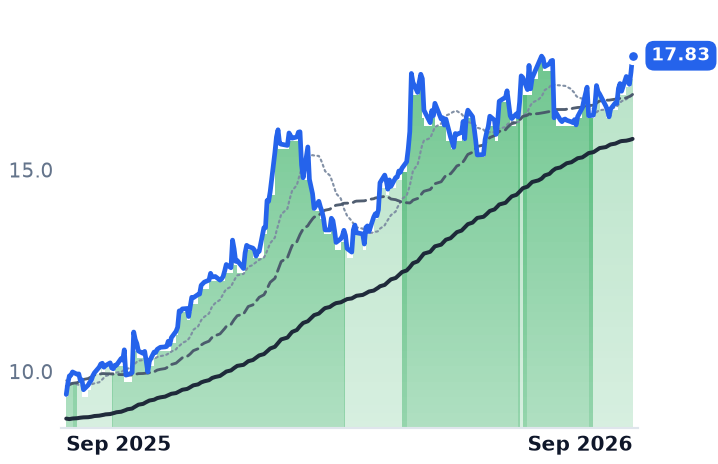
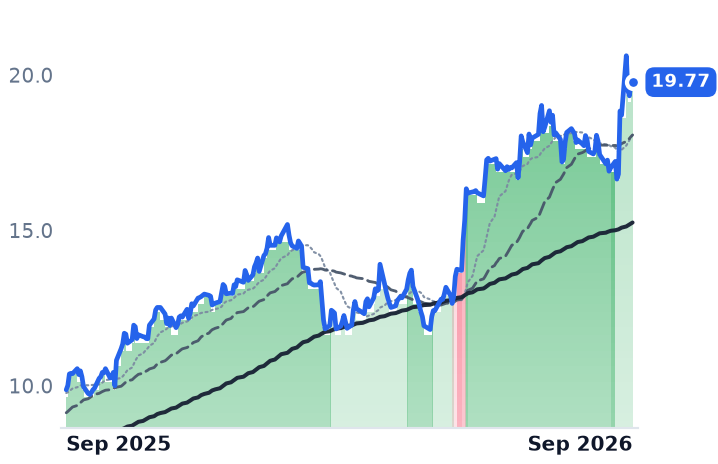
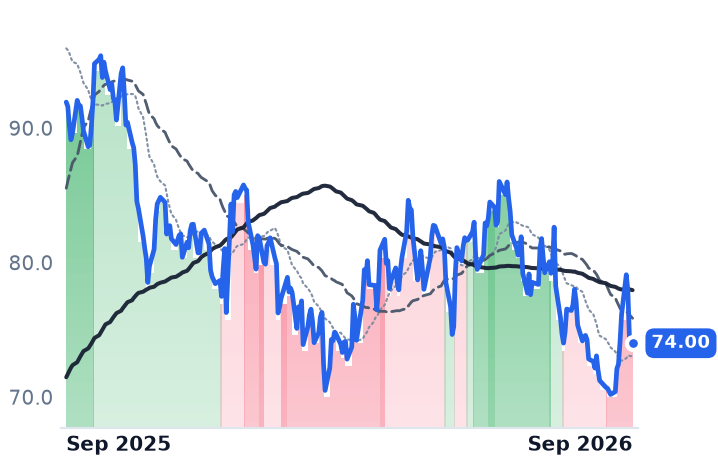
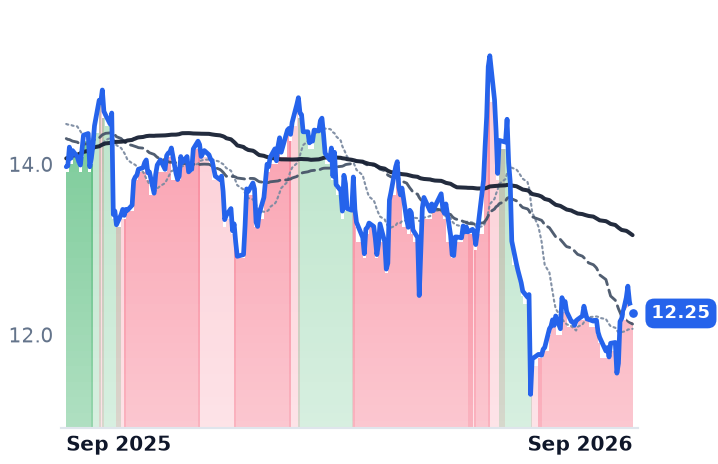
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMPH | $1.2B | 15.0x | 8.8x | 1.6x | 1.5x | 3.3x | 3.2x | 9.3x | 13.3% |
TEVA | $45.6B | 62.9x | 19.7x | 2.7x | 2.8x | 5.1x | 5.3x | 19.2x | 5.2% |
VTRS | $20.8B | n/m | 7.1x | 1.4x | 1.4x | 4.0x | 4.0x | 12.7x | 9.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMRX | $6.2B | 38.9x | 19.0x | 2.0x | 2.0x | 5.0x | 5.0x | 13.5x | 1.3% |
ANIP | $1.7B | 15.4x | 8.0x | 1.7x | 1.5x | 2.7x | 2.4x | 6.5x | 9.4% |
RDY | $10.3B | 30.3x | — | 3.0x | — | 6.0x | — | 15.9x | 1.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AMPH | Revenue | +3.1% | +4.9% | +3.0% |
| EPS | −13.6% | +7.1% | +6.3% | |
TEVA | Revenue | −1.2% | +4.6% | +4.5% |
| EPS | −23.8% | +53.8% | +11.8% | |
VTRS | Revenue | +4.7% | +1.7% | +3.1% |
| EPS | +8.7% | +6.4% | +7.3% | |
AMRX | Revenue | +4.7% | +9.0% | +10.9% |
| EPS | +27.4% | +17.3% | +21.4% | |
ANIP | Revenue | +27.1% | +11.5% | +8.4% |
| EPS | +23.2% | +12.9% | +14.2% | |
RDY | Revenue | +7.4% | +1.4% | +11.7% |
| EPS | −10.9% | −28.8% | +32.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A price cut with no competitor
Amphastar Pharmaceuticals, the Rancho Cucamonga maker of generic and proprietary injectables, inhalation and intranasal medicines, sells the only intranasal glucagon rescue treatment on the US market. In the June quarter it collected less for it than a year earlier: BAQSIMI net sales of $45.5m, down 3%. No generic version has been approved. The price came down through rebates and discounts.
The complex-generic argument rests on manufacturing difficulty — build something few rivals can replicate and the price holds. BAQSIMI shows the buyer can take the price anyway, and that matters because Amphastar's margin has been going one direction for three years: 54.5% gross margin in 2023, 51.1% in 2024, 49.5% in 2025. Operating income fell 31.7% last year to $140.4m and diluted earnings went from $3.06 a share to $2.03.
Margin that has to be re-bought each year
The March quarter was the trough, at a 41.1% gross margin against 50.0% a year earlier on flat revenue. June recovered to 50.8% on revenue of $183.9m, up 5.4% — and the company located that recovery in recently launched ipratropium bromide, teriparatide and iron sucrose, partly offset by lower average selling prices on BAQSIMI, glucagon and epinephrine multidose vials. Operating income still fell 5.8%. Meanwhile the legacy glucagon emergency kit, which BAQSIMI replaces, fell 45% to $14.1m in the December 2025 quarter.
Two bills land on top. On 2 July the Food and Drug Administration sent Amphastar's IMS subsidiary a warning letter over manufacturing-practice violations at South El Monte, California, following a December inspection; distribution was not restricted, but remediation adds $2m to $3m of expense a quarter for several quarters. And BAQSIMI's own success triggered a $100m milestone payment owed to Eli Lilly in the third quarter, for clearing $175m of annual net sales.
The reshoring option nobody is paying for
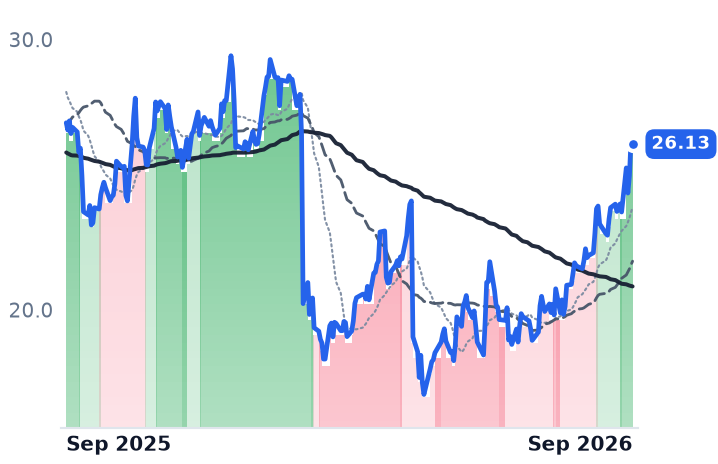
Amphastar is, on paper, the cleanest domestic beneficiary of US trade policy: all finished products are made in the United States, and in July 2025 it announced a plan to quadruple capacity at Rancho Cucamonga. Imported generics face zero tariffs until August 2028, then 100%, then 200% a year later, while India supplies close to half of American generic medicines. "Patients pay the tariff," Sandoz chief executive Richard Saynor said on 8 September. Amphastar still imports active ingredients and starting materials, so the hedge is partial — and over twelve months the shares fell 2.7% regardless.
That decline did rational work. Consensus has 2026 earnings at $2.97 a share, down 13.6% from the $3.44 that stood for 2025, leaving the stock at 8.8x forward earnings against 15.0x trailing, with a 13.3% trailing free-cash-flow yield — the highest of the generic makers. Diluted share count has fallen 15% since late 2024, to 44.2m, so the reported earnings decline understates the drop in absolute profit.
What the past month does not explain is the rally: up 22.1%, including 11.2% across four sessions into 24 September, with no company announcement discoverable. Barclays lifted its price target to $23 from $20 while keeping an Equal Weight rating — a target below the $26.13 close. Management reaffirmed mid- to high-single-digit sales growth for 2026.
The business earns the cheap multiple and the cash yield; it does not yet earn the month. A margin that must be repurchased with fresh approvals every year is a different asset from one protected by manufacturing barriers, and BAQSIMI is the proof — the price fell while the barrier held.
The $100m check to Lilly clears this quarter, paid on a product already being discounted with no competitor anywhere in sight.