

Winter Gas Hit a Year Low; EQT, Antero and Expand Lost a Fifth or More Since March
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
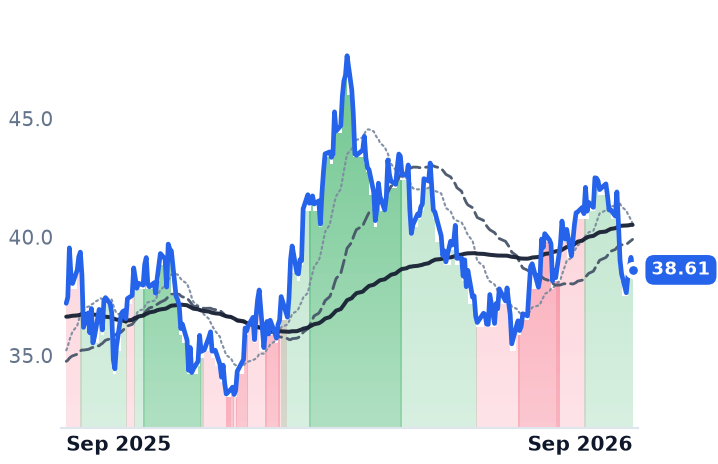
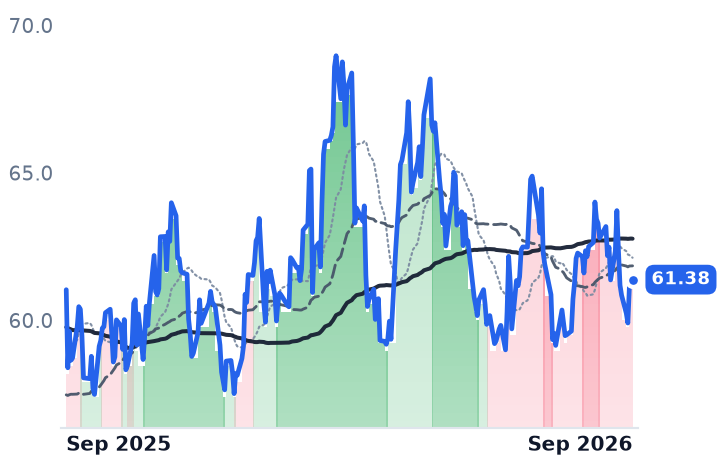
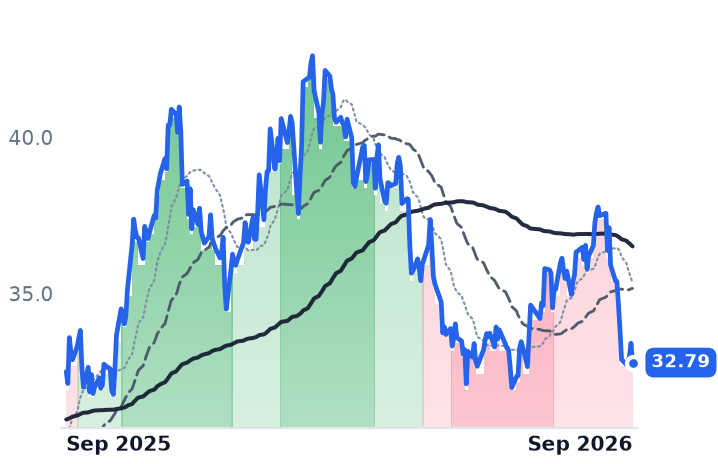
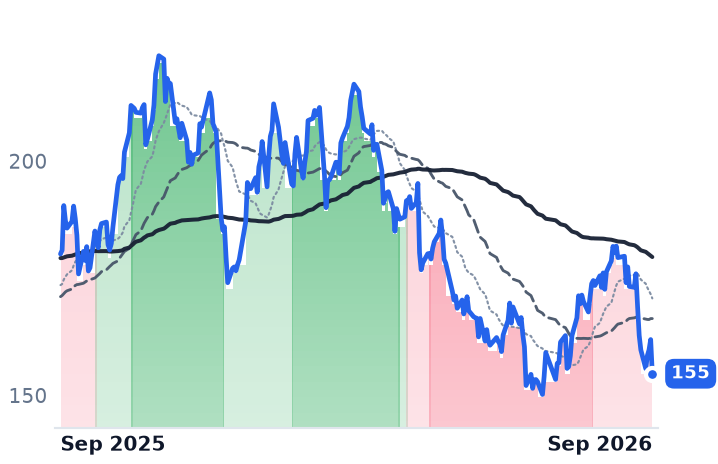
Natural gas rose 9.7% in the ten sessions to 25 September and the producers that sell it fell — Antero hardest, down 9.9%. The equity is not paid on the prompt month; it discounts next winter's strip, which touched its lowest of the year in early September on record output and a forecast 3,985 Bcf of gas in storage at the end of October.
Earnings expectations barely moved through the slide: EQT's 2026 consensus slipped to $4.07 a share while the stock fell 7.9%. The businesses split. Antero grew June-quarter revenue 11% on record production and raised guidance; EQT's revenue fell 29% and Expand's 20% as the strip took their realizations, even with volumes above guidance and unit costs down.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
EQT | EQT | Appalachian Shale Gas | 🔴 Cont. Bear | −6.9% | −6.2% |
AR | Antero Resources | Appalachian Shale Gas | 🟢 Cont. Bull | −9.0% | +4.3% |
EXE | Expand Energy | Appalachian Shale Gas | 🔴 Cont. Bear | −11.5% | −17.4% |
| Compared against · context, not the story | |||||
CRK | Comstock Resources | Diversified Onshore & Conventional | 🔴 Cont. Bear | −8.2% | −35.2% |
RRC | Range Resources | Appalachian Shale Gas | 🟢 Cont. Bull | −6.9% | +3.8% |
TOU.TO | Tourmaline Oil | Oil & Gas Exploration & Production | 🔴 Cont. Bear | −1.8% | +0.6% |
CNX | CNX Resources | Appalachian Shale Gas | 🔴 Cont. Bear | −9.4% | +0.9% |
GPOR | Gulfport Energy | Appalachian Shale Gas | 🔴 Cont. Bear | −12.3% | −14.2% |
NG=F | NG=F | — | 🔴 Cont. Bear | +11.7% | −1.3% |
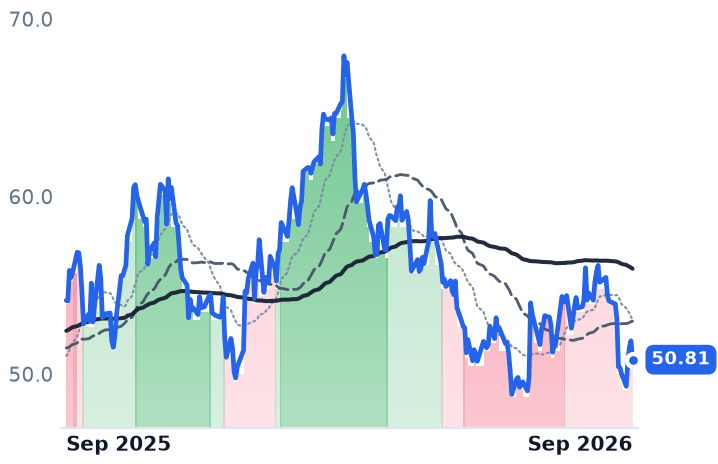
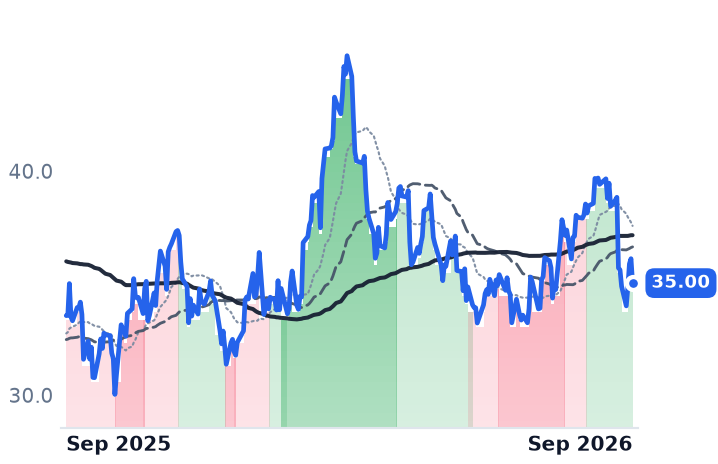
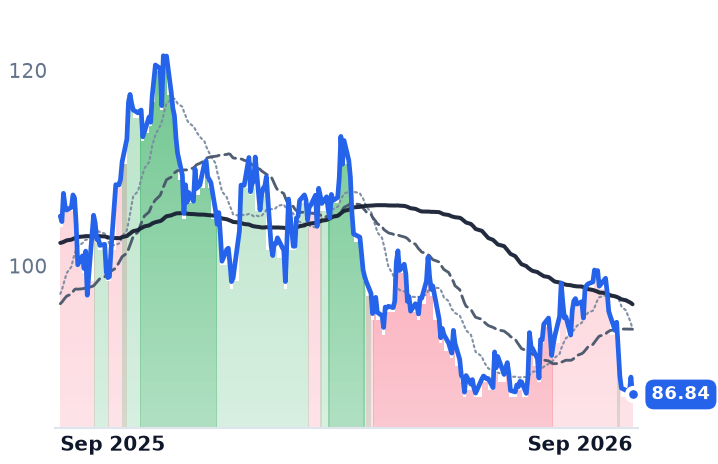
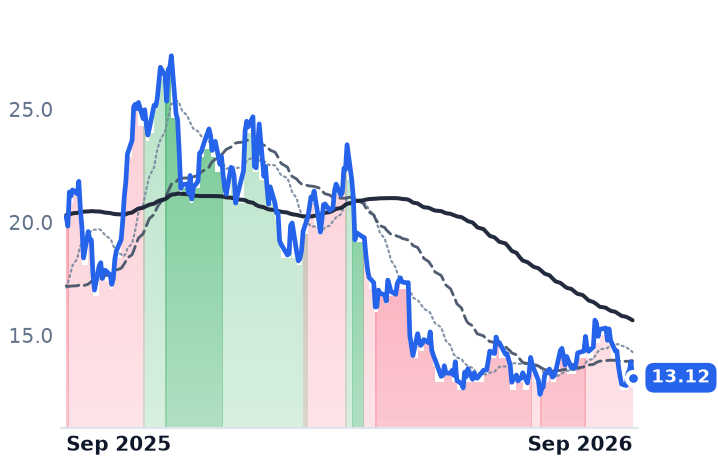
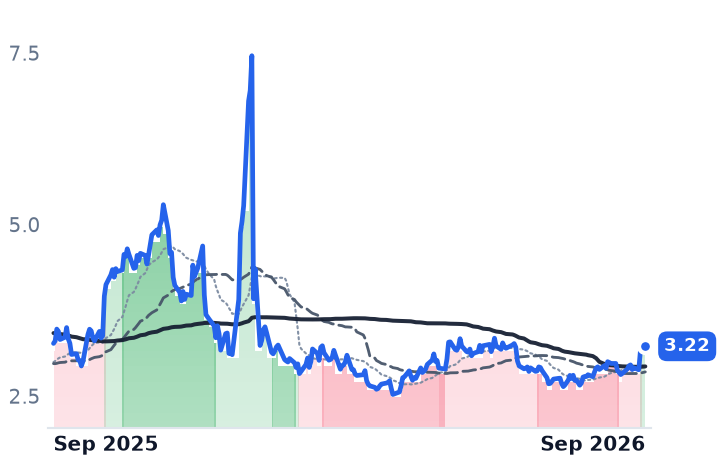
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQT | $31.8B | 11.2x | 12.5x | 3.4x | 3.4x | 5.0x | 5.0x | 6.0x | 11.9% |
AR | $10.8B | 10.0x | 8.2x | 1.9x | 1.6x | 7.4x | 6.2x | 6.4x | 13.1% |
EXE | $20.1B | 7.4x | 10.1x | 1.5x | 1.5x | 2.4x | 2.4x | 3.5x | 12.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRK | $3.9B | 7.6x | 32.0x | 2.1x | 2.0x | 3.1x | 3.0x | 5.2x | -18.7% |
RRC | $9.8B | 11.5x | 10.3x | 3.0x | 2.8x | 6.2x | 5.8x | 7.6x | 12.0% |
TOU.TO | $23.0B | 61.0x | 13.1x | 4.0x | 3.4x | 75.6x | 65.7x | 6.7x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNX | $5.3B | 5.2x | 11.5x | 2.2x | 2.2x | 4.5x | 4.5x | 4.1x | 9.9% |
GPOR | $3.1B | 6.9x | 7.4x | 2.1x | 2.0x | 3.5x | 3.4x | 4.3x | 8.0% |
NG=F | — | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EQT | Revenue | +10.3% | −0.6% | +11.7% |
| EPS | +38.1% | −4.9% | +38.3% | |
AR | Revenue | +31.0% | −0.1% | +8.3% |
| EPS | +135.1% | +3.9% | +26.9% | |
EXE | Revenue | +14.7% | −4.1% | +6.9% |
| EPS | +43.3% | −1.6% | +24.1% | |
CRK | Revenue | +2.5% | +16.5% | +12.5% |
| EPS | −20.6% | +71.4% | +79.2% | |
RRC | Revenue | +17.7% | +2.5% | +8.1% |
| EPS | +40.2% | −4.7% | +21.6% | |
TOU.TO | Revenue | +10.2% | +8.9% | −1.3% |
| EPS | +44.6% | +7.4% | +6.3% | |
CNX | Revenue | +16.2% | −8.8% | +7.1% |
| EPS | +42.9% | +31.7% | +23.1% | |
GPOR | Revenue | +10.7% | +1.2% | +5.4% |
| EPS | +8.7% | +18.6% | +31.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A rally the wellhead did not get
On 24 September TC Energy's Columbia Gas Transmission declared force majeure on the Mountaineer XPress system after a leak at a West Virginia regulator station, cutting as much as 1.8 Bcf/d of firm service on a line built to carry 2.7 Bcf/d of Appalachian gas out of the basin. Henry Hub futures posted their biggest single-day gain since January. The producers stranded behind the blockage did not rally with it — an outage on takeaway lifts the national benchmark and worsens the price at the wellhead at the same time, a pattern S&P Global recorded on an earlier Mountaineer failure.
The whole month ran that way. Between 15 and 25 September the front-month contract rose 9.7% to $3.225 per million British thermal units while EQT fell 4.3%, Expand Energy 7.8% and Antero Resources 9.9%. These shares are not valued on the prompt; they are valued on next winter, and the winter 2026/27 strip hit its lowest of the year in early September on a strong El Niño and stout supply. In August the Energy Information Administration had already cut its 2026 Henry Hub forecast more than 6% to $3.44, citing record production and a projected 3,985 Bcf in storage at the end of October.
The drawdown is six months old, not four quarters. EQT, Expand and Comstock Resources peaked on 25 March, Antero and Range Resources on 27 March; from those highs EQT is down 25.2%, Expand 23.8% and Antero 22.5%, though Antero and Range remain slightly higher than a year ago. A third of the September decline came in four sessions from 16 to 21 September, and 16 September was a broad energy sell-off — the XLE energy fund fell 1.9% and West Texas crude 3.2% while gas itself fell 1%. Tourmaline Oil, the Canadian producer selling into AECO rather than a US hub, lost 1.3% over the month. The problem has a postcode.
One curve, three different businesses
Antero, the Denver producer whose roughly 502,000 net Appalachian acres yield an unusually wet barrel of ethane, propane and heavier liquids, is having its best year. June-quarter revenue rose 11.1% to $1.34bn and net income 78% to $279m on record output above 4.1 Bcfe/d, up 21%, with full-year guidance raised to 4.15–4.2 Bcfe/d. Its C3+ liquids barrel realized $44.33, the highest since 2022, and it carries no liquids hedges. "Ten to 15 years back, we signed up for all the firm transport arrangements just to get our gas out. Now we're at the end of that. We can select the best paths," chief executive Michael Kennedy told investors on the second-quarter call. It trades at 8.22x forward earnings against 9.97x trailing — the only one of the three the market prices for growth — on a 13.1% trailing free-cash-flow yield.
EQT, the Pittsburgh gas extractor that owns its gathering system and a stake in Mountain Valley Pipeline, shows the strip in its accounts: revenue down 29.2% to $1.81bn and operating margin down to 25.1% from 44.3%. Operationally it improved — 634 Bcfe sold above the top of guidance, unit operating costs of $1.03 per Mcfe against $1.08, and net debt cut to $5.5bn from $7.7bn against a $5bn target. It is also the most expensive of the three, at 12.49x forward earnings against 11.16x trailing, and the least protected: roughly 35% of local basis hedged against a historical norm near 90%. "I don't see a way for basis not to continue to strengthen materially," chief financial officer Jeremy Knop said on the 22 July call.
Expand, the former Chesapeake and the largest US gas producer, straddles both problems: about 7.48 Bcfe/d, 42.6% of it Haynesville gas next to the Gulf Coast liquefaction trains. Revenue fell 19.7%, realized gas came in at $2.42 per Mcf, and 66% of 2026 volumes and 41% of 2027 are already hedged — protection on the way down and a ceiling on any recovery. It has retired $850m of stock this year and cut net debt to $3.1bn, trades at 3.48x trailing enterprise value to EBITDA against EQT's 6.02x and Antero's 6.44x, and has had no permanent chief executive since February.
What the fall earns
Part of this is earned. EQT's and Expand's reported revenue and margins genuinely fell with the gas price, and a market that paid a scarcity premium for gas in March is taking some of it back. But the forward numbers did not follow the shares down: consensus 2027 EBITDA for the three is flat to 5% lower than 2026, and through the exact window of the September slide EQT's 2026 estimate moved from $4.14 to $4.07 against a 7.9% share fall while Antero's held near $4.26 against an 8.9% one. At Antero, where revenue, volumes and guidance all rose, nothing in the reported business explains a fifth off the price. The mechanism is a curve, and the curve is not the company.
The tightness these shares were bought for is dated. The same EIA outlook that cut this year's price has supply outrunning demand by 0.5 Bcf/d in 2026 and falling 1.6 Bcf/d behind it in 2027 as liquefaction demand arrives. EQT's ten-year supply contract to a West Virginia power plant and Expand's Delfin cargoes both begin delivering around 2031. Owning the gas is the easy part; being paid for it requires holding the position until the buyers turn up.