

Alignment Named Hospital Billing and $10–11m of Extra Spending, Then Held 2026 Guidance
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two insurers running the same capitated Medicare Advantage book were priced within a whisker of each other seventeen sessions ago. They are now 63% apart on the same measure, and only one of them disclosed anything.
At Baird's Global Healthcare Conference on 15 September, Alignment Healthcare's management flagged third-quarter cost pressure from aggressive hospital billing, disputes and appeals, plus unplanned second-half spending — while leaving full-year guidance alone. The June quarter it is being repriced away from showed revenue up 31.6% to $1.34bn and an adjusted medical benefit ratio of 86.3%, about 0.4 points better than a year earlier.
An industry-wide cost shock does not fit: UnitedHealth Group says its 2026 Medicare cost trend is running below its own initial estimate of roughly 10%, and Clover Health's benefits expense ratio improved. What the decline buys is a claims-timing problem, a legal overhang and a star-ratings print due within days.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
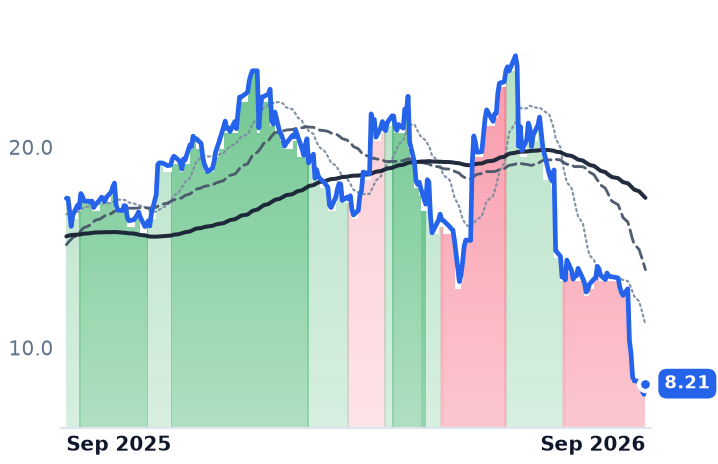
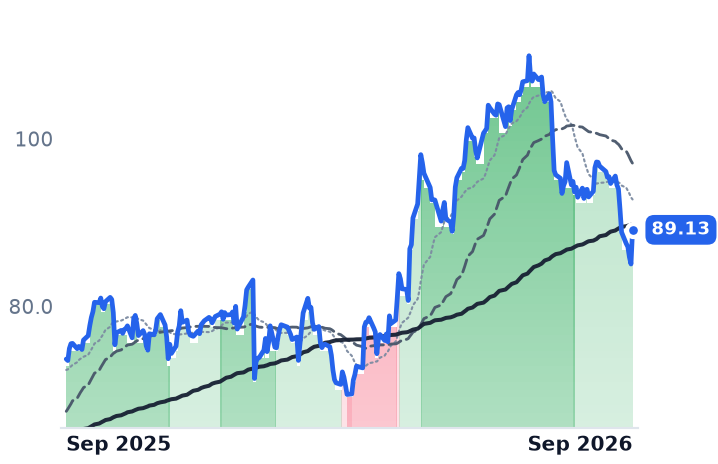
ALHC | Alignment Healthcare | Medicare Advantage Specialists | ⚠️ Emerging Bear | −39.7% | −53.0% |
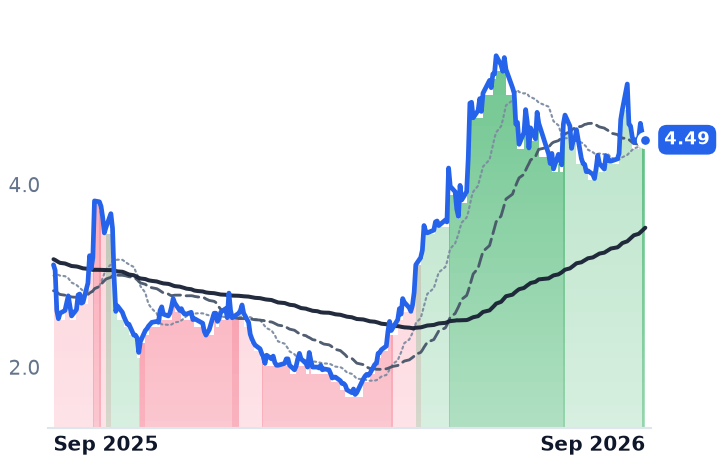
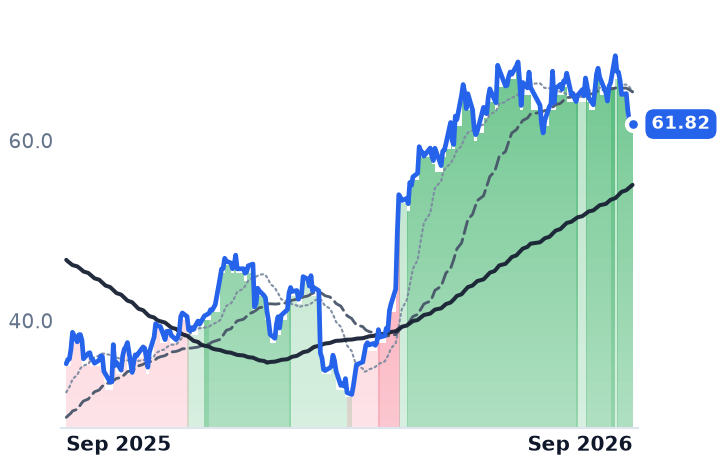
CLOV | Clover Health Investments | Medicare Advantage Specialists | 🟢 Cont. Bull | +6.1% | +43.9% |
| Compared against · context, not the story | |||||
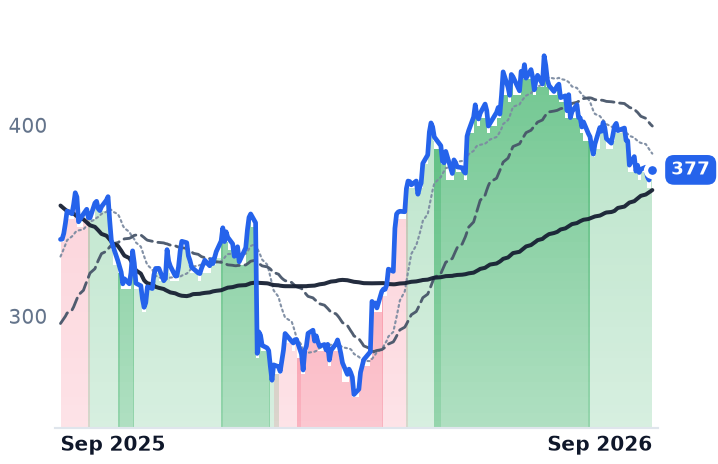
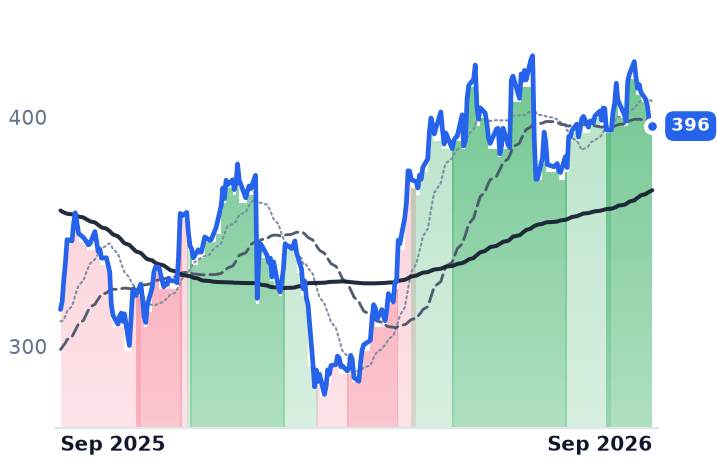
UNH | UnitedHealth Group Incorporated | Large Integrated Health Plans | 🟢 Cont. Bull | −4.2% | +10.7% |
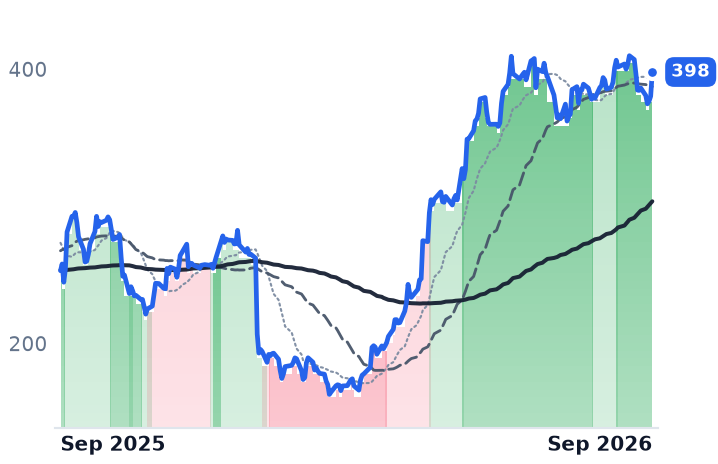
HUM | Humana | Large Integrated Health Plans | 🟢 Cont. Bull | +3.2% | +57.2% |
CVS | CVS Health | Large Integrated Health Plans | 🟢 Cont. Bull | −4.2% | +20.9% |
CNC | Centene | Government & Medicaid Plans | 🟢 Cont. Bull | −4.5% | +75.6% |
ELV | Elevance Health | Large Integrated Health Plans | 🟢 Cont. Bull | +0.4% | +25.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALHC | $1.7B | 41.2x | 45.2x | 0.4x | 0.3x | 3.0x | 2.6x | 15.5x | 12.1% |
CLOV | $2.3B | n/m | 80.1x | 0.9x | 0.8x | 5.1x | 4.2x | n/m | 3.2% |
UNH | $357.7B | 29.8x | 21.4x | 0.8x | 0.8x | 4.2x | 4.3x | 17.7x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HUM | $48.9B | 38.3x | 44.5x | 0.3x | 0.3x | 2.5x | 2.2x | 18.3x | -0.9% |
CVS | $122.3B | 41.6x | 13.0x | 0.3x | 0.3x | 2.2x | 2.2x | 17.2x | 6.0% |
CNC | $28.8B | n/m | 16.7x | 0.1x | 0.2x | 1.0x | 1.0x | n/m | 22.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ELV | $92.0B | 18.9x | 15.6x | 0.5x | 0.5x | 1.2x | 1.2x | 14.1x | 6.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ALHC | Revenue | +32.3% | +24.5% | +23.7% |
| EPS | −277.8% | +126.3% | +65.6% | |
CLOV | Revenue | +55.2% | +19.6% | +11.5% |
| EPS | −132.4% | +79.1% | +66.1% | |
UNH | Revenue | −0.9% | +2.9% | +5.7% |
| EPS | +12.5% | +13.1% | +18.8% | |
HUM | Revenue | +25.8% | +3.3% | +6.6% |
| EPS | −46.4% | +82.6% | +65.7% | |
CVS | Revenue | +1.8% | +4.4% | +5.5% |
| EPS | +10.8% | +13.0% | +15.4% | |
CNC | Revenue | −1.3% | +0.4% | +3.1% |
| EPS | +71.3% | +29.3% | +32.9% | |
ELV | Revenue | −0.7% | +2.2% | +5.5% |
| EPS | −9.5% | +9.2% | +14.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Alignment Healthcare told investors on 15 September that its third-quarter medical costs were running hot, and named the reasons: hospitals billing more aggressively, a heavier load of disputes and appeals, and longer skilled-nursing stays. At Baird's Global Healthcare Conference in New York the Orange, California insurer — which owns Medicare Advantage health plans in California, North Carolina and Nevada and also delivers care to members of unaffiliated plans — also disclosed $10m to $11m of unplanned investment earmarked for the second half. Full-year guidance was left unchanged. The shares fell 19.9% that session, from $12.94 to $10.37, on 28.5m shares against 5.7m the day before.
That matters beyond one session because of what the company says is causing it. The mechanism management gave is not utilization running above the bid it filed in June but a claims-system transition that left 2025 hospital bills landing in 2026 — a timing problem inside a business whose revenue is a per-member rate set annually in Washington and paid monthly regardless. "Whenever you go through a claims application implementation, those are messy and noisy... We are pretty much through the end of that, and there is a lot of data points that would suggest … all that noise is starting to settle down," chief executive John Kao said at the conference.
The meters went the other way
June-quarter revenue rose 31.6% to $1,336m, operating income rose 85.1% to $42.1m and net income more than doubled to $36.6m. Reported gross margin was 13.55% against 13.15% a year earlier, implying a medical benefit ratio — the share of premium consumed by claims — of 86.45%. The company's own adjusted figure was 86.3%, about 0.4 points better year over year, with the midpoint of membership, revenue and adjusted EBITDA guidance raised on 30 July. Guidance has been lifted or reaffirmed at every point in this decline, never trimmed.
Nor does an industry cost shock fit the window. UnitedHealth Group said its 2026 Medicare cost trend is running below its initial estimate of about 10%, with care patterns becoming more predictable. Humana is up 56.4% over twelve months and CVS Health 19.5%. Alignment is down 52.6%.
Clover, same book, opposite direction
Clover Health runs a capitated Medicare Advantage book roughly half Alignment's size out of Franklin, Tennessee, built around physician software it also licenses to outside providers through its Counterpart Health arm. June-quarter revenue rose 56% to $743m and Medicare Advantage membership 48% to 157,309, guidance went to $2.92–3.0bn of revenue, and it closed the quarter with $443m of cash and no debt. It carries a $2.33bn market value against Alignment's $1.70bn on half the sales.
On price to gross profit — the measure that survives a 13.5% margin sitting beside a 20.6% one, and Clover's trailing loss — Alignment now fetches 2.60x forward against 4.24x for Clover. On 10 September the two were 4.13x and 4.10x. Seventeen sessions opened the entire gap.
What the fall earns
The part the business explains is thin. Nothing in the reported numbers deteriorated; what changed is the market's willingness to underwrite a company still spending for growth while the largest carriers deliberately trade enrollment for margin. The genuinely unresolved part is legal and regulatory: a securities investigation opened after the Baird disclosures, and TD Cowen's estimate that losing the fourth star on Alignment's H3815 contract would cost roughly $175m of bonus revenue annually. Clover's own advantage is no safer — its half-star court win, worth an estimated $120m in 2027, went to the Eleventh Circuit on appeal on 21 July. And on earnings Alignment is not cheap at all: 45.2x forward against 41.2x trailing, because consensus 2026 earnings of $0.18 a share sit below the trailing base.
The Centers for Medicare and Medicaid Services publishes the 2027 star ratings in early October, and about half of the cut points got harder. Alignment's claim that essentially all its members will again sit in four-star-or-better plans rests on a preliminary read of that data. The confirmation arrives days before seniors start choosing.