

Dell Guided to $192bn and Wider Server Margins on a Record $95bn AI Backlog
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The cheapest premise in the AI-server trade is that the box builder earns nothing on the accelerator it resells. Dell's July quarter says otherwise: gross margin widened to 20.9% from 18.3% a year earlier on revenue up 58%, and the infrastructure segment that ships AI racks ran at a 15% operating margin, 620 basis points better than last year. Management's own forecast has that margin expanding again while AI server revenue roughly triples.
The builders paid alongside Dell split. Celestica raised guidance for the third time in six months, to $20.5bn, yet its gross margin slipped because assembly work grew faster than its own designs. Sanmina's revenue fell sequentially and its gross profit rose anyway. Jabil, the least concentrated in AI racks, is the one breaking down into its September 30 results.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
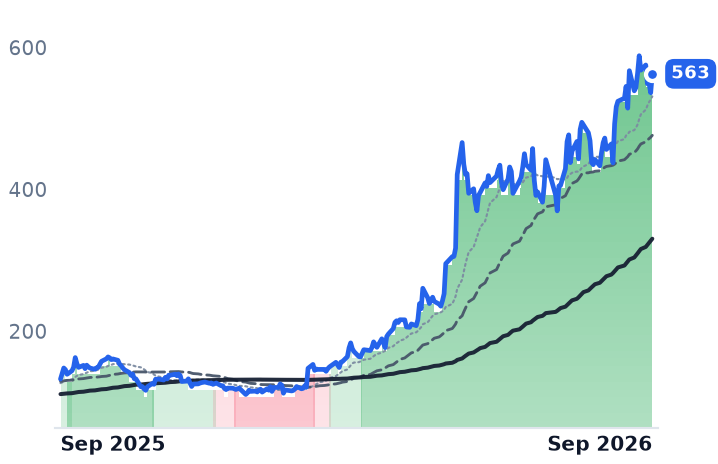
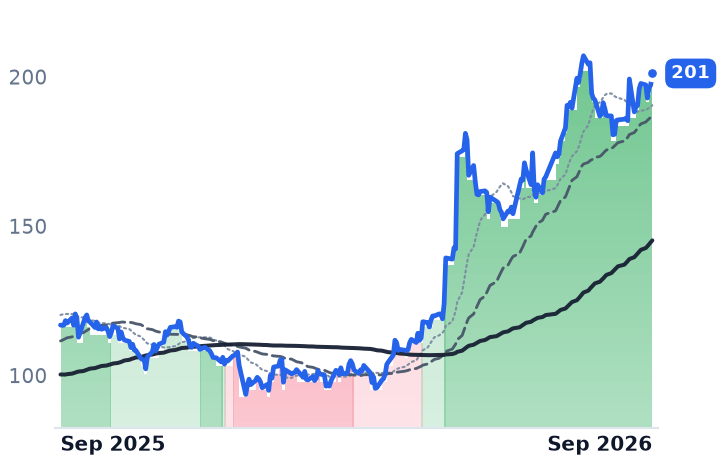
DELL | Dell Technologies | Enterprise Storage & Software | 🟢 Cont. Bull | +23.4% | +325.0% |
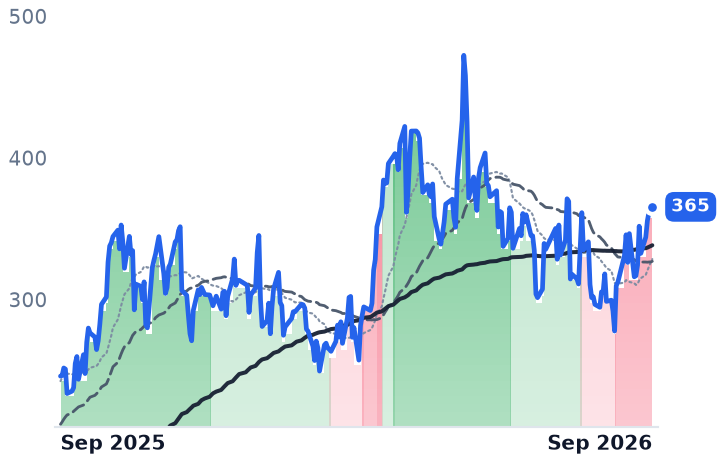
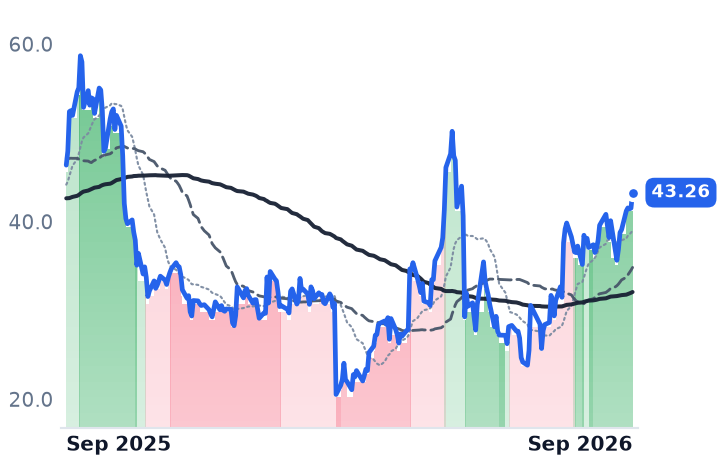
CLS | Celestica | Electronic Manufacturing Services | ⚠️ Emerging Bear | +22.3% | +48.6% |
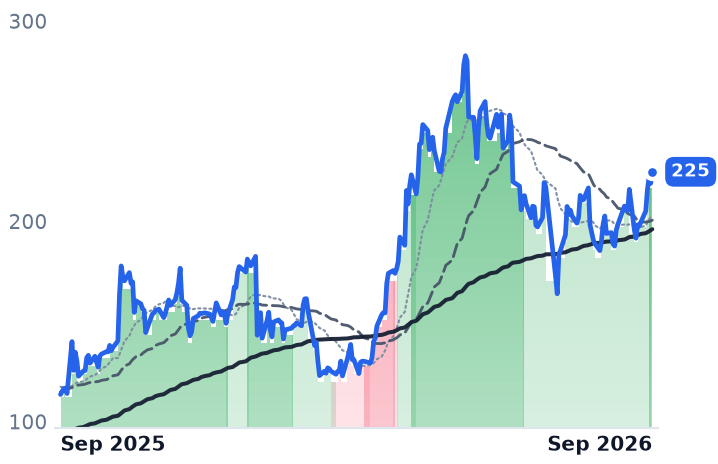
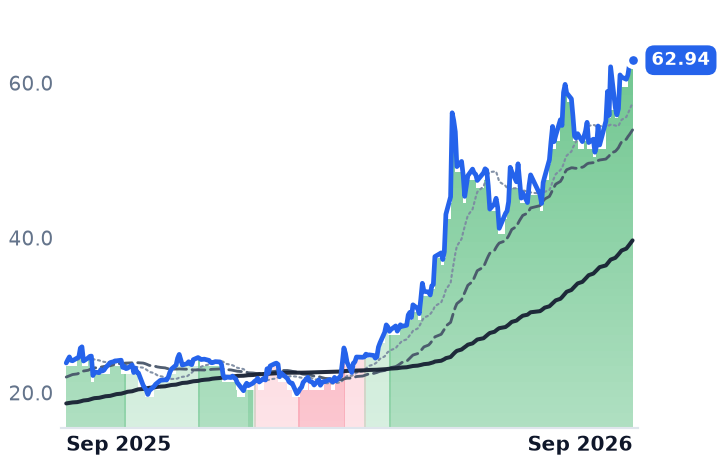
SANM | Sanmina | Electronic Manufacturing Services | 🟢 Cont. Bull | +15.9% | +97.9% |
| Compared against · context, not the story | |||||
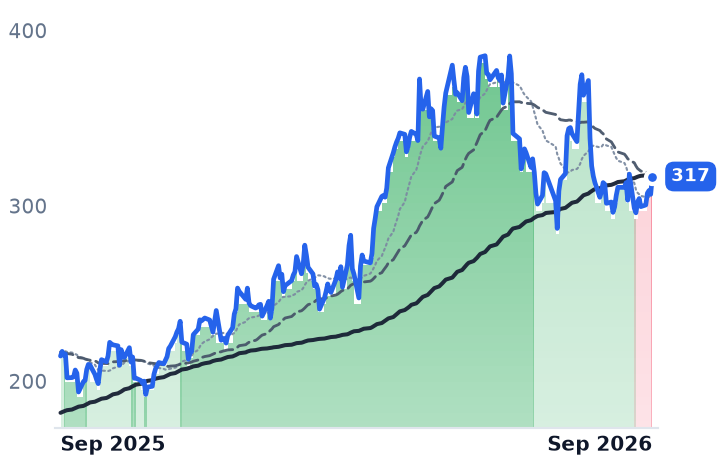
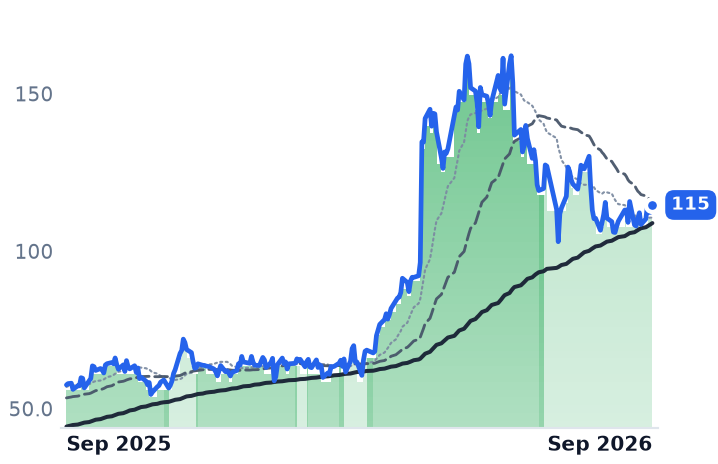
JBL | Jabil | Electronic Manufacturing Services | ⚠️ Emerging Bear | +5.1% | +47.8% |
NTAP | NetApp | Enterprise Storage & Software | 🟢 Cont. Bull | +7.6% | +72.1% |
SMCI | Super Micro Computer | Server & Infrastructure Systems | 🌱 Emerging Bull | +16.7% | −6.7% |
FLEX | Flex | Electronic Manufacturing Services | 🟢 Cont. Bull | +3.8% | +99.3% |
HPE | Hewlett Packard Enterprise | Enterprise Storage & Software | 🟢 Cont. Bull | +20.3% | +164.0% |
MU | Micron Technology | Memory (DRAM/NAND) | 🟢 Cont. Bull | +16.0% | +561.3% |
AMD | Advanced Micro Devices | AI & Data Center GPUs | 🟢 Cont. Bull | +35.5% | +290.8% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DELL | $373.9B | 32.2x | 21.7x | 2.5x | 1.9x | 12.5x | 9.7x | 21.6x | 2.3% |
CLS | $42.0B | 37.6x | 32.9x | 2.7x | 2.1x | 22.5x | 17.3x | 28.1x | 1.2% |
SANM | $12.0B | 39.4x | 16.1x | 0.9x | 0.7x | 10.5x | 8.2x | 18.9x | 4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
JBL | $32.2B | 37.9x | 18.3x | 1.0x | 0.8x | 10.4x | 8.2x | 16.3x | 4.7% |
NTAP | $38.5B | 27.3x | 19.6x | 5.2x | 4.7x | 7.4x | 6.7x | 18.4x | 4.3% |
SMCI | $26.8B | 11.4x | 9.6x | 0.7x | 0.4x | 6.3x | 3.7x | 8.5x | -26.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLEX | $40.1B | 41.9x | 23.1x | 1.4x | 1.2x | 14.4x | 12.2x | 22.7x | 2.7% |
HPE | $82.5B | 31.0x | 16.3x | 2.0x | 1.8x | 5.5x | 4.9x | 17.1x | 5.0% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMD | $1.0T | 156.2x | 80.7x | 24.3x | 19.7x | 45.7x | 37.0x | 93.6x | 0.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DELL | Revenue | +16.2% | +73.9% | +20.9% |
| EPS | +27.3% | +159.7% | +19.4% | |
CLS | Revenue | +64.9% | +72.1% | +33.1% |
| EPS | +85.6% | +73.5% | +36.3% | |
SANM | Revenue | +74.9% | +15.8% | +11.8% |
| EPS | +103.4% | +15.2% | +12.7% | |
JBL | Revenue | +20.2% | +21.8% | +13.4% |
| EPS | +35.9% | +31.6% | +21.6% | |
NTAP | Revenue | +4.3% | +19.4% | +6.3% |
| EPS | +10.4% | +25.3% | +11.0% | |
SMCI | Revenue | +77.7% | +69.8% | +17.7% |
| EPS | +33.5% | +54.7% | +23.3% | |
FLEX | Revenue | +6.8% | +26.3% | +30.0% |
| EPS | +24.2% | +44.7% | +51.5% | |
HPE | Revenue | +34.9% | +16.7% | +6.8% |
| EPS | +101.4% | +20.4% | +10.6% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
AMD | Revenue | +49.4% | +75.5% | +37.7% |
| EPS | +92.6% | +108.1% | +44.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dell's infrastructure business shipped a record $31.8bn of servers, storage and networking in the July quarter, and the margin on it went up. Operating margin in the Infrastructure Solutions Group reached 15%, 620 basis points better than a year earlier, while revenue from AI-optimized servers doubled to $16.4bn.
That combination matters beyond one quarter. The working assumption about AI servers is that the assembler is a toll booth — it buys somebody else's accelerator, integrates it into a chassis, and hands the economics to the silicon and memory makers. Dell's raised guidance argues the opposite. The company, which sells branded PowerEdge systems, storage and services through an enterprise channel and takes allocation priority on accelerator shipments, lifted its fiscal year by $25bn to $192bn of revenue and $25.50 of earnings per share, with AI server revenue of about $74bn — roughly three times the prior year — and infrastructure margin still expanding more than a point on that mix.
"We exited the quarter with a record $95 billion of AI backlog, and our pipeline continued to grow sequentially and remains multiples of our backlog even after converting $131.7 billion into orders over the past 12 months," chief operating officer Jeff Clarke told investors on the September 1 call. Orders in the quarter were $60.9bn. The AI customer base passed 6,500 accounts, 3,300 of them added in three quarters, which is a broader book than the handful of accelerator-rental startups the bear case assumes.
The bought-in component went up and got repriced
Management named memory as the binding constraint — dynamic random-access memory and NAND flash first, then processors, disk and optical — and attributed the guidance raise to redirecting component supply from PCs into infrastructure rather than to any change in demand. Memory is the largest bought-in item in an AI server, and its cost roughly doubled through the first half of 2026; Micron's data-center revenue rose more than sevenfold to $11.5bn in its May quarter. Dell absorbed that and widened gross margin anyway. The differentiator among assemblers this year has been quoting terms and repricing speed, not end demand.
The cash has lagged the profit. Dell's 10-Q for the quarter shows receivables of $22.9bn against $17.6bn in January, growth slower than first-half sales; inventories rose $4.7bn over six months while payables rose $11.7bn, so suppliers financed the build twice over. The operating cash figures disagree — the filing indicates $4.1bn for the half, management cited $6.3bn on the call — and only the direction, cash trailing earnings, is agreed.
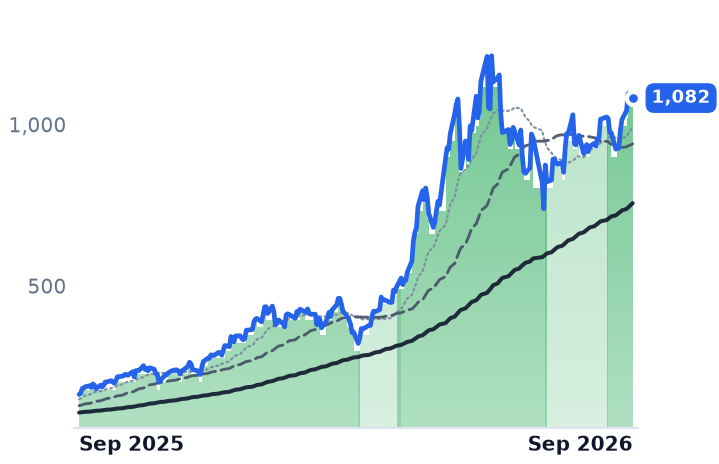
Dell trades at 32.2x trailing and 21.7x forward earnings, and its price against trailing gross profit has more than doubled this year, to 12.5x from 5.85x on May 3. Consensus has revenue up about 74% this fiscal year and then 21% the next: the forward figure is paid against one exceptional year. At $562.90 the shares sit essentially on the average analyst target near $564, with Citi and Bank of America at $600.
Paid a conversion fee for the same rack
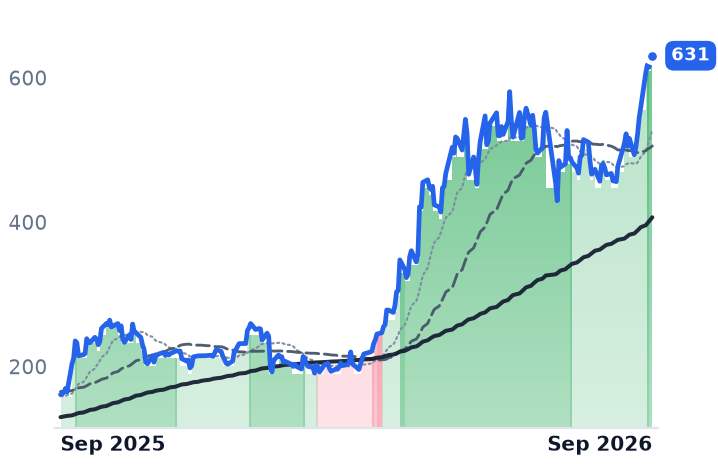
Celestica, the Toronto builder that assembles and increasingly designs racks, switches and interconnect for hyperscalers, is the awkward case. Its growth has accelerated for four straight quarters, to 62% in the June quarter, and it raised 2026 guidance for the third time in six months, to $20.5bn of revenue and $11.30 of adjusted earnings per share. Gross margin still slipped, to 12.29%, because its own-design Hardware Platform Solutions line grew 58% while the assembly-heavy Connectivity and Cloud segment around it grew 84%. Three customers are 63% of revenue. The ramp was funded with equity: about 11.1m shares priced at $310 in August, near a tenth of the diluted count. The shares are flat over three months and cheaper than in spring against gross profit, 22.5x trailing versus 26.1x on May 3, after a 31.6% climb off a September 2 low with no earnings inside the window. The investor day is October 27, with third-quarter results.
Sanmina is the cleanest test of who owns the accelerator dollar. Having bought ZT Systems' manufacturing business from AMD for $2.25bn plus consideration, the contract manufacturer saw June-quarter revenue fall 13.7% sequentially to $3.464bn — and gross profit rise 2.7%, with margin up 167 basis points to 10.49%. The dollars that left were the silicon, not the labor. Guidance puts ZT revenue at $0.8–1.0bn in the September quarter on timing shifts in legacy programs, with next-generation accelerated compute deferred to fiscal 2027. It is the cheapest of the three at 16.1x forward earnings against 39.4x trailing.
What the money is actually buying
So the AI assembly dollar is being paid better, not thinner, and the evidence runs in both directions across the group. Where an assembler resells accelerators it earns little on them, which is why Sanmina's margin rose as that content shrank; where it converts, integrates and reprices, the margin holds. Dell earns its advance on accelerating revenue, expanding segment margin and a backlog with a date on it. Celestica's business earns an advance its price has not delivered for three months; the likelier reading of the September round trip is positioning, given that industrial-side AI names decoupled from semiconductors without any change in order books.
The contrast that settles it sits at the edges. NetApp, in storage, has re-rated to 8.2x trailing gross profit from 4.6x in May while guiding fiscal 2027 gross margin down to 68.5–69.5% from 71.3% on component costs — a higher price for a thinner margin. Jabil, the most diversified and least rack-concentrated of the large contract manufacturers, has fallen 15.5% in three months and reports its fiscal fourth quarter on September 30. Being near the rack is doing the work; being near the enclosure is not.
Dell's own forecast is the claim to hold management to: AI revenue roughly tripling and infrastructure margin wider at the end of it. One of those two has never happened before at this scale.