

Tandem Shipped a Record 33,000 Pumps Into a Medicare Rule That Pays by the Month
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
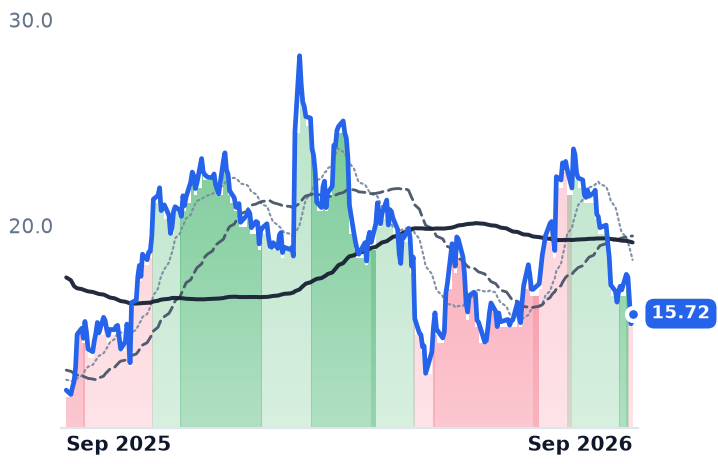
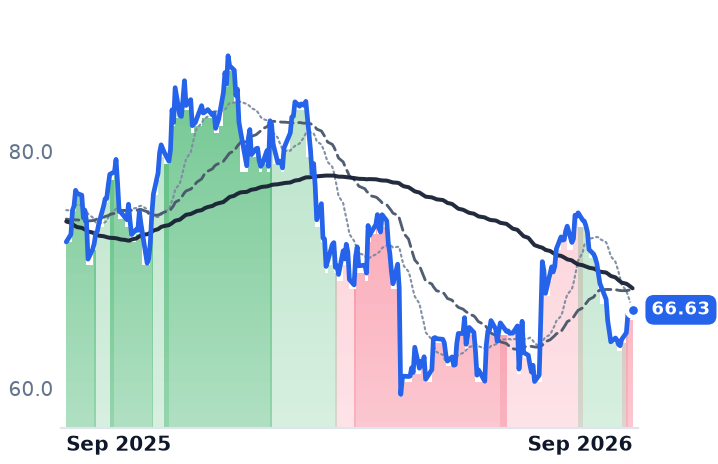
Tandem Diabetes Care reaffirmed full-year sales guidance of $1.065–1.085bn in August and lifted gross margin 4.6 points year over year — and its shares have fallen 27.7% in a month, giving back the entire 19.1% jump they made the session after those results.
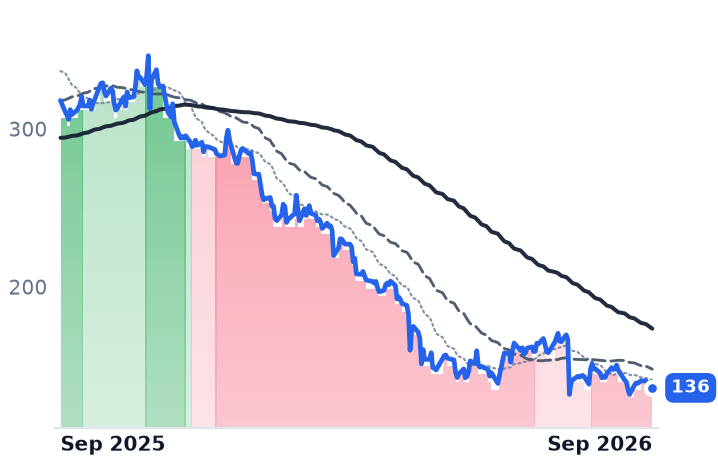
Insulet is the same disagreement over a longer horizon: revenue up 23.5% and gross margin at 70.2%, against a 58% compression in its forward earnings multiple over twelve months. Only Dexcom rose, and its revenue growth halved on the way.
The one force all three share is Medicare's reclassification of continuous glucose monitors and insulin pumps as monthly rentals subject to competitive bidding — bids now, prices in 2027, contracts in 2028. It lands hardest on Tandem's up-front pump and not at all on Insulet's pharmacy-benefit pod.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TNDM | Tandem Diabetes Care | Diabetes & Continuous Monitoring | ⚠️ Emerging Bear | −27.7% | +31.0% |
PODD | Insulet | Diabetes & Continuous Monitoring | 🔴 Cont. Bear | −4.6% | −57.2% |
DXCM | DexCom | Diabetes & Continuous Monitoring | 🟢 Cont. Bull | −3.9% | +29.1% |
| Compared against · context, not the story | |||||
ABT | Abbott Laboratories | Other | 🌱 Emerging Bull | −9.6% | −23.0% |
BETA | BETA Technologies | eVTOL & Urban Air Mobility | 🌱 Emerging Bull | +9.3% | −33.7% |
BSX | Boston Scientific | Spinal Surgery & Neuromodulation | 🔴 Cont. Bear | −7.0% | −55.3% |
SYK | Stryker | Orthopedic Implants & Trauma | 🔴 Cont. Bear | −16.9% | −25.6% |
MDT | Medtronic | Spinal Surgery & Neuromodulation | 🟢 Cont. Bull | −2.8% | −4.5% |
GEHC | GE HealthCare Technologies | Diagnostic Imaging & Devices | ⚠️ Emerging Bear | −8.9% | −7.9% |
RMD | ResMed | Sleep & Respiratory Care | 🌱 Emerging Bull | −6.4% | −17.2% |
XRAY | DENTSPLY SIRONA | Surgical Instruments & Solutions | 🔴 Cont. Bear | −15.9% | −23.7% |
ISRG | Intuitive Surgical | Surgical Robotics & Minimally Invasive Surgery | 🔴 Cont. Bear | +10.1% | −8.1% |
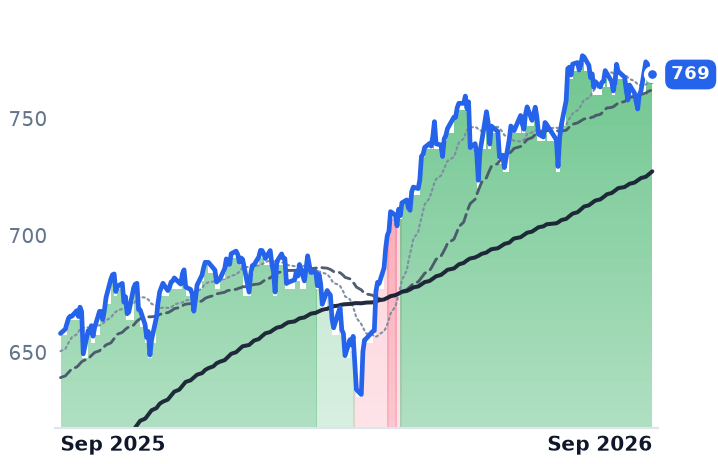
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.1% | +17.2% |
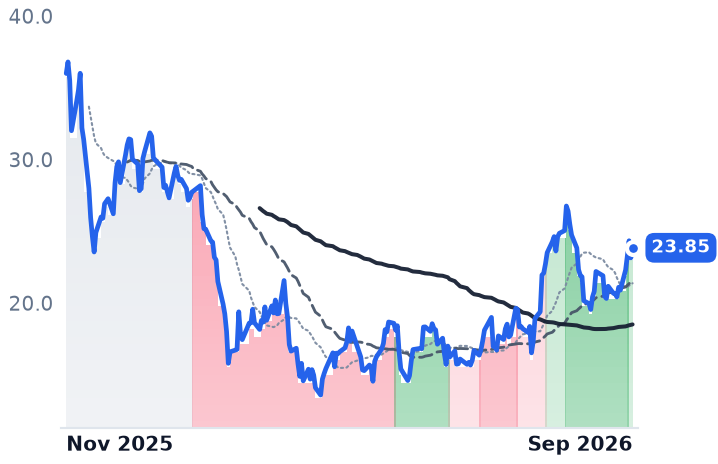
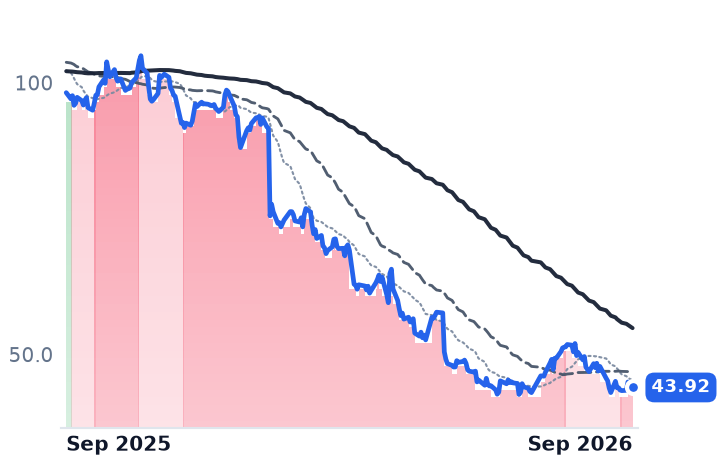
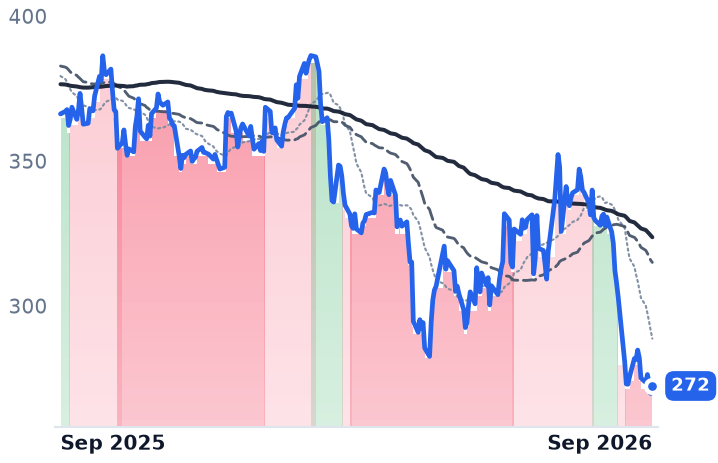
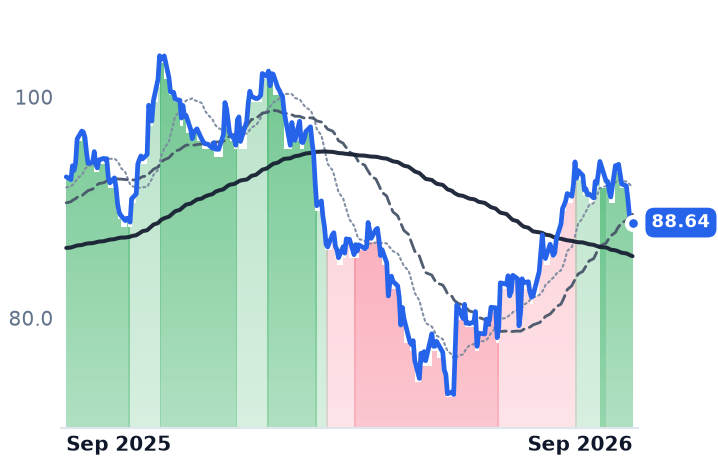
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TNDM | $1.1B | n/m | — | 1.0x | 1.0x | 1.8x | 1.8x | n/m | -2.5% |
PODD | $9.4B | 25.4x | 20.9x | 3.1x | 2.9x | 4.3x | 4.0x | 15.5x | 3.2% |
DXCM | $32.7B | 33.4x | 32.5x | 6.6x | 6.2x | 10.5x | 10.0x | 21.2x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ABT | $147.1B | 23.5x | 15.4x | 3.3x | 2.9x | 5.8x | 5.2x | 16.1x | 5.0% |
BETA | $5.9B | n/m | — | 130.8x | 125.3x | 282.4x | 270.3x | n/m | -7.2% |
BSX | $63.9B | 17.3x | 13.1x | 3.0x | 3.0x | 4.3x | 4.2x | 13.4x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SYK | $105.5B | 28.3x | 18.3x | 4.1x | 3.9x | 6.3x | 5.9x | 18.7x | 4.5% |
MDT | $116.4B | 22.2x | 15.2x | 3.1x | 3.0x | 4.7x | 4.5x | 15.1x | 5.3% |
GEHC | $27.6B | 18.4x | 12.4x | 1.4x | 1.3x | 3.3x | 3.0x | 11.3x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RMD | $29.3B | 19.5x | 18.2x | 5.3x | 5.2x | 8.6x | 8.4x | 13.5x | 6.0% |
XRAY | $2.0B | n/m | 7.1x | 0.5x | 0.6x | 1.1x | 1.2x | n/m | 5.2% |
ISRG | $149.1B | 50.2x | 40.6x | 14.1x | 12.8x | 21.3x | 19.2x | 39.1x | 1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TNDM | Revenue | +7.1% | +12.4% | +13.8% |
| EPS | −67.7% | −120.7% | +473.3% | |
PODD | Revenue | +22.2% | +14.0% | +13.8% |
| EPS | +33.1% | +18.5% | +20.2% | |
DXCM | Revenue | +12.4% | +10.8% | +11.3% |
| EPS | +29.5% | +17.0% | +19.2% | |
ABT | Revenue | +12.8% | +9.0% | +7.3% |
| EPS | +6.2% | +10.7% | +11.6% | |
BETA | Revenue | +47.8% | +569.3% | +193.9% |
| EPS | −58.4% | +2.1% | −12.8% | |
BSX | Revenue | +6.2% | +4.4% | +7.0% |
| EPS | +8.3% | +3.9% | +10.8% | |
SYK | Revenue | +8.7% | +8.8% | +7.8% |
| EPS | +10.6% | +11.6% | +11.3% | |
MDT | Revenue | +7.9% | +8.0% | +3.5% |
| EPS | +1.1% | +8.3% | +7.1% | |
GEHC | Revenue | +6.1% | +4.7% | +4.7% |
| EPS | +7.7% | +10.6% | +11.4% | |
RMD | Revenue | +10.2% | +7.6% | +6.9% |
| EPS | +16.8% | +10.2% | +9.7% | |
XRAY | Revenue | −1.7% | +2.0% | +2.5% |
| EPS | −11.4% | +8.8% | +10.2% | |
ISRG | Revenue | +17.5% | +13.5% | +13.7% |
| EPS | +19.6% | +13.4% | +13.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Tandem Diabetes Care, which sells the t:slim X2 durable insulin pump to insulin-dependent patients, shipped a record 33,000 pumps worldwide in the second quarter and left its full-year outlook of $1.065–1.085bn alone. Its shares are down 27.7% over the past month and have surrendered the whole 19.1% gain they made the day after that report.
Dexcom, Insulet and Tandem sell the same patient the same promise — hardware or a disposable that must be replaced for life — and are paid for it in three incompatible ways. Dexcom bills per disposable glucose sensor. Insulet bills per Omnipod, pay-as-you-go through the pharmacy counter, with no durable device sold first. Tandem sells a pump up front against a roughly four-year replacement queue. In a final rule issued on 28 November 2025, Medicare decided that two of those three models get paid differently: continuous glucose monitors and insulin pumps are reclassified as "frequently and substantially serviced", moved onto continuous monthly rental and pushed into competitive bidding, with roughly ten national contract suppliers expected in the category. Bidder registration and the bid window open in late summer and early fall of this year; single payment amounts arrive in 2027, contracts on 1 January 2028. Congressional Diabetes Caucus leaders have formally objected that the change will complicate patient access, so the eventual price is unresolved — which is precisely the shape of a discount that accrues over a quarter instead of a morning.
The pump that loses its up-front payment
Tandem's revenue grew 5.8% in the quarter, a crawl beside its peers, but the operating line moved: gross margin of 56.9% against 52.3% a year earlier, and an operating loss narrowed 73% to -$13.8m. It also reaffirmed 94,000–95,000 US pump shipments for the year and filed its tubeless Mobi pump with the Food and Drug Administration. "Getting into that market … is gonna give us access to a significantly higher interest level and it is going to drive meaningful growth," chief executive John Sheridan said on the 6 August call, noting tubed pumps grow at mid-single digits while tubeless grows above 20%.
The shares now fetch 1.00x forward sales, down from roughly 1.66x in late February on essentially unchanged consensus revenue. Two identifiable reasons exist. Beta Bionics, whose iLet pump reached about 10% of new-patient share and grew second-quarter sales 38%, rose 42.8% over three months while Tandem fell — a share shift, not a shrinking market. And Tandem is the single name whose payment model Medicare is rewriting: the up-front durable-equipment sale becomes a bid-set monthly rental. Truist cut its price target to $28 from $31 in late September while keeping a buy rating, citing recalibrated medtech valuations rather than demand.
The pod Medicare cannot bid
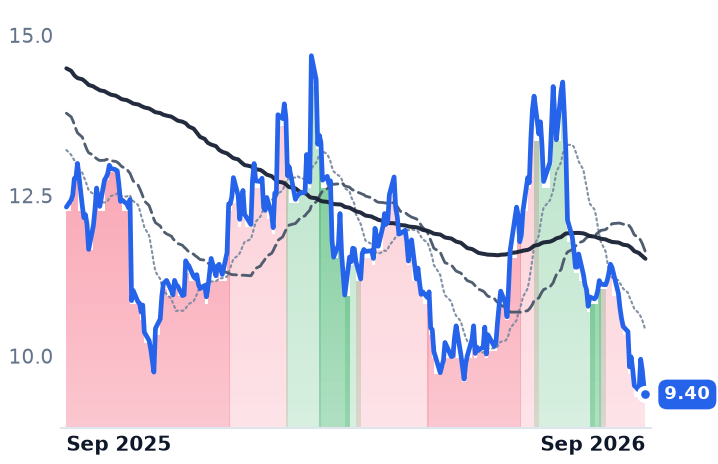
Insulet's second quarter, reported 5 August, was $801.7m of revenue, up 23.5%, above its own guidance range, with international Omnipod up 35.5% and gross margin at 70.2%, a five-quarter high. The break was retention: it trimmed full-year US Omnipod growth to 17–19% from 20–22% because type 2 customers were staying and using less than expected, and the stock fell 20.9% that session. "While we are updating our outlook to reflect what we're learning as we scale in type 2, our conviction in the long-term opportunity remains unchanged," chief executive Ashley McEvoy said. The shares trade at 20.9x forward earnings against 25.4x trailing; a year ago the same FY2026 consensus of $6.50 a share implied close to 50x. Meanwhile Omnipod sits inside the Medicare Part D pharmacy benefit, which is not subject to competitive bidding.
The one that rose
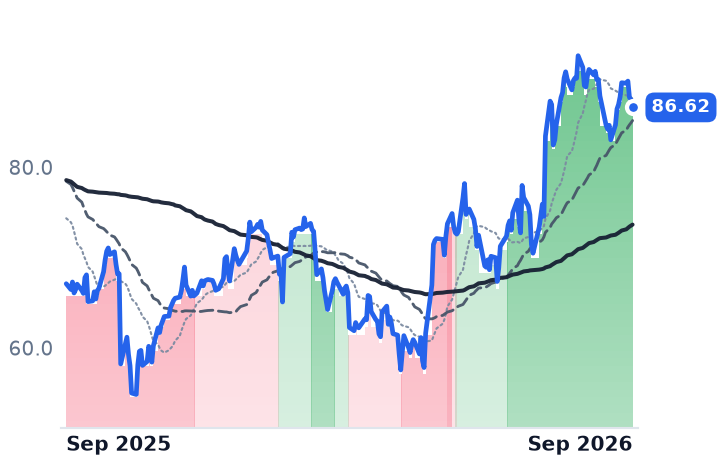
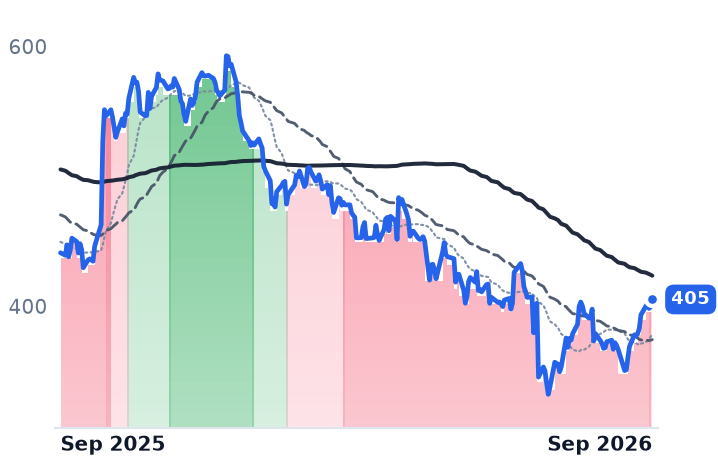
Dexcom, the sensor maker, is the group's advancer, up 26.8% over twelve months. Its economics improved rather than eroded: gross margin of 63.4% versus 59.5%, adjusted gross margin up 400 basis points to 64.1% with full-year guidance raised, and its own filing crediting higher sensor volumes and favorable revenue per customer, partly offset by channel mix and rebate eligibility. It also won coverage across the four largest commercial pharmacy benefit managers. "We carried forward solid demand from the first quarter for Dexcom CGM globally as we benefited from broader access and share gains," chief executive Jake Leach told investors on 30 July. But revenue growth halved, from 21.6% a year ago to 13.1%, and the forward multiple went the other way: about 22x at the 30 April low, 32.5x now on an unchanged $2.67 of FY2026 consensus earnings, barely below its 33.4x trailing. Dexcom straddles both payment worlds, with a rental ceiling illustrated at $272.69 a month on the Medicare side.
What each part earns
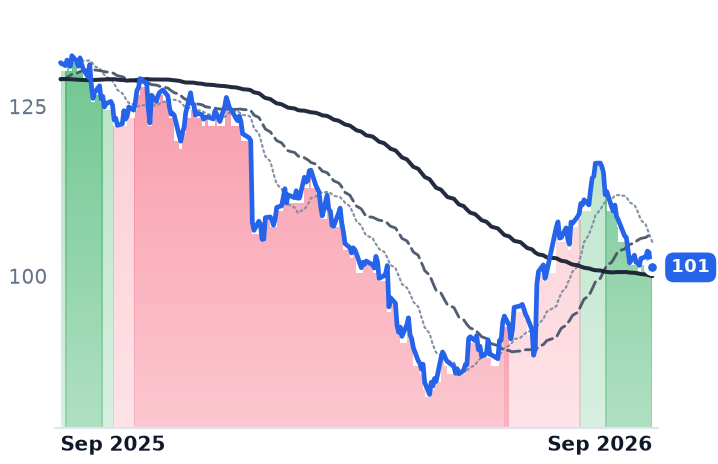
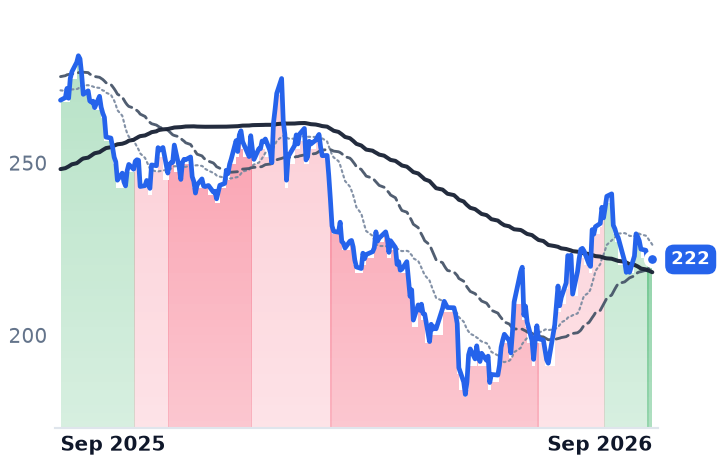
The last month was not kind to devices generally — Stryker fell 16.9% and Abbott 9.6% while the S&P 500 was flat — so Dexcom's and Insulet's declines were milder than the peer median, and Tandem is the outlier that needs explaining. The most-cited structural bear case has meanwhile inverted: Dexcom data at this year's American Diabetes Association meeting showed sensor use nearly quadrupling among non-insulin users after starting a GLP-1 drug.
So the margin expansion Dexcom earns; the 46% expansion in its multiple while growth halved, nothing in the operating line explains. Insulet's guidance cut is worth about 300 basis points of US growth, which does not buy a 58% compression in its multiple, though retention is the first genuinely new fact anyone has about patient demand in this niche. And Tandem's discount rests on two things that are real but dated far out — a rival taking new starts today, and a payment change that sets prices in 2027.
The number nobody has yet is the single monthly amount Medicare will pay for a pump. Tandem trades as though it has already been published.