

Ascendis Now Funds Itself on Three Drugs Novo Nordisk's Exit Never Touched
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Ascendis Pharma lost a partnered obesity program in September and the shares took the blow, even though the drug in question was never in the numbers. The Danish rare-disease company grew second-quarter revenue 118.2% year over year and swung its operating margin to 18.4% from -33.5%, with EUR 812m of cash, no bank or convertible debt and a buyback running.
The stock is down 10.1% over thirty days, most of it in one session. What that session priced was optionality, not the annuity: three approved medicines billing per patient, per week. Cytokinetics, the nearer comparison inside the same Barron's takeout list, is also selling a launched drug now — and is carried at roughly five times Ascendis's forward sales multiple with no consensus profit until 2029.
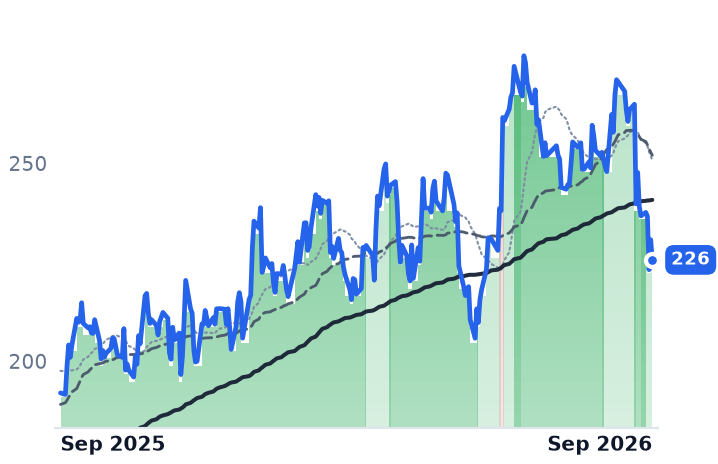
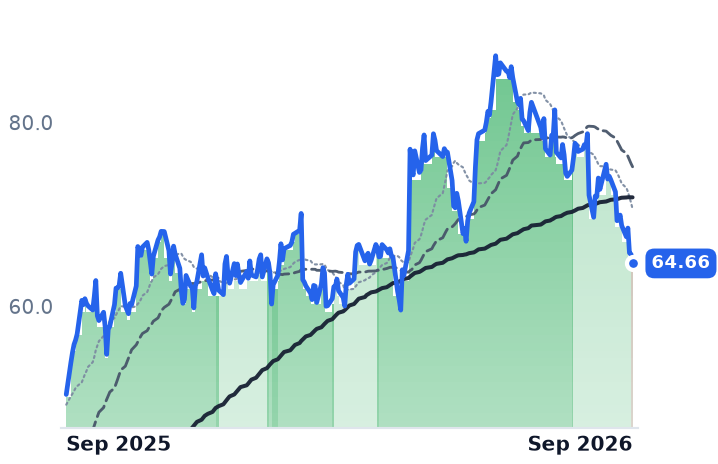
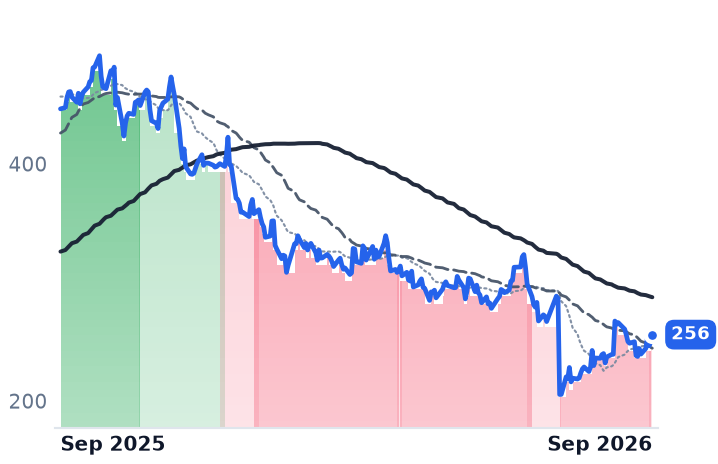
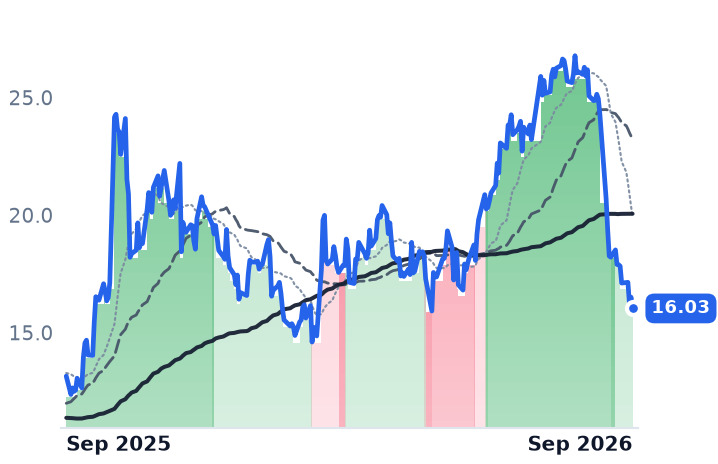
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ASND | Ascendis Pharma A/S | Rare Genetic & Metabolic Diseases | 🟢 Cont. Bull | −9.5% | +17.5% |
CYTK | Cytokinetics, Incorporated | CNS & Neurological | 🟢 Cont. Bull | −17.9% | +28.3% |
ALNY | Alnylam Pharmaceuticals | RNA-Based Therapeutics | 🔴 Cont. Bear | +10.3% | −42.7% |
| Compared against · context, not the story | |||||
DYN | Dyne Therapeutics | Gene Therapy & Cell Therapy | 🟢 Cont. Bull | −38.8% | +21.9% |
MLTX | MoonLake Immunotherapeutics | Immunology & Autoimmune | 🔴 Cont. Bear | −23.0% | −80.6% |
PCVX | Vaxcyte | Infectious Diseases & Vaccines | 🟢 Cont. Bull | −8.4% | +65.4% |
CGON | CG Oncology | Other | 🟢 Cont. Bull | −14.1% | +78.9% |
DNLI | Denali Therapeutics | CNS & Neurological | 🟢 Cont. Bull | −16.3% | +46.2% |
BMRN | BioMarin Pharmaceutical | Rare Genetic & Metabolic Diseases | 🌱 Emerging Bull | −7.7% | +11.9% |
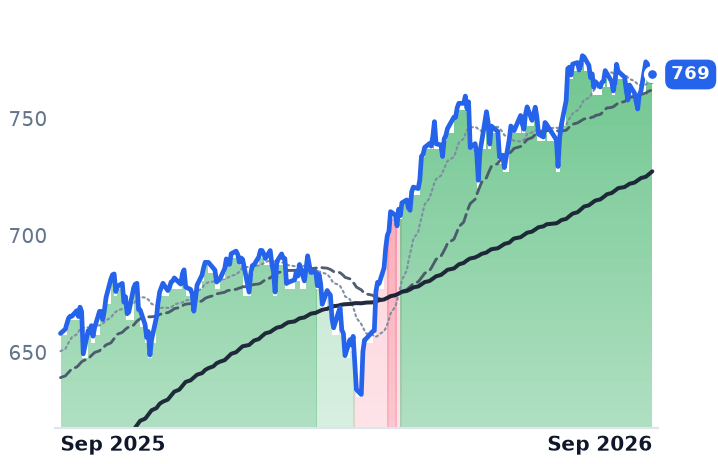
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.1% | +17.2% |
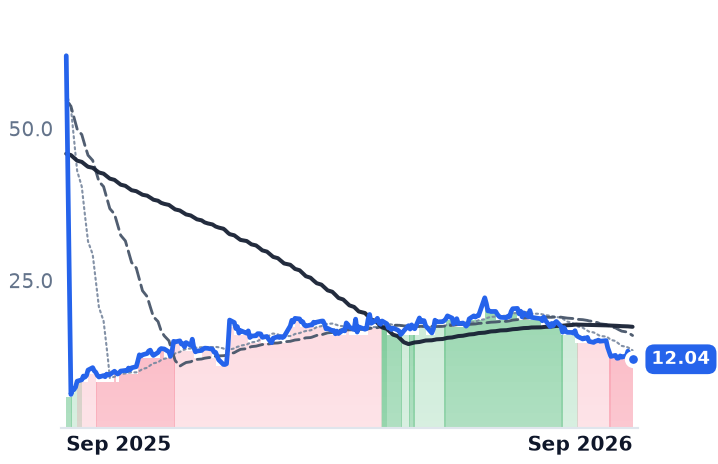
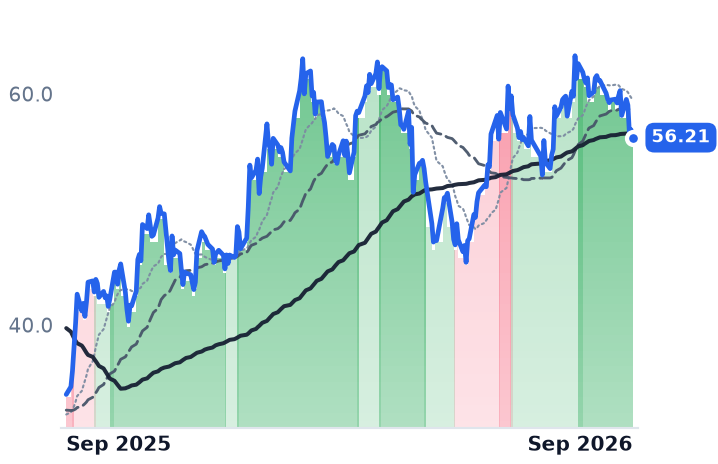
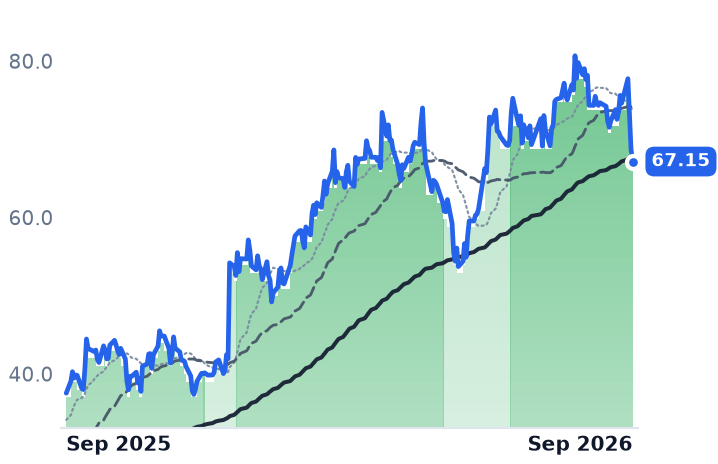
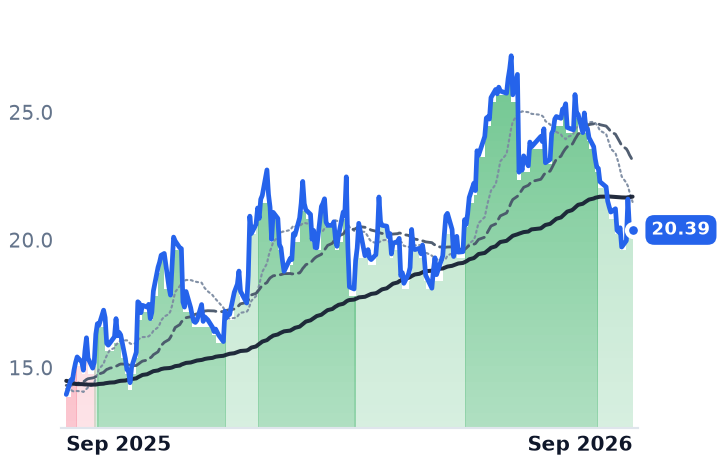
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASND | $14.0B | 16.4x | 16.2x | 11.7x | 10.4x | 12.9x | 11.5x | 152.8x | 2.7% |
CYTK | $8.0B | n/m | — | 113.4x | 53.7x | 133.4x | 63.2x | n/m | -7.2% |
ALNY | $34.2B | 42.0x | 38.4x | 7.1x | 6.3x | 8.9x | 7.9x | 29.4x | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DYN | $3.0B | n/m | — | n/m | — | — | — | n/m | -16.7% |
MLTX | $1.6B | n/m | — | n/m | — | — | — | n/m | -14.5% |
PCVX | $8.4B | n/m | — | n/m | 335.4x | — | — | n/m | -14.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CGON | $6.3B | n/m | — | — | 568.3x | — | — | n/m | -2.6% |
DNLI | $3.7B | n/m | — | n/m | 104.4x | — | — | n/m | -11.5% |
BMRN | $12.6B | 171.3x | — | 3.7x | — | 4.9x | — | 41.2x | 5.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ASND | Revenue | +90.9% | +46.5% | +27.1% |
| EPS | −516.5% | −35.2% | +58.5% | |
CYTK | Revenue | +94.8% | +182.8% | +110.5% |
| EPS | −6.8% | −26.1% | −52.9% | |
ALNY | Revenue | +45.6% | +26.9% | +19.6% |
| EPS | +171.3% | +51.0% | +24.2% | |
DYN | Revenue | +43.8% | +5202.8% | +423.5% |
| EPS | +3.5% | −7.7% | −24.6% | |
MLTX | Revenue | — | — | +499.2% |
| EPS | +6.4% | −5.3% | −19.5% | |
PCVX | Revenue | — | +248.6% | +103.3% |
| EPS | +51.9% | −19.8% | −5.5% | |
CGON | Revenue | +292.5% | +669.5% | +432.7% |
| EPS | +26.5% | +2.4% | −97.0% | |
DNLI | Revenue | +1299.4% | +204.0% | +150.9% |
| EPS | −18.1% | +0.8% | −24.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
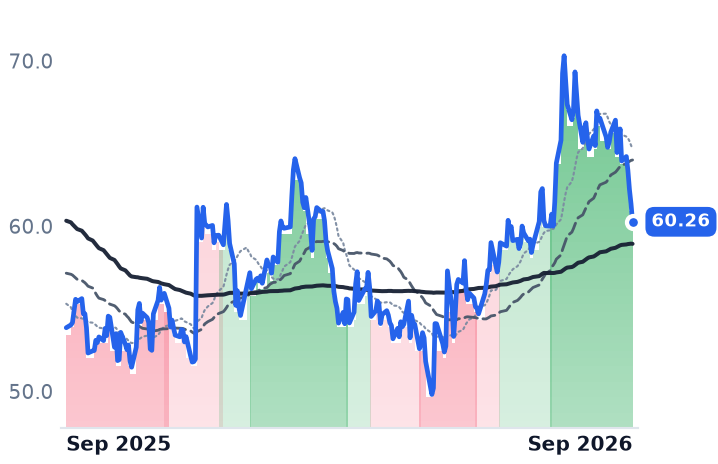
Ascendis Pharma got its obesity chemistry back on September 14, and its shares fell 9.5% the next session on 2.96m shares against roughly 200,000 in the days before. Novo Nordisk terminated the 2024 collaboration whose lead program was a once-monthly version of semaglutide built on the Danish company's TransCon carrier, handing the rights back across metabolic and cardiovascular disease. The pact had carried up to $285m in upfront, development and regulatory payments. Neither side now owes the other anything.
That one day is most of Ascendis's 10.1% decline over the past month, and it is a clean test of what the market pays for in mid-cap biotech — an option on a partnered obesity drug, or approved medicines already billing. Ascendis lost the first. The second is what the company actually is.
Paid by the patient, by the week
Ascendis, headquartered in Hellerup and worth $14.0bn, sells three rare-disease drugs built on one prodrug chemistry that tethers a hormone to an inert carrier so a daily injection becomes a weekly or monthly one: Skytrofa for growth hormone deficiency, Yorvipath for hypoparathyroidism, and Yuviwel for pediatric achondroplasia. Second-quarter revenue reached $344.9m, up 118.2% year over year, at a 90.6% gross margin. Operating margin came in at 18.4% against -33.5% a year earlier, the fifth consecutive quarterly improvement.
Reported in euros on the August 13 call, product revenue was EUR 315m, of which Yorvipath supplied EUR 252m on roughly 1,000 unique new US patients per quarter; Skytrofa contributed EUR 55m and Yuviwel EUR 8m in a first partial quarter with more than 220 enrollments. The economics are a subscription, and the leak is retention. "The majority of the drop-off is during that titration period in terms of when patients experience the most amount of change and where additional education and a higher touch support model makes sense," Jay Wu, president of Ascendis US, told investors on August 13.
The company closed the quarter with EUR 812m of cash, EUR 1.4bn of equity, no bank or convertible debt, and repurchased EUR 56m of its own shares while guiding to operating cash flow above EUR 500m for 2026. No guidance was trimmed. Annual revenue has gone from $7.8m in 2021 to $691.7m in 2025 while the annual operating loss narrowed from $451.8m to $130.9m.
The other value transfer inside the drawdown window went the other way in the market's reading. On August 30-31 Ascendis and BioMarin settled their patent disputes globally, with Ascendis paying 20% of US Yuviwel net sales retroactive to first sale and 18% in the EU, Brazil and South Korea until May 2030. The shares rose 5.8% that session: an import-ban risk before the US International Trade Commission was removed, and the royalty was the price.
What the launch costs
Cytokinetics is the nearer comparison and the sharper contrast. The South San Francisco company launched MYQORZO, an oral cardiac myosin inhibitor, in the US in January against Bristol Myers Squibb's incumbent Camzyos; product revenue went from $4.8m in the first quarter to $25m in the second. But total revenue fell 52.2% as collaboration income rolled off, the operating loss widened 57.7% to $175.9m, and consensus shows no net profit until 2029. It trades at 53.7x forward sales — roughly five times Ascendis's 10.4x, for a business three years from earning anything.
The premium is not what broke
Seven of the eight names on Barron's SMID-biotech takeout list fell over the past thirty days. Strip Dyne and MoonLake, each with its own datable blowup, and the remaining six averaged -9.6% against the equal-weight biotech benchmark XBI's roughly 8.3% decline. That residual is duration: the Federal Reserve's benchmark at 4.00% and a 10-year Treasury yield at its highest in nineteen years discount pre-profit biotech hardest. Acquisition appetite is not deflating — first-half 2026 biopharma deal value reached about $130bn across 42 deals, with average deal size up to $3.1bn from $2.7bn, and Novartis paid a 46% premium for Avidity. Alnylam, the one member too large to be bought, is the only one up over the period, having done its own damage on a guidance cut in August.
So the verdict on Ascendis splits cleanly. The market took roughly a tenth off a company whose operating line inflected, in exchange for one forgone partnership option and one royalty that bought away a trade-ban risk. Neither counterparty event touches Yorvipath's per-patient revenue, and the earnings multiple that would normally arbitrate is useless here — first-quarter net income of $639.7m sat on $25.2m of operating income, an artifact of one-off items.
The obesity program Novo returned had not yet earned a dollar. The thousand American patients starting Yorvipath each quarter already have.