

The Energy Department Cut Centrus to a $15m Storage Contract That Expires September 30
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The only federal contract that ever paid an American company to make high-assay low-enriched uranium has been reduced to a three-month caretaking job, and it runs out this week. Centrus Energy's enrichment unit sales fell 23% in the June quarter and operating income fell 69% to $10.4m; the government-funded engineering segment that housed the fuel work shrank 21% to $22.7m.
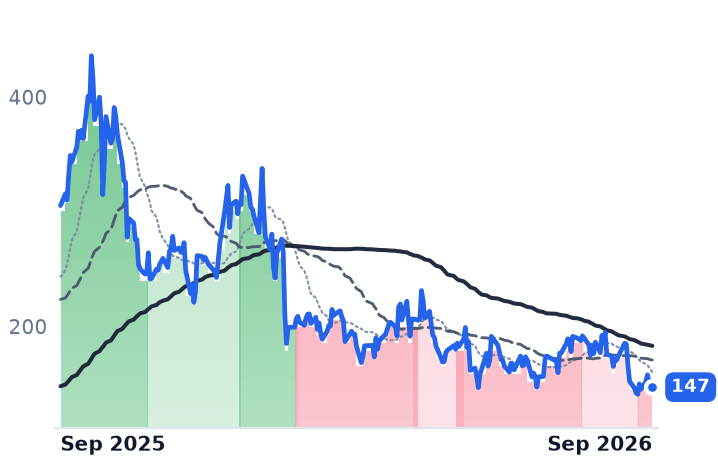
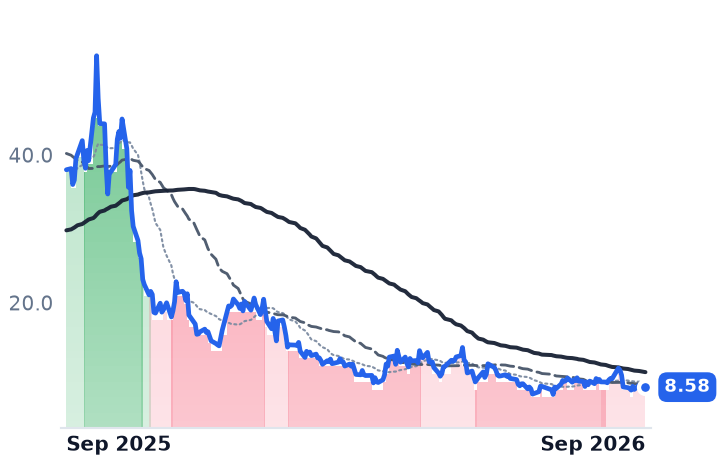
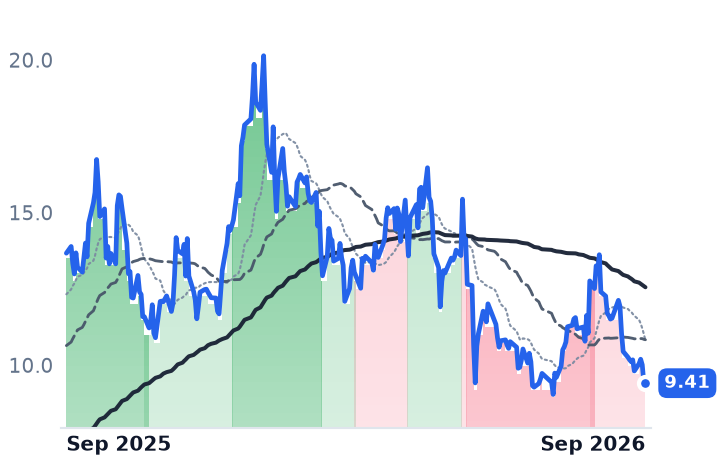
Sixteen days after selling $500m of stock and warrants at $199.64 a unit, Centrus closed at $147.07, leaving all four warrant strikes out of the money. Consensus carries 2026 earnings of $2.55 a share against $3.90 delivered in 2025, and the forward and trailing earnings multiples sit within a point of each other — what no growth looks like. BWX Technologies and Cameco, paid by contract and by the pound, show their damage somewhere else or not at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −24.5% | −51.8% |
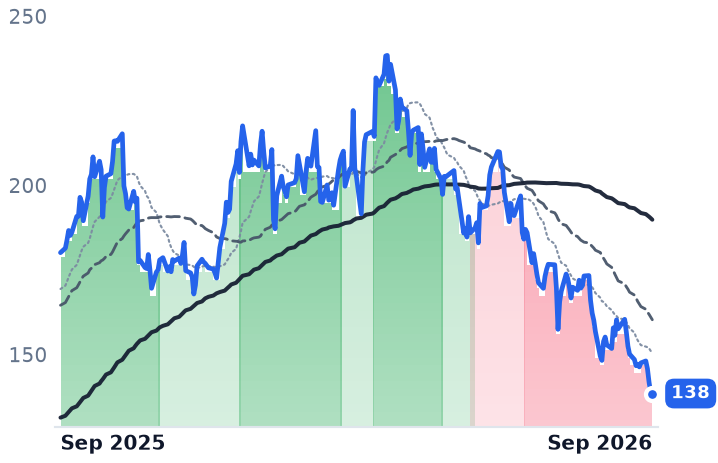
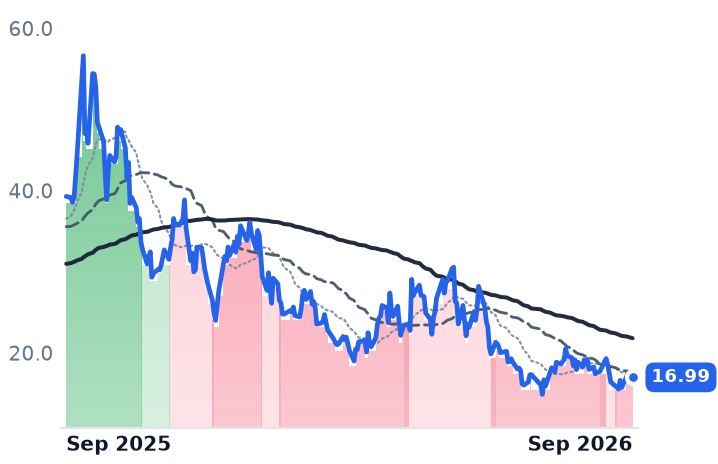
BWXT | BWX Technologies | Naval & Shipbuilding | 🔴 Cont. Bear | −10.8% | −23.1% |
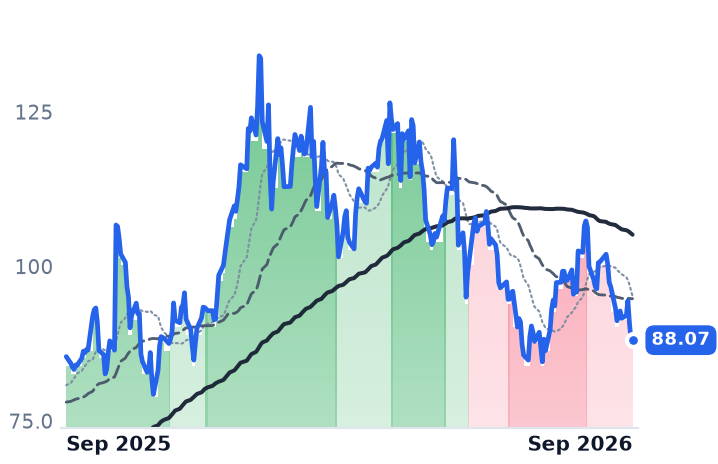
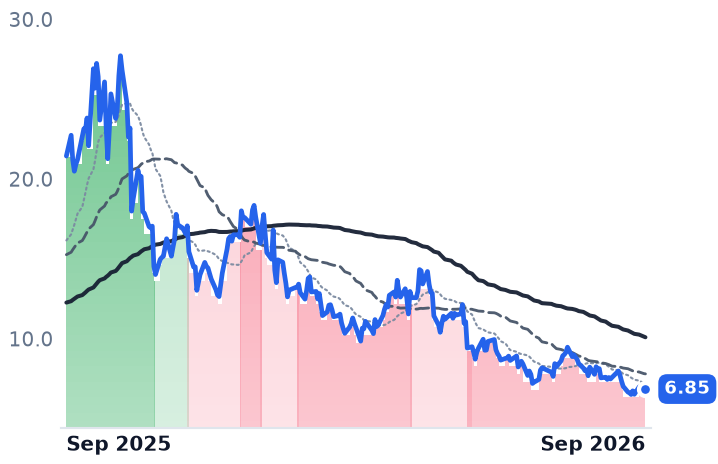
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −17.2% | +3.1% |
| Compared against · context, not the story | |||||
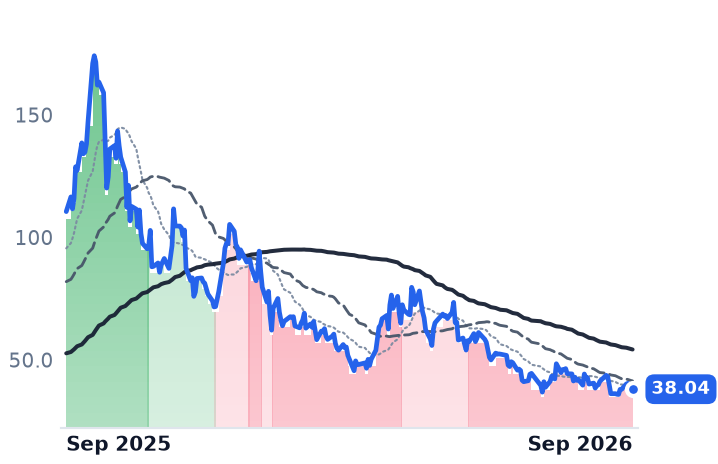
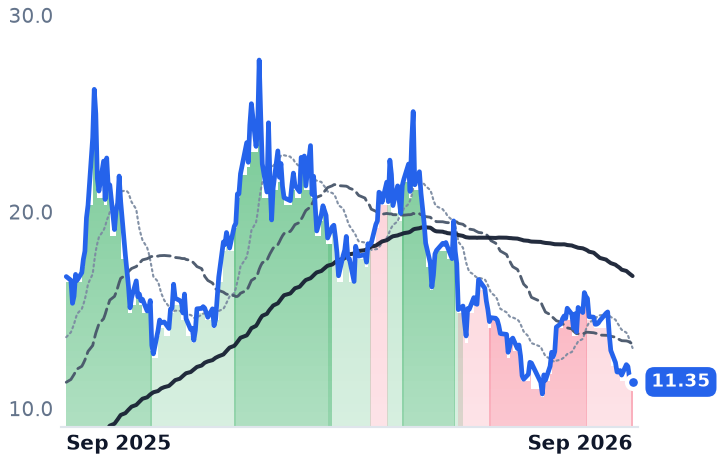
OKLO | Oklo | Emerging & Specialized Energy | 🔴 Cont. Bear | −11.0% | −65.6% |
SMR | NuScale Power | Advanced Nuclear | 🔴 Cont. Bear | −10.8% | −77.4% |
NNE | Nano Nuclear Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −11.6% | −56.8% |
LTBR | Lightbridge | Electrical Equipment & Parts | 🔴 Cont. Bear | −15.7% | −68.1% |
UUUU | Energy Fuels | Uranium | 🔴 Cont. Bear | −27.2% | −32.1% |
UEC | Uranium Energy | Uranium | 🔴 Cont. Bear | −30.9% | −31.2% |
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −14.4% | −11.1% |
URNM | Sprott Uranium Miners ETF | Asset Management | 🔴 Cont. Bear | −18.9% | −16.0% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +16.8% |
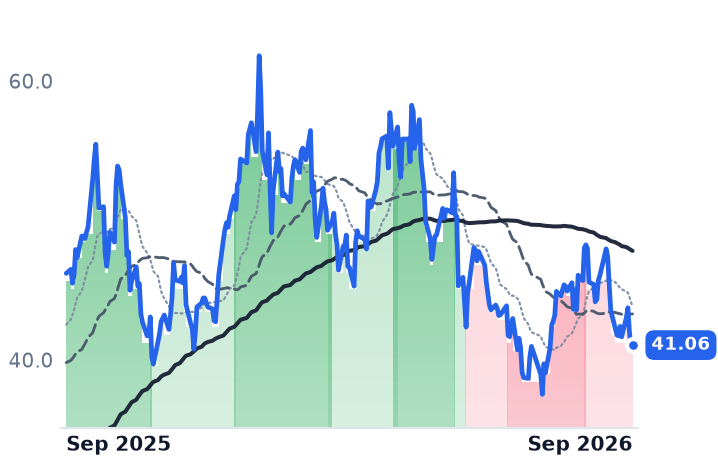
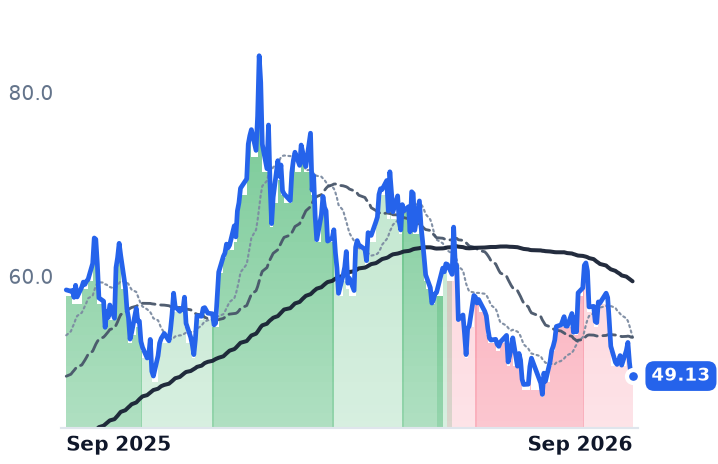
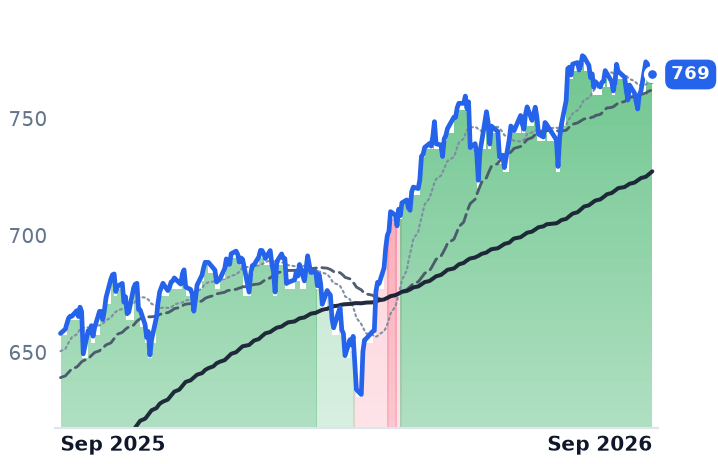
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.8B | 58.6x | 57.8x | 5.9x | 5.9x | 25.3x | 25.4x | 28.8x | -8.0% |
BWXT | $12.7B | 35.7x | 29.2x | 3.6x | 3.3x | 16.4x | 15.1x | 25.5x | 2.5% |
CCJ | $38.4B | 152.3x | 59.1x | 15.6x | 11.1x | 56.6x | 40.1x | 62.8x | 0.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
OKLO | $6.6B | n/m | — | — | — | — | — | n/m | -4.2% |
SMR | $3.0B | n/m | — | 284.6x | 160.7x | — | 762.7x | n/m | -25.5% |
NNE | $1.1B | n/m | — | — | 887.7x | — | — | n/m | -3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LTBR | $258.0M | n/m | — | n/m | — | — | — | n/m | -6.6% |
UUUU | $2.8B | n/m | — | 26.8x | 21.3x | 62.0x | 49.3x | n/m | -3.9% |
UEC | $5.1B | n/m | — | 253.1x | 49.9x | 598.0x | 117.9x | n/m | -2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
URA | $3.9B | — | — | — | — | — | — | — | — |
URNM | $1.1B | — | — | — | — | — | — | — | — |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LEU | Revenue | +5.2% | −0.8% | −10.9% |
| EPS | −43.2% | +13.2% | −23.3% | |
BWXT | Revenue | +20.6% | +9.8% | +7.3% |
| EPS | +24.1% | +11.2% | +11.8% | |
CCJ | Revenue | +1.3% | +12.3% | +8.4% |
| EPS | +3.8% | +70.4% | +24.8% | |
OKLO | Revenue | — | +247.8% | +498.2% |
| EPS | +64.1% | +8.1% | +10.3% | |
SMR | Revenue | −54.8% | +517.4% | +185.1% |
| EPS | −76.8% | +19.4% | −24.8% | |
NNE | Revenue | +1684.0% | +356.5% | +39.0% |
| EPS | −23.4% | +55.2% | +34.3% | |
UUUU | Revenue | +128.1% | +88.3% | +62.7% |
| EPS | −37.3% | −160.5% | +170.0% | |
UEC | Revenue | −61.4% | +301.4% | +159.3% |
| EPS | +50.7% | −74.9% | −447.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On 30 June the Department of Energy let the contract that paid Centrus Energy to produce high-assay low-enriched uranium expire, and replaced it with paid caretaking: a fixed $15.0m for three months of cascade maintenance and material storage, with no enrichment at all. That replacement expires on 30 September, and the department has told the company it "does not currently intend to exercise further options" under the agreement. A 21-month follow-on option exists on paper; no one has exercised it.
Centrus sells separative work units and enriched uranium to nuclear utilities and runs a government-funded engineering arm, and it is the only US-based producer of the fuel grade most advanced-reactor designs require. So the question hanging over the whole enrichment build-out — whether it is being funded or merely announced — now carries a date, and the date is four days out.
What the meters already said
The June quarter showed what losing the production contract costs. Separative work unit volumes fell 23% year over year with average unit cost up 13%, and the government-funded Technical Solutions segment fell 21% to $22.7m. Revenue still grew 14% to $176.1m, but on $53.4m of uranium resales rather than on enrichment work, and operating income fell 69% to $10.4m as gross margin narrowed to 28.3% from 34.9%. March-quarter operating income had already fallen 96%, to $0.8m.
"This was another strong quarter of financial and operational progress for Centrus that included a number of commercial wins for our future enrichment business," chief executive Amir Vexler said in the results release of 5 August, citing "the growing imbalance in uranium enrichment supply and demand."
The market has taken the other side. Consensus puts 2026 earnings at $2.55 a share against $3.90 delivered in 2025, with 2027 revenue expected marginally below 2026. At 57.8x forward earnings versus 58.6x trailing, the multiple pair embeds contraction, not the buildout. And the $500m of stock and warrants priced on 9 September at $199.64 a unit closed at $147.07 on 25 September, 26.3% below issue, with warrant strikes running from $226.86 to $362.98 — every one of them out of the money, over roughly 7m shares.
Paid by contract, paid by the pound
The other two ways to be paid for the same trend are behaving differently. BWX Technologies, which builds naval reactors and fuel for the Navy and the Energy Department alongside commercial nuclear components, ended June with $8.4bn of backlog, up 40%, and raised all four of its 2026 guidance lines on 3 August; in late August the Army named it in the $2.2bn Project Janus microreactor programme. Its shares have de-rated anyway, to 29.2x forward earnings from roughly 46-47x in May. The honest qualifier: reported operating income has fallen year over year for four straight quarters, down 12.2% in the June period, as lower-margin acquired commercial work pulled gross margin to 22.4% from 25.1%.
Cameco's damage is real but sits in the wrong leg. The mining half improved — 2026 realized-price guidance was raised to C$91.00-96.00 a pound from C$85.00-89.00 (Cameco reports in Canadian dollars), and Kazatomprom is cutting about 8m pounds from 2026 output. But its share of Westinghouse swung to a $10m net loss from $126m of earnings a year earlier, taking group net income down 92.1%. At 59.1x forward earnings, the de-rating is working on reactor services, not pounds.
Which part is earned
Over twelve months the selling was rank-ordered by distance from audited cash flow: NuScale down 78.4%, Oklo 71.0%, Centrus 53.4%, against BWXT's 23.9% and Cameco up 2.8%. In the five sessions to 25 September it inverted — NANO Nuclear up 8.0% and NuScale 3.7% while BWXT fell 6.1% and Cameco 3.9%. The newest leg is landing on the companies with earnings, which the label-repricing story does not explain; a higher long bond, with the 30-year Treasury yield above 5.5% for the first time since 2004, discounts 2033 reactor cash flows harder than it touches a 2026 order book.
So two of the three de-ratings are earned and one is not. Centrus's shrinking volumes and lapsed contract justify the price; Cameco's justifies itself through Westinghouse while the pounds get better; BWXT's rising backlog and raised guidance explain none of its own decline, only its falling margin mix does part of it. Holtec's cancelled $900m listing this month says the primary market for new nuclear capital narrowed at the same time.
The one federal contract that ever paid Centrus to enrich fuel now pays it to guard the building, and that stops in four days.