

A Record Diesel Price Hit J.B. Hunt for $10m a Quarter; Landstar and XPO Grew Volumes
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
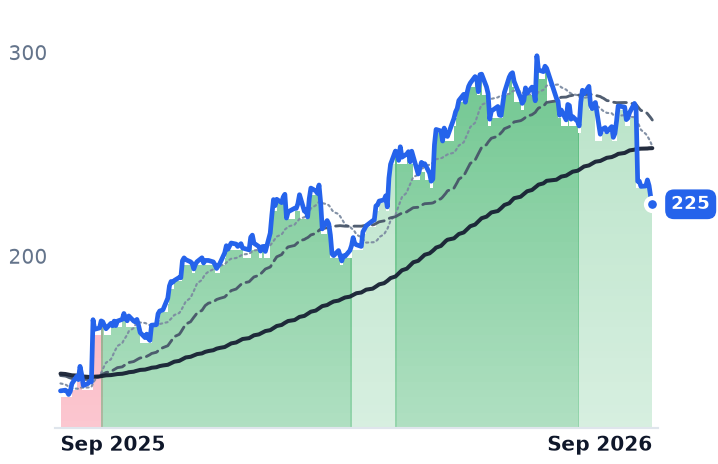
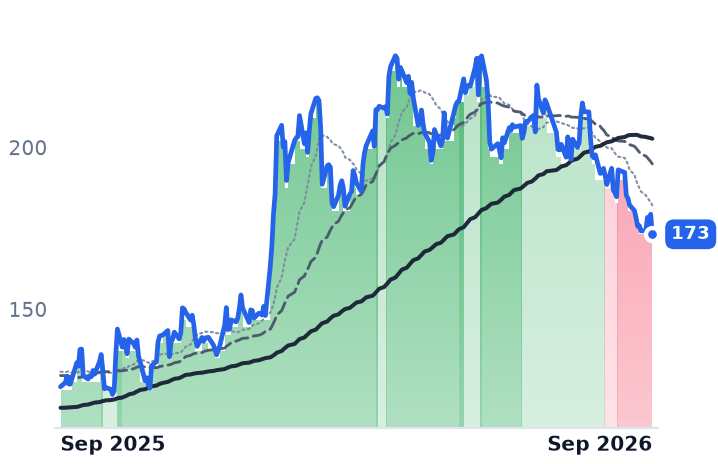
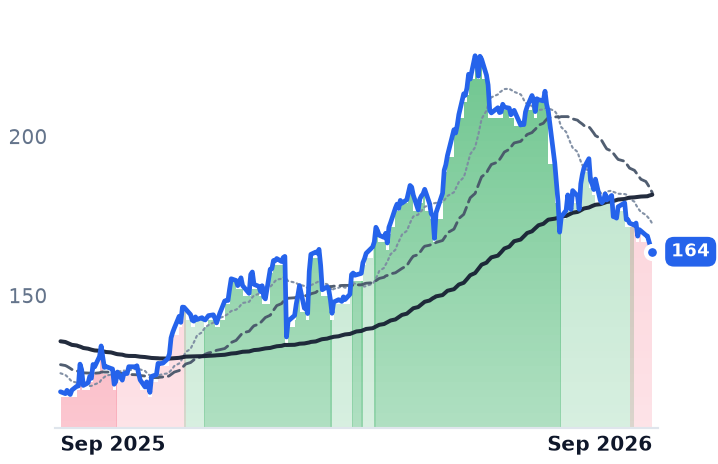
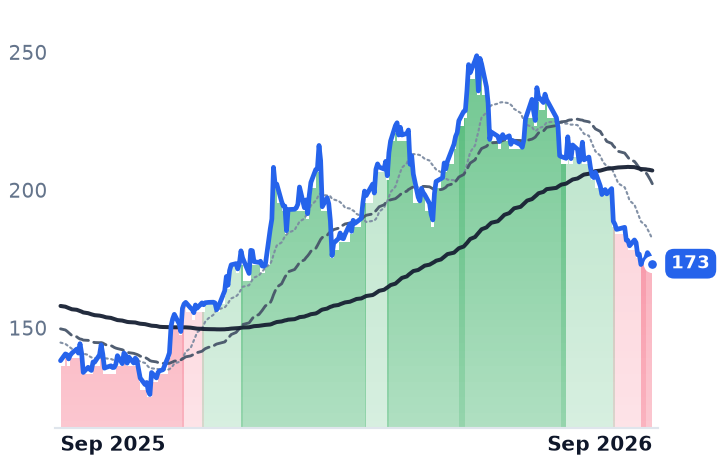
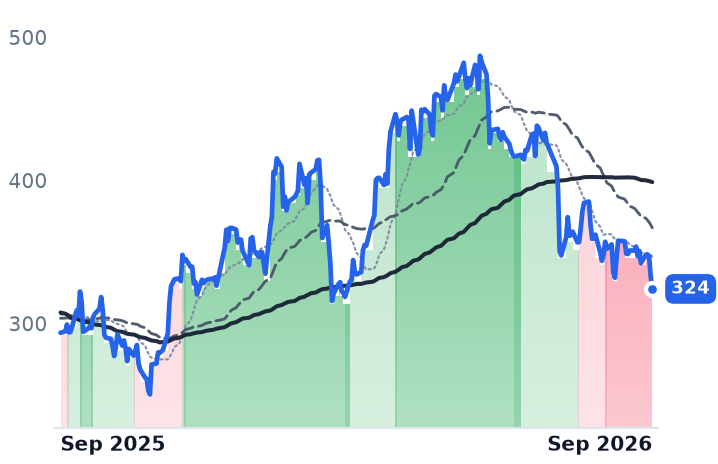
Freight carriers sell at prices fixed months ahead and buy fuel at spot, and the widest diesel spike since 2022 arrived in September while the industry was supposed to be entering a capacity-driven rate upturn. J.B. Hunt guided third-quarter profit 5% to 10% below the second quarter on fuel and driver cost; the shares fell 13% the next day and the whole complex followed, with thirteen of seventeen listed freight names down between 6.8% and 15.3% in thirty days.
The operating meters went the other way. J.B. Hunt moved a record 578,072 intermodal loads, up 10%, though revenue per load excluding fuel rose just 1% — bid season was conceded. XPO printed a 79.9% adjusted operating ratio, its best ever and five quarters ahead of its own target, then accelerated to 5.7% shipment growth in August. Landstar's loads rose 1.9% with gross margin flat at 9.2%. The cost shock is real; the demand break is not visible yet.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
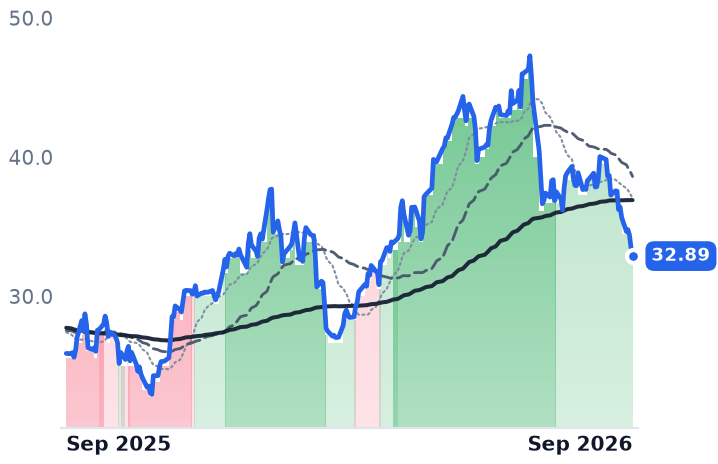
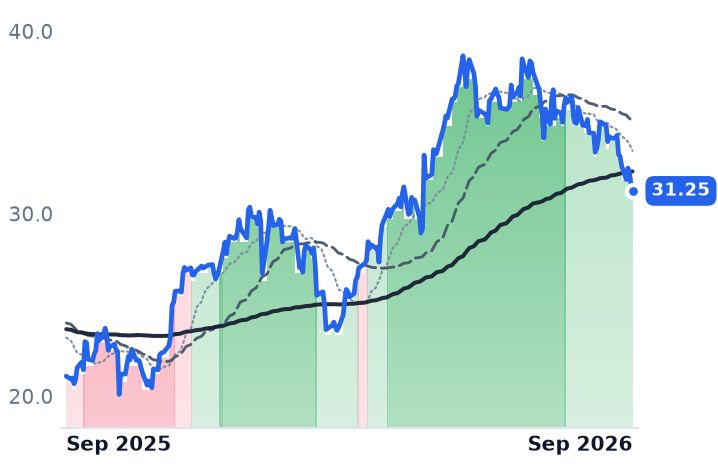
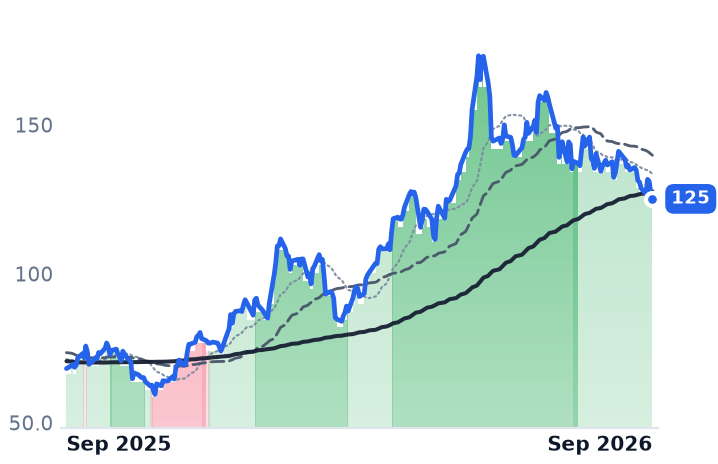
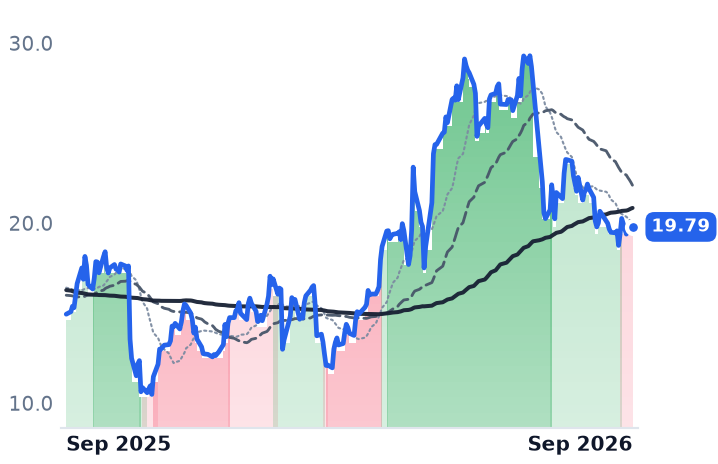
JBHT | J.B. Hunt Transport Services | Truckload & LTL | 🟢 Cont. Bull | −14.3% | +68.5% |
XPO | XPO Logistics | Truckload & LTL | ⚠️ Emerging Bear | −9.5% | +37.4% |
LSTR | Landstar System | Truckload & LTL | 🟢 Cont. Bull | −10.0% | +36.8% |
| Compared against · context, not the story | |||||
HUBG | Hub | Truckload & LTL | ⚠️ Emerging Bear | −24.4% | −11.8% |
ODFL | Old Dominion Freight Line | Less-Than-Truckload (LTL) | 🟢 Cont. Bull | −13.4% | +25.5% |
SAIA | Saia | Less-Than-Truckload (LTL) | ⚠️ Emerging Bear | −9.2% | +10.4% |
UNP | Union Pacific | Class I Railroads | 🟢 Cont. Bull | −11.2% | +17.7% |
NSC | Norfolk Southern | Class I Railroads | 🟢 Cont. Bull | −10.6% | +6.2% |
CSX | CSX | Class I Railroads | 🟢 Cont. Bull | −9.1% | +38.5% |
FDX | FedEx | Parcel & Express Delivery | 🔴 Cont. Bear | −14.6% | +21.3% |
UPS | United Parcel Service | Parcel & Express Delivery | ⚠️ Emerging Bear | −11.4% | +15.8% |
KNX | Knight-Swift Transportation | Less-Than-Truckload (LTL) | 🟢 Cont. Bull | −7.9% | +61.7% |
WERN | Werner Enterprises | Truckload & Dedicated | 🟢 Cont. Bull | −14.2% | +27.0% |
SNDR | Schneider National | Less-Than-Truckload (LTL) | 🟢 Cont. Bull | −11.1% | +48.1% |
ARCB | ArcBest | Less-Than-Truckload (LTL) | 🟢 Cont. Bull | −9.4% | +83.5% |
RXO | RXO | Freight Brokerage & Logistics | 🟢 Cont. Bull | −10.7% | +32.5% |
CHRW | C.H. Robinson Worldwide | Freight Brokerage & Forwarding | ⚠️ Emerging Bear | −2.9% | +12.4% |
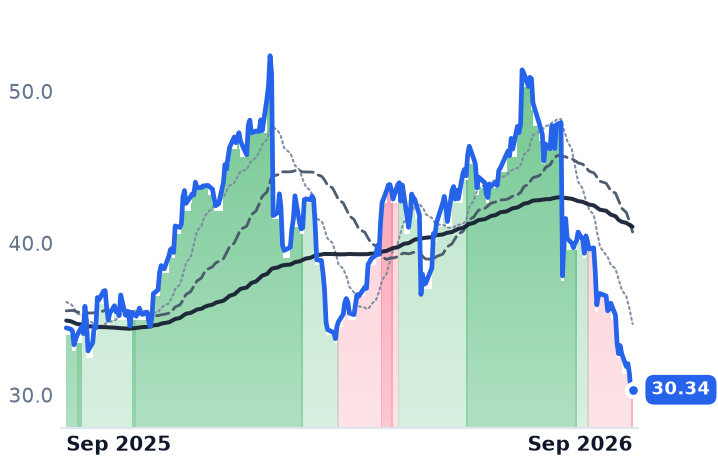
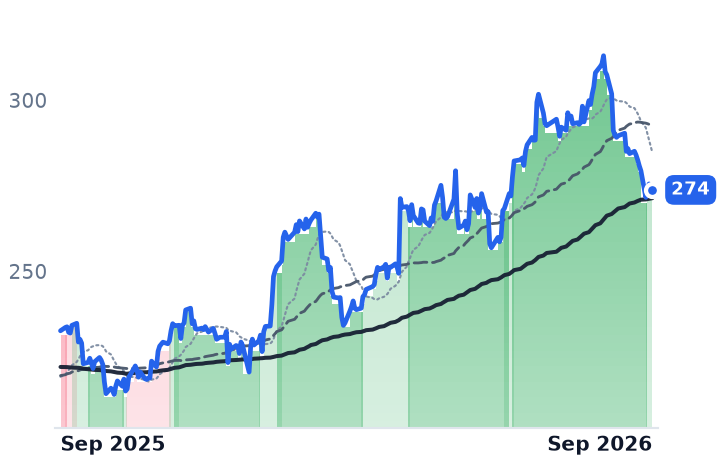
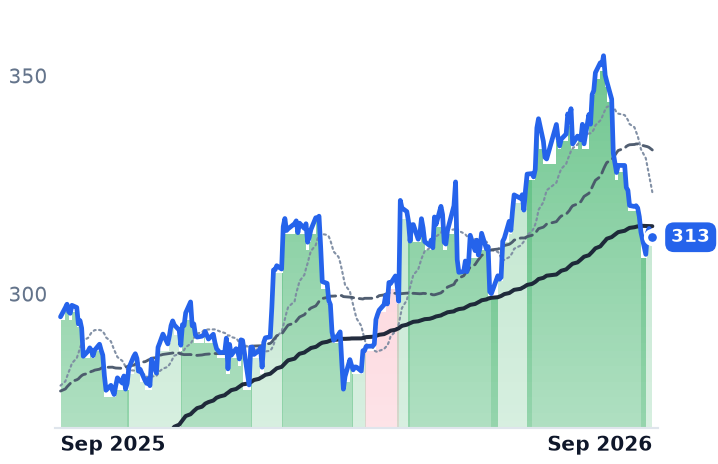
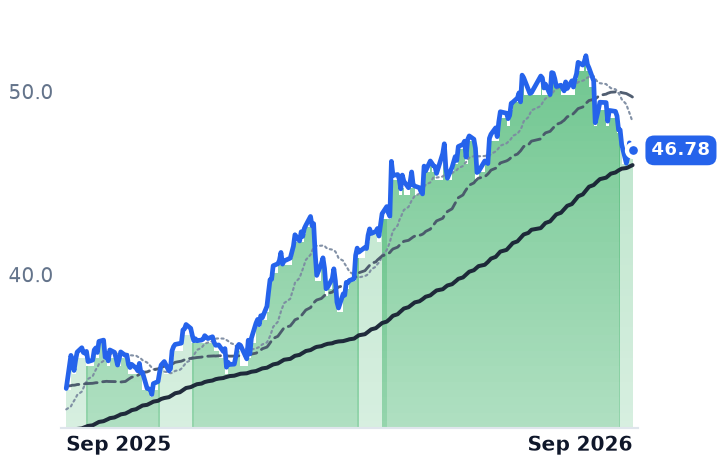
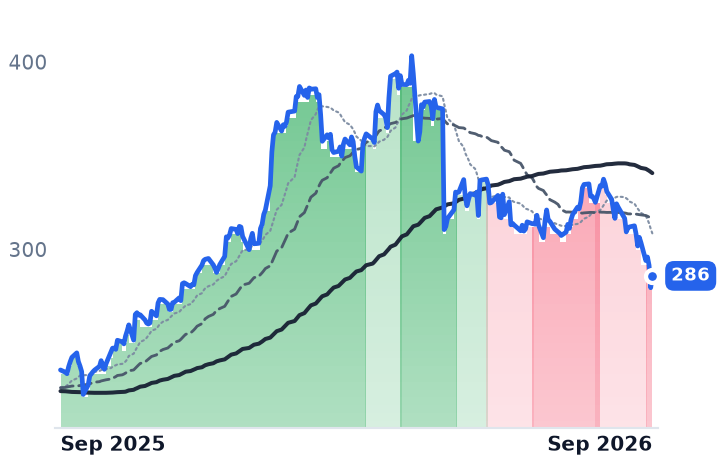
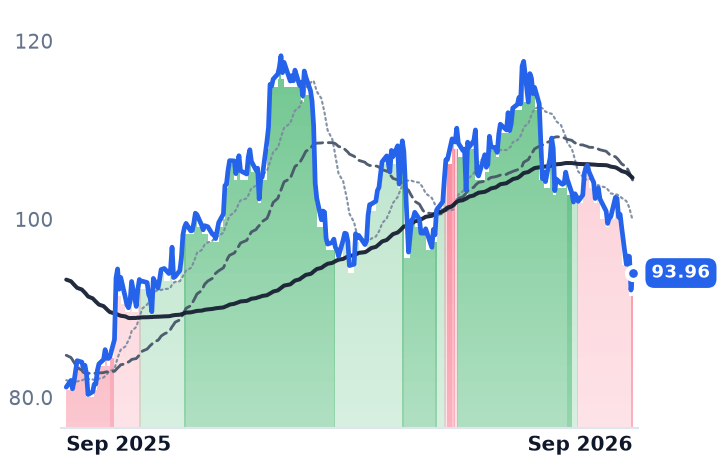
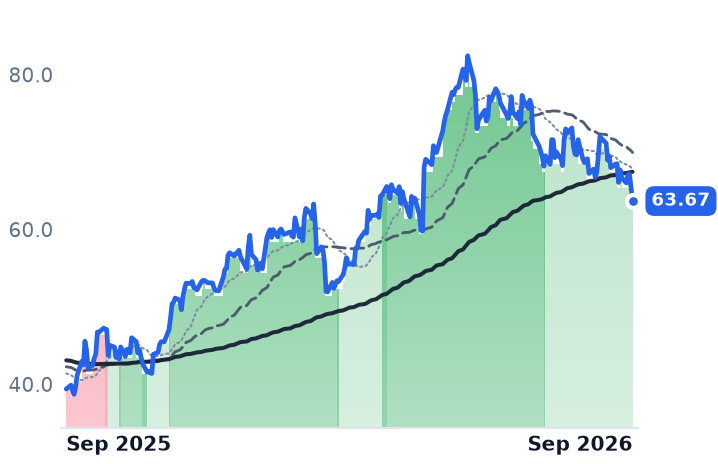
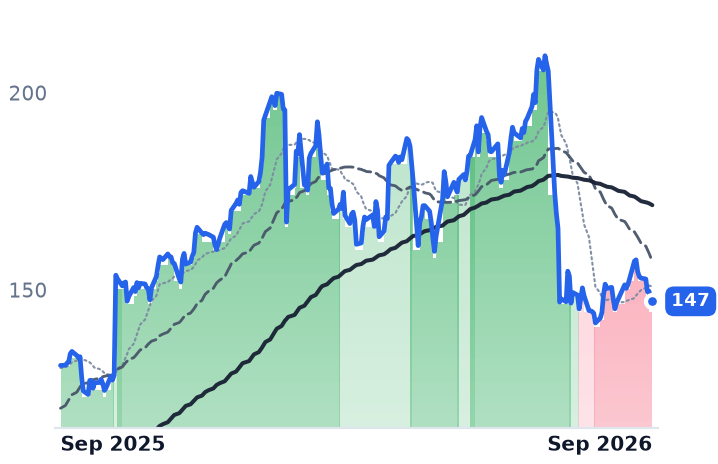
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
JBHT | $21.2B | 32.0x | 29.8x | 1.7x | 1.5x | 10.2x | 9.5x | 13.6x | 5.2% |
XPO | $20.3B | 50.5x | 31.5x | 2.4x | 2.2x | 18.5x | 17.6x | 18.6x | 2.9% |
LSTR | $5.6B | 42.4x | 27.7x | 1.1x | 1.0x | 7.2x | 6.5x | 22.3x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HUBG | $1.8B | 22.5x | 31.4x | 0.7x | 0.5x | 1.2x | 0.9x | 9.1x | 6.6% |
ODFL | $36.4B | 33.6x | 30.0x | 6.5x | 6.1x | 20.5x | 19.4x | 19.9x | 3.1% |
SAIA | $8.9B | 32.1x | 29.4x | 2.6x | 2.5x | 16.3x | 15.3x | 14.4x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UNP | $162.8B | 22.2x | 21.0x | 6.4x | 6.1x | 14.1x | 13.3x | 14.4x | 4.0% |
NSC | $69.5B | 26.4x | 23.8x | 5.5x | 5.2x | 10.3x | 9.8x | 15.7x | 5.5% |
CSX | $87.3B | 27.2x | 23.5x | 6.0x | 5.7x | 11.0x | 10.5x | 15.8x | 5.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FDX | $89.7B | 20.4x | 19.0x | 1.0x | 1.0x | 4.0x | 3.9x | 11.7x | 4.9% |
UPS | $84.1B | 16.0x | 13.9x | 1.0x | 0.9x | 5.2x | 5.1x | 9.7x | 5.4% |
KNX | $11.2B | 330.0x | 37.3x | 1.5x | 1.4x | 6.0x | 5.6x | 13.7x | 11.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WERN | $2.2B | n/m | 40.8x | 0.7x | 0.6x | 8.7x | 7.4x | 10.1x | -2.0% |
SNDR | $5.6B | 57.1x | 35.0x | 1.0x | 0.9x | 6.7x | 6.4x | 9.5x | 7.6% |
ARCB | $2.7B | 49.0x | 23.8x | 0.7x | 0.6x | 16.5x | 15.3x | 14.1x | 6.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RXO | $3.1B | n/m | 439.8x | 0.5x | 0.5x | 3.1x | 2.9x | 417.8x | -0.5% |
CHRW | $19.3B | 32.7x | 26.6x | 1.2x | 1.1x | 14.4x | 13.8x | 21.3x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
JBHT | Revenue | +14.3% | +9.7% | +8.4% |
| EPS | +25.3% | +32.6% | +19.1% | |
XPO | Revenue | +11.5% | +5.3% | +6.6% |
| EPS | +52.2% | +18.8% | +21.2% | |
LSTR | Revenue | +16.6% | +12.0% | +9.8% |
| EPS | +30.7% | +29.4% | +14.6% | |
HUBG | Revenue | +2.5% | +8.3% | +8.6% |
| EPS | −47.1% | +81.9% | +42.0% | |
ODFL | Revenue | +7.8% | +7.9% | +9.0% |
| EPS | +21.2% | +14.2% | +15.3% | |
SAIA | Revenue | +12.2% | +7.5% | +8.3% |
| EPS | +21.9% | +25.3% | +20.7% | |
UNP | Revenue | +9.3% | +5.1% | +12.5% |
| EPS | +11.9% | +8.4% | +10.9% | |
NSC | Revenue | +8.5% | +4.3% | +4.6% |
| EPS | +8.0% | +10.5% | +9.5% | |
CSX | Revenue | +7.6% | +5.0% | +3.7% |
| EPS | +22.7% | +13.3% | +10.4% | |
FDX | Revenue | +7.1% | +5.0% | +4.7% |
| EPS | +10.1% | +14.5% | +17.3% | |
UPS | Revenue | +2.1% | +3.9% | +3.2% |
| EPS | +2.7% | +11.6% | +8.2% | |
KNX | Revenue | +7.0% | +7.2% | +6.2% |
| EPS | +39.5% | +75.7% | +27.9% | |
WERN | Revenue | +19.7% | +7.0% | +4.0% |
| EPS | +1338.1% | +111.6% | +33.8% | |
SNDR | Revenue | +4.2% | +5.9% | +4.8% |
| EPS | +31.1% | +65.3% | +26.8% | |
ARCB | Revenue | +8.8% | +6.3% | +5.8% |
| EPS | +37.5% | +54.9% | +25.6% | |
RXO | Revenue | +8.2% | +7.2% | +6.9% |
| EPS | −301.5% | +1046.4% | +22.9% | |
CHRW | Revenue | +3.7% | +6.2% | +7.1% |
| EPS | +23.8% | +18.6% | +9.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The most expensive diesel ever recorded in the United States landed in September on carriers that had already sold most of this year's capacity at prices set in the spring. J.B. Hunt Transport Services, which moves freight for North American shippers through intermodal containers, dedicated fleets, brokerage and truckload, was first to put a number on it: chief financial officer Brad Delco told the Morgan Stanley Laguna Conference on 15 September that third-quarter profit would likely run 5% to 10% below the second quarter, on close to $10m of extra fuel and about $25m of incremental driver expense, with recent swings in fuel making it hard for the surcharge formula to keep up. The shares fell a little more than 13% the next day, to $236.73, as reported by the Arkansas Democrat-Gazette; the account is a paraphrase of his remarks rather than a transcript.
What matters beyond one quarter is that the entire bull case for freight equities this year was supply-side — tractors leaving the market, rates firming, a fourth year of recession ending. A cost shock that carriers cannot bill back for two quarters looks, on a price chart, exactly like that case being cancelled. It is worth separating the two, because the three companies here are paid in three incompatible ways, and all three published volume and price data after the diesel move began.
The shock, dated
The Energy Information Administration's weekly on-highway average reached $5.967 a gallon in the week of 7 September, passing the $5.810 record of June 2022 — and it did so on a refining crunch with crude near $100 a barrel, not a crude shortage. Pump averages were reported around $6.31 in mid-September, roughly 70% above a year earlier. Intermodal contracts reprice on a lag of about two quarters, a structure that absorbs drift and fails on spikes. The selling was indiscriminate: over the thirty days to 25 September, Old Dominion fell 13.2%, Union Pacific 12.5% and FedEx 15.3%, thirteen of seventeen freight names down more than 6.8%.
Three meters, one direction
J.B. Hunt moved 578,072 intermodal loads in the June quarter, up 10% — a record, and its first double-digit volume quarter in more than a decade, with intermodal operating income up 58% to $150.9m. The concession is in the price line: revenue per load excluding fuel surcharge rose only 1%. Bid season was given away, and the margin now rides on volume and cost discipline. At 32.0x trailing earnings against 42.0x at the end of May, and 29.8x forward on consensus 2026 earnings of $7.58 a share, the de-rating is partly earned — but a 24% fall from its 52-week high is a steep price for one guided quarter.
XPO, a pure-play less-than-truckload carrier with 299 service centers, printed the number its own plan did not expect until late 2027: an adjusted operating ratio of 79.9%, three percentage points better than a year earlier, with tonnage per day up 1.0% and yield excluding fuel up 4.4%. "We accelerated our performance significantly in the second quarter, delivering 56% year-over-year growth in adjusted diluted EPS," chief executive Mario Harik said on 30 July. Then August tonnage per day rose 3.7% on shipments up 5.7%, disclosed 3 September — accelerating as the shares fell. It trades at 50.5x trailing earnings, down from 82.1x in early May, and 31.5x forward.
Landstar System owns almost no trucks and employs 1,378 people; independent agents and owner-operators take a fixed percentage of every load, so its gross margin barely moves and its loadings are the cleanest volume read available. It hauled 510,250 truckloads, up 1.9%, at $2,614 revenue per load against $2,234, with gross margin of 9.2% against 9.0%. Its capacity is growing again — a net 68 trucks added, the best since early 2022 — and the reason is legal: after the Supreme Court's Montgomery ruling exposed freight brokers to state negligent-hiring claims, small brokerages are consolidating onto larger platforms. "Inbound interest and conversations with potential new agents has accelerated since the Montgomery decision was released," chief executive Frank Lonegro said on the 28 July call, adding that July revenue per load ran about 26% above a year earlier. At 27.7x forward earnings against 42.4x trailing, Landstar is cheaper than itself on a recovery from trough profits, with enterprise value still 22.3x EBITDA.
What the move earns
Industry truckload volumes were running 4-5% below year-ago levels through September, with spot rates near $3.40 a mile and tender rejections at their highest since 2022. Against that, growth at these three is share taken, not a cycle joined — and Hub Group, the intermodal peer that never joined the year-long advance, is the counterweight: consensus has its 2026 earnings at $0.97 a share against $1.83 last year, while J.B. Hunt's rise 25%.
So the de-rating prices a cost shock as though it were a demand break, and only one piece of it is confirmed by the companies' own meters: J.B. Hunt's flat ex-fuel rate. Everything else — tonnage, shipments, loadings, operating ratio — improved into the drawdown. If diesel holds, the two-quarter repricing lag that took the quarter away hands most of it back by early 2027; the genuine risk is the other one, that volumes roll over before price catches up and the supply-side case dies of no demand. The rail backdrop that sets J.B. Hunt's purchased-transportation cost stays open either way: the Surface Transportation Board declined on 18 September to summarily reject the Union Pacific-Norfolk Southern application, with opening comments due 18 November.
J.B. Hunt reports on 15 October and XPO on 29 October. One of them has already told the market how bad the fuel line looks; the other has spent three weeks publishing evidence that its freight is still growing, and has been marked down for the first one's problem.