

Clorox's $2.25bn Purell Deal Lifted Leverage to 3.6x as Dividends Outran Free Cash Flow
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The distortion that wrecked Clorox's fiscal year is finished in the accounts, and the shares have gone on falling to a fresh low. Organic sales fell 13% in the year to June 2026, but roughly 13.5 points of that was lapping cases retailers pre-bought ahead of a US software cutover — a timing wedge, and US consumption was back to flat by the June quarter.
What is left is harder. Gross margin fell 290 basis points for the year to 42.3%, management guided to more than $200m of fiscal 2027 inflation, and the $2.25bn debt-funded purchase of Purell maker GOJO left leverage near 3.6x earnings before interest, taxes, depreciation and amortization. Reported operating cash flow of $612m sat barely above the dividend bill. Cash conversion, not shipments, now decides whether a near-6% yield on a 49-year raising streak is value or warning. Church & Dwight, on the same shelves, raised guidance twice.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
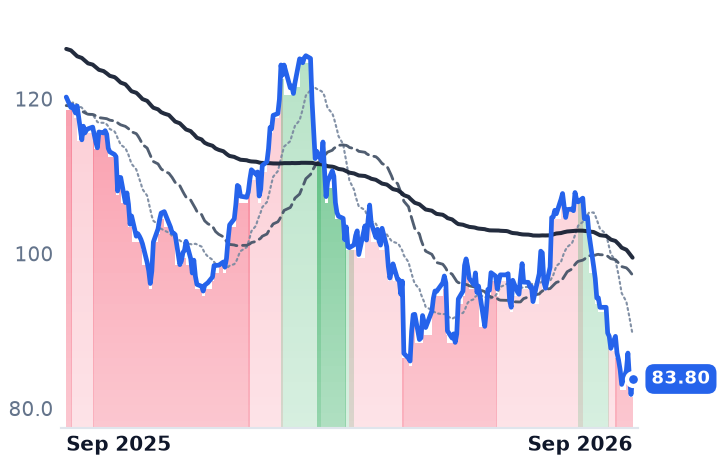
CLX | The Clorox | Home Care & Cleaning | 🔴 Cont. Bear | −20.0% | −30.3% |
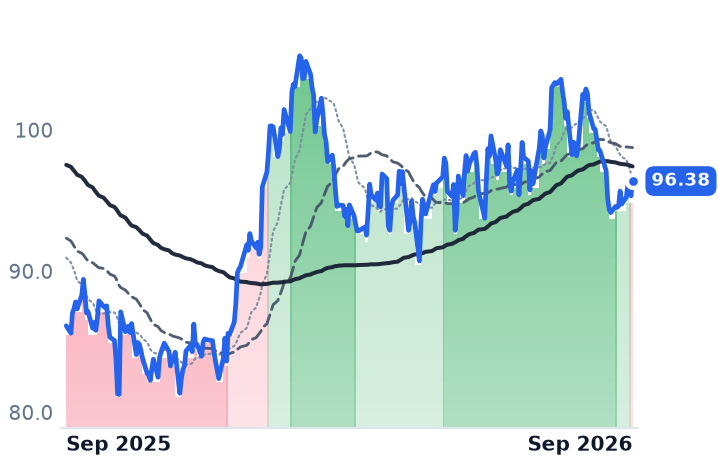
CHD | Church & Dwight | Home Care & Cleaning | 🌱 Emerging Bull | −6.0% | +11.9% |
| Compared against · context, not the story | |||||
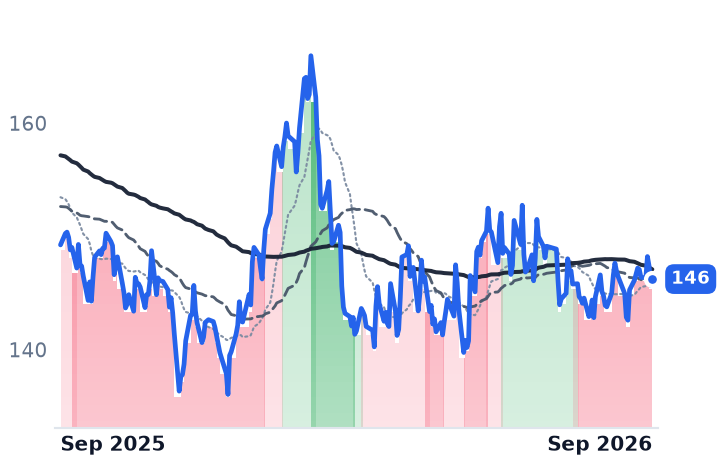
PG | The Procter & Gamble | Beauty & Personal Care | 🔴 Cont. Bear | +1.6% | −2.0% |
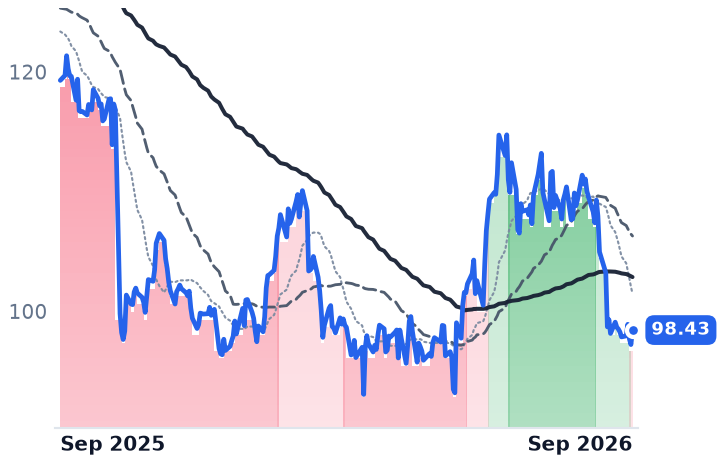
KMB | Kimberly-Clark | Tissue & Absorbent Products | 🌱 Emerging Bull | −10.5% | −17.5% |
CL | Colgate-Palmolive | Oral & Specialty Health | 🟢 Cont. Bull | −6.0% | +10.2% |
KVUE | Kenvue | Oral & Specialty Health | 🟢 Cont. Bull | −7.3% | +12.4% |
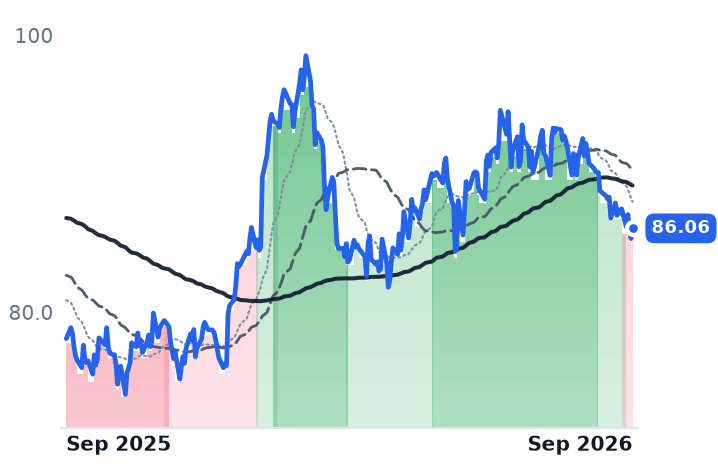
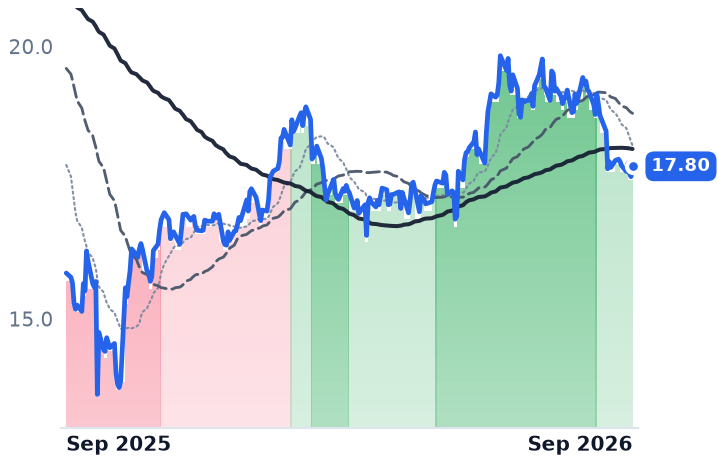
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLX | $10.1B | 17.4x | 14.5x | 1.5x | 1.3x | 3.6x | 3.1x | 16.8x | 4.0% |
CHD | $22.8B | 30.9x | 25.5x | 3.7x | 3.7x | 8.0x | 8.0x | 20.5x | 4.9% |
PG | $347.6B | 21.7x | 21.0x | 4.0x | 3.9x | 8.0x | 7.8x | 17.5x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
KMB | $32.7B | 16.7x | 13.3x | 2.0x | 2.0x | 5.4x | 5.4x | 12.5x | 7.8% |
CL | $70.5B | 33.9x | 23.2x | 3.4x | 3.3x | 5.6x | 5.5x | 19.7x | 5.3% |
KVUE | $32.9B | 20.2x | 14.4x | 2.1x | 2.1x | 3.7x | 3.6x | 12.4x | 5.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLX | Revenue | −5.1% | +14.2% | +2.4% |
| EPS | −21.6% | +4.9% | +7.9% | |
CHD | Revenue | +0.5% | +4.2% | +4.0% |
| EPS | +8.0% | +7.1% | +7.2% | |
PG | Revenue | +3.5% | +1.8% | +2.9% |
| EPS | +1.4% | +1.5% | +6.0% | |
KMB | Revenue | +0.9% | +2.6% | +2.7% |
| EPS | −1.4% | +0.3% | +7.6% | |
CL | Revenue | +5.9% | +3.3% | +3.6% |
| EPS | +4.1% | +5.4% | +7.5% | |
KVUE | Revenue | +4.1% | +2.4% | +3.3% |
| EPS | +14.9% | +6.3% | +5.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Clorox spent fiscal 2026 explaining an inventory swing it caused itself. Before replacing the US software that turns a retailer's purchase order into a truckload, its largest customers pre-bought stock to protect shelf availability, then ran that stock down instead of reordering. Reported organic sales fell 13% for the year to June, of which about 13.5 percentage points was the lapping of those pulled-forward shipments, the company said — and US consumption was back to flat by the June quarter.
That wedge has closed, and the shares have fallen roughly another tenth since late August to a 52-week low of $82.47, against a $128.90 high. What the market is pricing now is not shipments. It is the cost line and the balance sheet of a company whose entire shareholder case is a dividend it has raised for 49 consecutive years.
The shortfall was one quarter, the margin damage was all of them
The drawdown is localized: revenue fell 18.9% in the September 2025 quarter and then moved barely at all — down 0.8% in December, up 0.1% in March, down 2.0% in June. Profitability is the part that did not normalize. Gross margin fell 290 basis points for the full year, to 42.3%, and in the June quarter it fell 521 basis points to 41.3%. Diluted earnings came in at $4.81 a share against $6.52.
Fiscal 2027 guidance concedes the rest. Net sales are guided up 13% to 14%, but roughly 9.5 points of that is the GOJO acquisition and more than 3.5 points of the 3.5%-to-4.5% organic figure is pure arithmetic from lapping last year's drawdown; strip both and underlying growth is flat to slightly up. Gross margin is guided roughly flat at about 42% because more than $200m of inflation — "more than double our historical range" — eats the cost savings. "We expect the operating environment to remain challenging, with continued cost volatility and a value-seeking consumer," Chair and Chief Executive Linda Rendle said of fiscal 2027 in the 3 August results release. At the Boston Global Staples Conference, management said it will take a straight price increase on Glad trash bags, the part of the portfolio most exposed to private label, while conceding it does not know how competitors will respond.
The dividend and the cash that has to fund it
Clorox reported fiscal 2026 net cash from operations of $612m, 9.1% of sales, and an adjusted free cash flow of $881m that adds back a $476m venture-termination payment. On the reported basis, free cash flow was closer to $405m — against roughly $600m paid out in dividends. The board still raised the quarterly rate to $1.25, lifting the annualized payout to $5.00 and the yield to near 6% at the September price. Fiscal 2027 free cash flow is guided to 11%-13% of net sales, about $840m to $990m on guided sales, which would cover the payout roughly 1.4 to 1.6 times. It has to, because the April purchase of GOJO Industries for $2.25bn in cash left leverage at about 3.6x earnings before interest, taxes, depreciation and amortization, against a stated target near 2.5x by the end of 2027.
The shares now change hands at 14.5 times forward earnings against 17.4 times trailing and a history above 20x, and 16.8 times enterprise value to the same earnings measure with the acquisition debt aboard. Consensus fiscal 2027 earnings of $5.79 sit inside management's own $5.70-$6.00 range, so estimates have been cut to meet guidance rather than left hanging above it. Brokers have followed the price down: Wells Fargo cut its target to $90 from $102 on 11 September and Barclays moved to $84.
Not the category
Staples sold off generally in September — 14 of 18 large US names fell over the thirty days to 25 September while the S&P 500 barely moved, the likelier reading being rotation out of defensives as long Treasury yields pushed higher. But Clorox's 20% fall is about twelve points worse than the group's middle, and the two obvious comparisons refuse to cooperate. Procter & Gamble, which sells Tide and Dawn into the same aisles, grew revenue 3.3% to $87.0bn in the year to June and trades near 21 times forward earnings. Church & Dwight, owner of Arm & Hammer, OxiClean and TheraBreath, grew organic sales 5.8% in the June quarter on 4.3% volume, widened gross margin by 240 basis points and raised its 2026 outlook twice; it is up over the past twelve months and trades above 25 times forward earnings. Chief Executive Rick Dierker called the company's "evergreen model" intact at the Barclays staples conference on 9 September. Household cleaning demand is not contracting; Clorox's discount of roughly a third to Procter & Gamble is its own.
So the earnings decline is earned and largely explained: a self-inflicted shipment gap plus real input inflation, with cleaning holding share for an eighth consecutive quarter while Fresh Step, Glad and Kingsford do not. What the last month added is not an operating fact but a financing one — a levered balance sheet and a payout that reported cash flow did not fund last year. At 11% of sales, the guided cash conversion makes the September selloff look like an overshoot; at fiscal 2026's 9%, the yield is the market telling you the streak is the thing at risk.
The first quarter of the guided year is the one where last year's drawdown flatters the sales comparison automatically. The cash line gets no such help.