

Novartis's Failed Myotonia Trial Erased a Third of Dyne Therapeutics' Market Value
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A company with no revenue lost roughly $1.5bn of market value this month on a trial run by someone else. Novartis disclosed on 8 September that del-desiran missed its primary endpoint in myotonic dystrophy type 1 — change in video hand opening time at six months — the same measure Dyne Therapeutics' own registrational readout, due in the first quarter of 2027, will be judged on.
Dyne holds about $1.3bn of cash including a July offering that raised roughly $405m, leaving some $1.7bn of its value resting on that readout and a 21 January 2027 decision date in Duchenne muscular dystrophy. The eight-stock Barron's takeout list Dyne sits in is down 15.4% over thirty days, but acquisition appetite is not what broke: biopharma mergers ran 80 deals in the first half of 2026 against 50 in all of 2025.
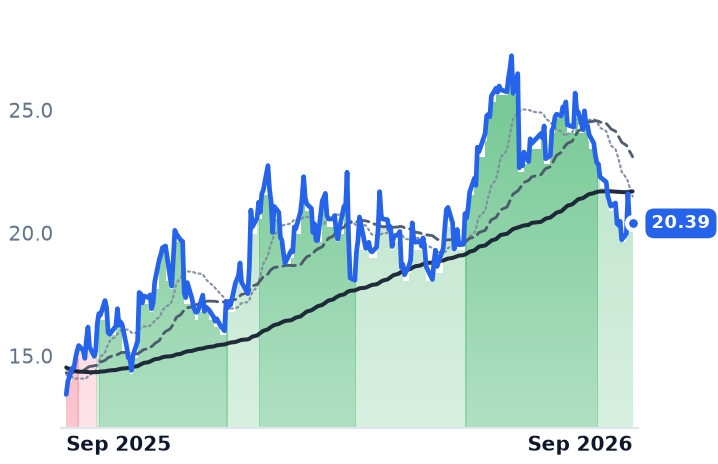
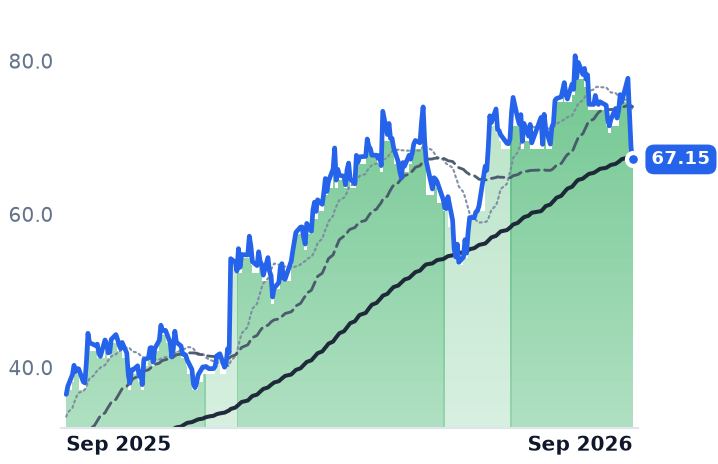
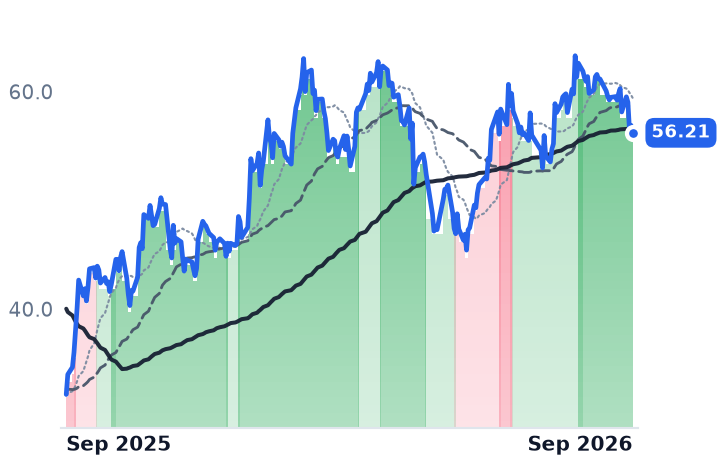
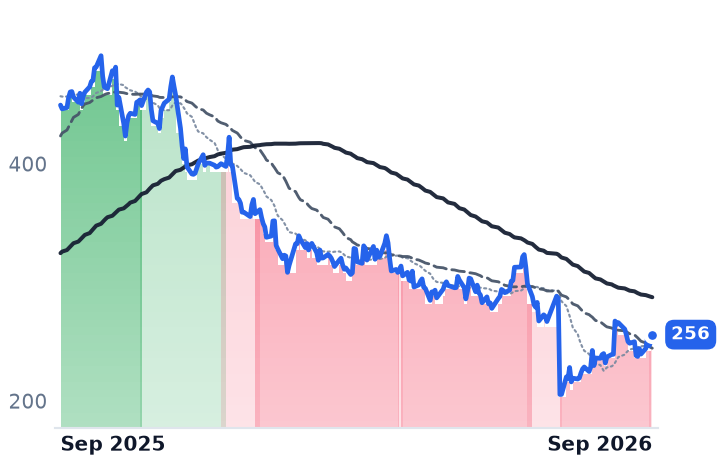
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
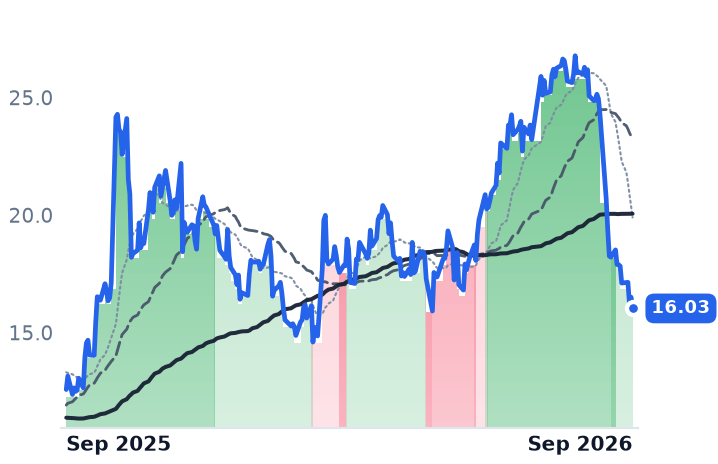
DYN | Dyne Therapeutics | Gene Therapy & Cell Therapy | 🟢 Cont. Bull | −38.1% | +27.4% |
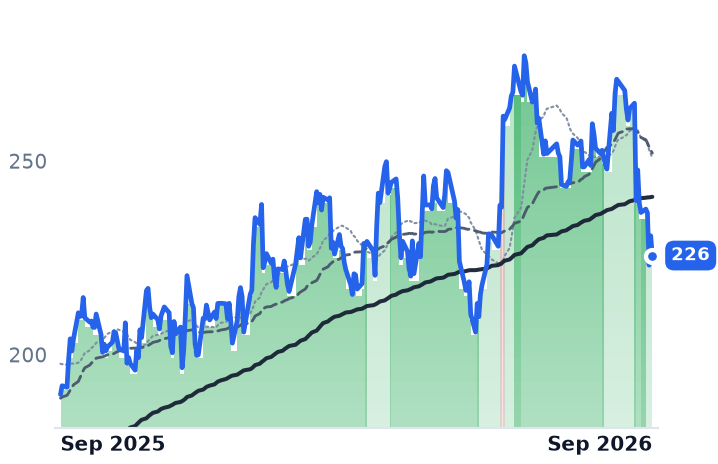
ASND | Ascendis Pharma A/S | Rare Genetic & Metabolic Diseases | 🟢 Cont. Bull | −10.1% | +18.9% |
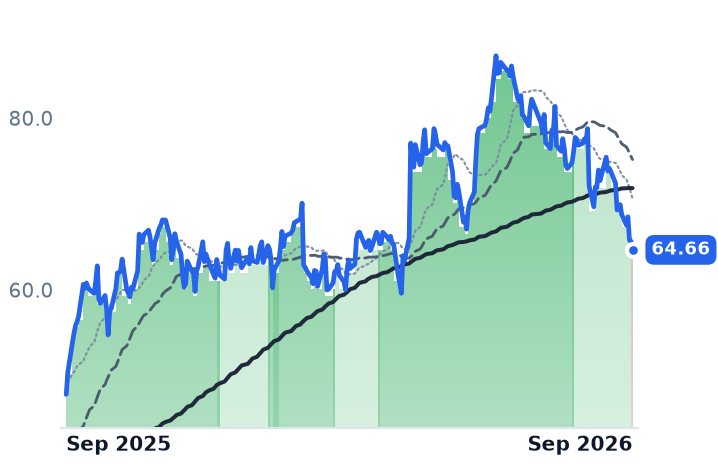
CYTK | Cytokinetics, Incorporated | CNS & Neurological | 🟢 Cont. Bull | −16.4% | +35.2% |
| Compared against · context, not the story | |||||
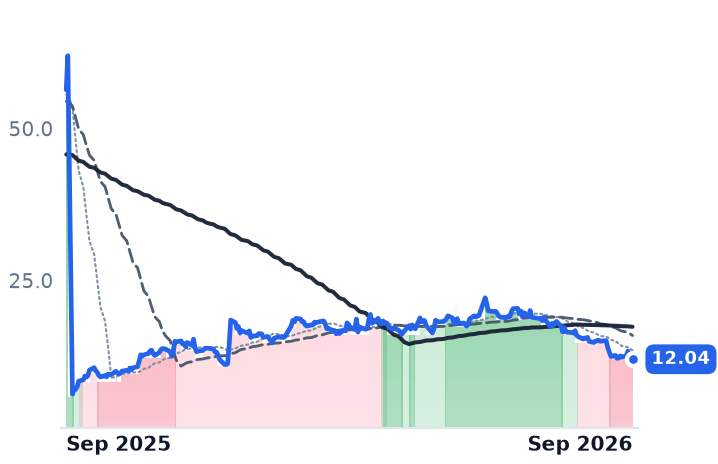
MLTX | MoonLake Immunotherapeutics | Immunology & Autoimmune | 🔴 Cont. Bear | −22.2% | −78.6% |
DNLI | Denali Therapeutics | CNS & Neurological | 🟢 Cont. Bull | −16.4% | +51.8% |
CGON | CG Oncology | Other | 🟢 Cont. Bull | −13.5% | +84.1% |
PCVX | Vaxcyte | Infectious Diseases & Vaccines | 🟢 Cont. Bull | −7.8% | +74.9% |
ALNY | Alnylam Pharmaceuticals | RNA-Based Therapeutics | 🔴 Cont. Bear | +6.7% | −43.1% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.4% | +17.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DYN | $3.0B | n/m | — | n/m | — | — | — | n/m | -16.7% |
ASND | $14.0B | 16.4x | 16.2x | 11.7x | 10.4x | 12.9x | 11.5x | 152.8x | 2.7% |
CYTK | $8.0B | n/m | — | 113.4x | 53.7x | 133.4x | 63.2x | n/m | -7.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MLTX | $1.6B | n/m | — | n/m | — | — | — | n/m | -14.5% |
DNLI | $3.7B | n/m | — | n/m | 104.4x | — | — | n/m | -11.5% |
CGON | $6.3B | n/m | — | — | 568.3x | — | — | n/m | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PCVX | $8.4B | n/m | — | n/m | 335.4x | — | — | n/m | -14.3% |
ALNY | $32.8B | 40.3x | 36.8x | 6.8x | 6.0x | 8.6x | 7.5x | 28.2x | 1.6% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DYN | Revenue | +43.8% | +5202.8% | +423.5% |
| EPS | +3.5% | −7.7% | −24.6% | |
ASND | Revenue | +90.9% | +46.5% | +27.1% |
| EPS | −516.5% | −35.2% | +58.5% | |
CYTK | Revenue | +94.8% | +182.8% | +110.5% |
| EPS | −6.8% | −26.1% | −52.9% | |
MLTX | Revenue | — | — | +499.2% |
| EPS | +6.4% | −5.3% | −19.5% | |
DNLI | Revenue | +1299.4% | +204.0% | +150.9% |
| EPS | −18.1% | +0.8% | −24.6% | |
CGON | Revenue | +292.5% | +669.5% | +432.7% |
| EPS | +26.5% | +2.4% | −97.0% | |
PCVX | Revenue | — | +248.6% | +103.3% |
| EPS | +51.9% | −19.8% | −5.5% | |
ALNY | Revenue | +45.6% | +26.9% | +19.6% |
| EPS | +171.3% | +51.0% | +24.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
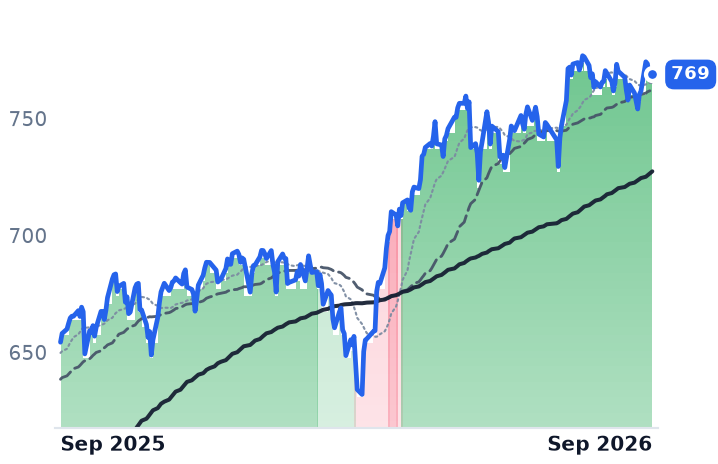
Novartis told investors on 8 September that del-desiran had failed to beat placebo on the primary endpoint of its Phase 3 HARBOR study in myotonic dystrophy type 1. Dyne Therapeutics, a Waltham, Massachusetts developer of muscle-targeted genetic medicines, published nothing of its own that day. Its shares fell 14.7%, on 9.2m shares against a recent daily average nearer 1m, and no comparable move hit neuromuscular peers.
By 25 September the stock had ground down to $16.03, a 34% decline in twelve sessions and roughly $1.5bn of market value. That matters beyond one bad fortnight because of what Dyne is: a $2.99bn company holding about $1.3bn of cash, which leaves some $1.7bn of value resting on two dated events, both in 2027, and one of them is a trial measured exactly the way Novartis's was.
The endpoint, not the molecule
The registrational expansion stage of Dyne's ACHIEVE trial of z-basivarsen is testing change from baseline in middle-finger myotonia by video hand opening time at six months versus placebo — the endpoint HARBOR missed. That is the transmission channel. It is also contestable: Jefferies argued after HARBOR that Dyne now "claims frontrunner status" in the disease, citing stronger tissue penetration, more consistent hand-opening effects and a larger splicing effect than Avidity's — the company Novartis bought for $12bn at a 46% premium, a deal that had itself been read as evidence that Dyne was next.
Dyne's own meters are short. Revenue has been zero in every quarter on record back to 2021. The second-quarter operating loss widened 57% to $181.7m, and diluted shares rose 45% over the year to 165.5m. Cash was $898.5m at 30 June plus about $405m net from a July offering, funding operations into the second quarter of 2028. The dates are a 21 January 2027 decision deadline for z-rostudirsen in exon-51 Duchenne muscular dystrophy, and ACHIEVE topline in the first quarter of 2027. Price-to-book of 3.78x is the only anchor that means anything; forward price-to-sales of 3,006x sits on $1m of consensus revenue. Analysts' 2028 revenue estimates run from $154m to $774m.
The list fell; the premise did not
Equal-weighted, the eight-stock Barron's takeout list Dyne belongs to is down 15.4% over thirty days while the S&P 500 exchange-traded fund rose 0.4%. But Alnylam rose 7.1% in the same window, and the other sharp declines each carry their own cause. Ascendis Pharma, the Danish maker of the TransCon slow-release hormone therapies, fell 9.5% on 15 September when Novo Nordisk handed back its obesity licence; Cytokinetics, which sells the oral heart-muscle inhibitor MYQORZO, fell 8.5% on 28 August when positive Phase 3 data in non-obstructive cardiomyopathy came with a modest effect size. Acquisition appetite, meanwhile, is widening: 80 deals worth $96bn in the first half of 2026 against 50 for all of 2025.
The three are paid for different things, which is why one drawdown means three things. Ascendis grew second-quarter revenue 118% and swung its operating margin to +18.4% from −33.5%, and now trades at 10.4x forward sales against 11.7x trailing — against roughly 11x in mid-September — while owing BioMarin a 20% royalty on U.S. Yuviwel sales. Its constraint is keeping patients on drug: "The majority of the drop-off is during that titration period," Jay Wu, president of Ascendis U.S., told investors on the 13 August call. Cytokinetics' $25.3m of second-quarter product revenue against a $175.9m operating loss supports 53.7x forward sales at gross margins within a point of Ascendis's, with consensus showing no profit until 2029; its de-rating from 57x is the one the arithmetic invites.
Dyne's is not a de-rating at all. Nothing about its cash, its timelines or its data changed in September; what changed is the market's estimate of how hard the hand-opening endpoint is to clear, learned from someone else's failure. That is real information, and it is not information about Dyne's molecule.
Which leaves a company whose next two quarterly reports cannot settle anything. The first day that can is in January 2027 — and it concerns a different muscle disease entirely.