

Sterling's Site-Development Revenue Nearly Tripled as Argan's Gas Backlog Fell $411m
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
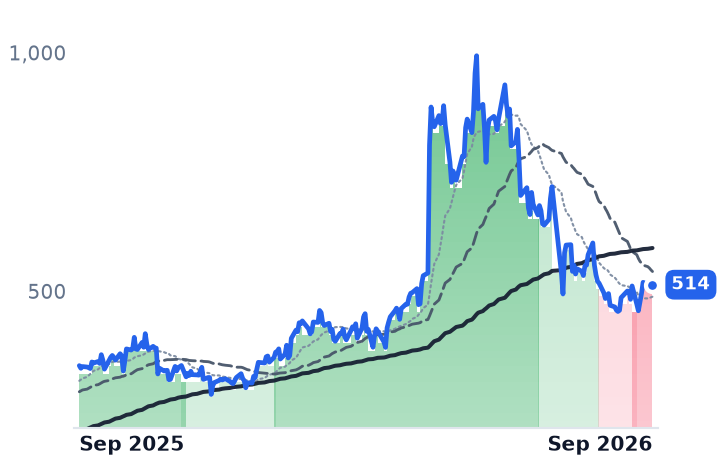
The earliest-cycle work in the data-center chain — moving dirt and pouring pads — was supposed to crack first if the AI build-out slowed. It didn't. Sterling Infrastructure grew June-quarter revenue 90.1% at a 24.2% gross margin, lifted signed backlog 116% to $4.33bn and raised full-year guidance to $19.70–20.30 in adjusted earnings a share. Its shares are still 48% below their June peak, and its trailing earnings multiple has halved to 36.5x.
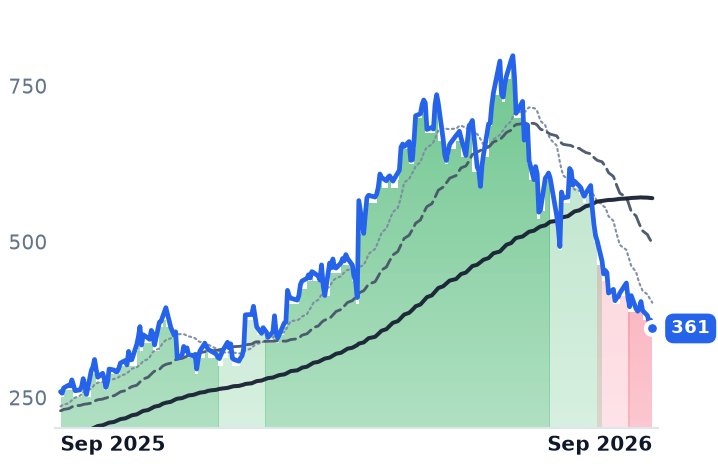
The name where the meters actually rolled over is Argan, the fixed-price builder of gas-fired plants: backlog down $411m to $2.5bn since the fiscal year began and gross margin down three straight quarters, from 25.0% to 19.3%. Its order book is 80% natural gas, into a Texas interconnection queue frozen for audit. One of these two de-ratings the business explains. The other it does not.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
STRL | Sterling Infrastructure | Civil Infrastructure | ⚠️ Emerging Bear | +6.0% | +49.3% |
AGX | Argan | Energy Solutions | ⚠️ Emerging Bear | −19.5% | +39.1% |
PWR | Quanta Services | Power Grid & Distribution | ⚠️ Emerging Bear | +7.0% | +59.8% |
| Compared against · context, not the story | |||||
MTZ | MasTec | Energy Solutions | ⚠️ Emerging Bear | −14.1% | +2.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STRL | $16.4B | 38.0x | 26.9x | 4.8x | 4.0x | 20.2x | 17.0x | 22.6x | 2.9% |
AGX | $5.5B | 30.5x | 29.7x | 4.6x | 3.9x | 22.2x | 18.8x | 23.6x | 9.9% |
PWR | $101.7B | 76.5x | 40.4x | 3.1x | 2.6x | 21.5x | 17.8x | 35.5x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MTZ | $17.3B | 34.0x | 23.2x | 1.1x | 1.0x | 9.4x | 8.3x | 15.4x | 1.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
STRL | Revenue | +71.5% | +21.2% | +17.3% |
| EPS | +91.2% | +28.0% | +20.6% | |
AGX | Revenue | +12.1% | +48.9% | +20.4% |
| EPS | +65.8% | +57.7% | +19.4% | |
PWR | Revenue | +41.1% | +16.2% | +13.8% |
| EPS | +57.6% | +17.8% | +17.9% | |
MTZ | Revenue | +29.2% | +18.9% | +15.4% |
| EPS | +44.9% | +34.5% | +31.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The place a slowdown in data-center construction was supposed to appear first is the place it hasn't appeared at all. Sterling Infrastructure, which does mass grading, foundations and underground utilities for data-center, semiconductor and warehouse campuses before anyone pulls a single wire, grew that business 192% year over year in the June quarter, according to its quarterly presentation. Its transportation and building-solutions segments shrank. All of the growth came from the segment closest to the AI trade.
That matters because five contractors in this corner — the companies that pour pads, energize substations and erect power plants — fell an average of 37% in the three months to 23 September, and the fall began on 28 July, when chip stocks shed more than $1 trillion in a single session and investors began reassessing near-term returns on AI spending. None of these companies had reported yet. What the subsequent earnings showed is that the group is not one story: in one name the order book and the margin are both going the wrong way, and in the other neither is.
Sterling: guidance up, multiple halved
Sterling's June-quarter revenue was $1.168bn, up 90.1%, with gross margin of 24.2% and diluted earnings of $5.00 a share against $2.31. Operating income grew 113.8% on 90.1% more revenue — leverage, not mix. Signed backlog reached $4.33bn, up 116% year over year, with combined backlog of $5.62bn and mission-critical projects at 92% of the site-development book, the company reported. Full-year guidance was raised to $4.0–4.15bn of revenue and $19.70–20.30 of adjusted earnings a share.
The shares fell on it anyway, and there is one honest reason inside the print: site-development adjusted operating margin of 24.1% against 28.3% a year earlier, because the acquired CEC electrical business runs at 11.4% against upper-20s margins in earthwork. Chief executive Joe Cutillo also pre-announced a wobble, telling investors on the August 4 call that "this, coupled with our forecast for strong revenue burn in the third quarter[,] could result in a sequential backlog decline in the third quarter," which he attributed to customer bidding-cycle timing.
Against that, the price. Sterling closed at $993.74 on 4 June and at $512.00 on 23 September, down 48.5%, having troughed at $457.60 on 2 September. On unchanged trailing earnings of $13.87 a share, the June peak was roughly 71.6x; today it is 36.5x trailing and 25.9x forward. The multiple halved while the guidance went up.
Argan: the order book that actually shrank
Argan, a 1,409-employee builder of fixed-price gas plants through its Gemma Power Systems unit, reported record July-quarter results — revenue up 61.5% to $384m, net income of $53.3m — and its shares set a new low on 22 September, three weeks later. The reason is on the other two lines. Backlog fell to $2.5bn from $2.9bn at the fiscal year's start, a $411m decline the company attributed to completions and award timing, and gross margin has stepped down three quarters running. "Consolidated gross margin has stepped down over the past 3 quarters from 25% in the fourth quarter of fiscal 2026 to 21% in Q1 of fiscal 2027 and now 19.3% in the second quarter," chief financial officer Joshua Baugher said on the September 2 call, adding that second- and third-year project ramps offer "the opportunity to enhance margin." Its fabrication arm took the acute hit: 111% revenue growth at a 7.3% margin after two projects came in with higher estimates to complete.
In fixed-price engineering and construction the margin is set at signature, so a step-down is a statement about work already sold. And Argan's book is 80% natural gas at the moment Texas froze the queue: on 3 August Governor Greg Abbott ordered an audit of every data-center project seeking ERCOT interconnection, with data centers roughly 90% of 474 GW of requests, and BloombergNEF estimates the review could delay 49.8 GW of load and cost projects up to $15bn. Management said it has seen no change in developer behavior. Matthew Smith of Chronometer Partners argued in a 22 June letter that gas-plant contractors are "acutely short natural gas" and that new construction could stop around 2028 as approved liquefied-natural-gas exports outrun supply growth.
Argan trades on 29.6x trailing earnings and 28.7x forward — the market pricing no growth for a year consensus still has at $13.04 a share. The counterweight is $1.0bn of cash and investments with no debt against a $5.25bn market value, roughly 23x excluding cash, and a trailing free-cash-flow yield above 10%.
The name that didn't break
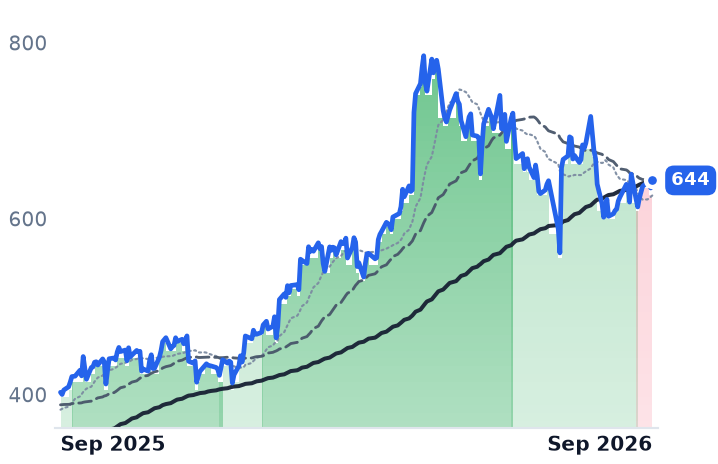
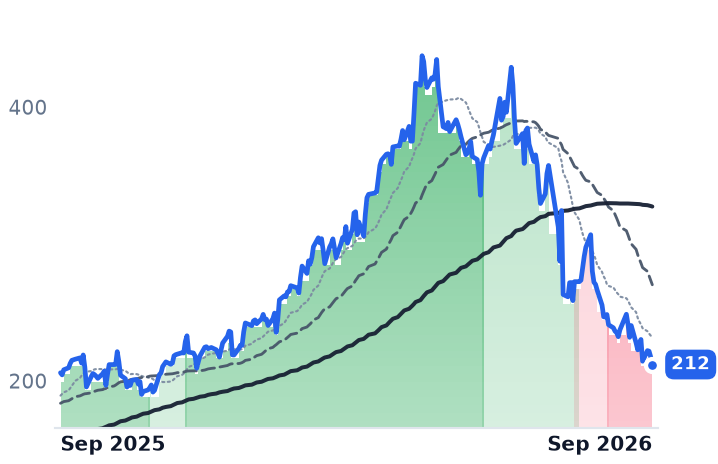
Quanta Services, the 69,500-employee transmission and substation contractor, is the control and it sat out most of this. Revenue grew 41.1% to $9.557bn with gross margin up nearly three percentage points to 16.2%, backlog at a record $53.4bn and free cash flow of $0.9bn in the quarter; about 70% of its $33.6bn of contracted performance obligations converts within twelve months. It fell 9.6% over the three months, against 42.6% for Sterling and 49.2% for Argan. MasTec, which posted record revenue up 23% and an 18-month backlog up 30% to $21.4bn, fell 44.3% — so the selling was not company-specific either.
What connects the de-ratings is duration, not demand: the 30-year Treasury yield is around 5.3%, the highest in roughly 19 years, and a higher discount rate shrinks the present value of an order book that pays in 2028 without shrinking the book. Sterling's fall is that repricing, plus a real mix dilution from an electrical acquisition earning 11.4%. Argan's is something firmer: a shrinking order book, a margin set at signature that has fallen four percentage points, and the only genuine demand-side event in the window sitting on top of 80% of its backlog. The heading can no longer be traded as one thing.
The cheapest test arrives on a schedule nobody controls. Texas said its audit would take several months; Argan expects to add a handful of new projects over the next seven to fifteen months against capacity for a dozen jobs at once.