

Fair Isaac's $10 Mortgage Score Now Faces a $1 Rival Cleared for Every Fannie Mae Lender
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
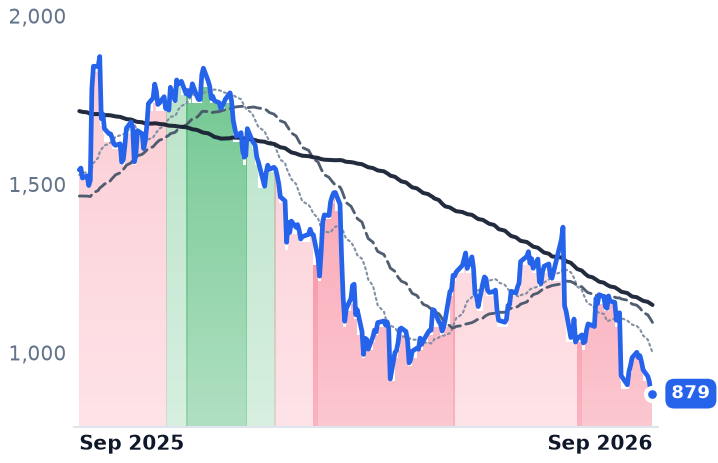
Fair Isaac's mortgage business is growing faster than it ever has while its shares have lost more than 40% in a year. Both are true because the growth came from a price the company set by itself — the wholesale royalty on a mortgage score more than doubled for 2026 — and on 3 September the Federal Housing Finance Agency directed Fannie Mae and Freddie Mac to approve every eligible lender to use VantageScore 4.0 instead.
Scores revenue rose 41% in the June quarter and mortgage-origination revenue rose 97%, against industry forecasts of roughly 8% growth in loan volume. Nothing in the reported meters has broken. What has broken is the assumption that nobody can undercut the toll. The seat-billed platforms — Q2 Holdings and Alkami — face a different question entirely, and Alkami's 19.3% fall this week answered none of it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
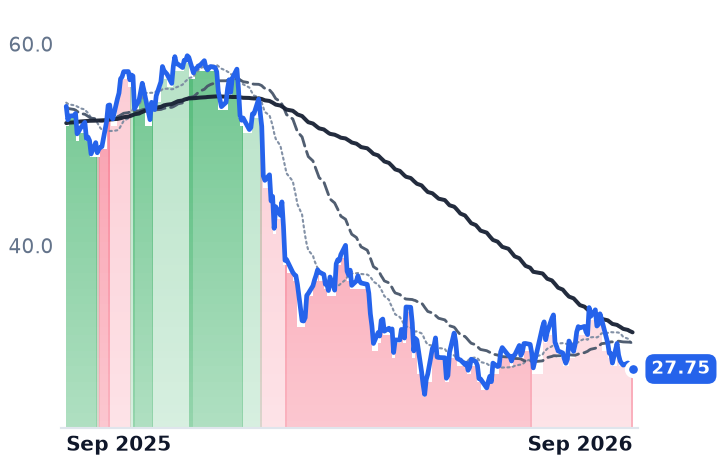
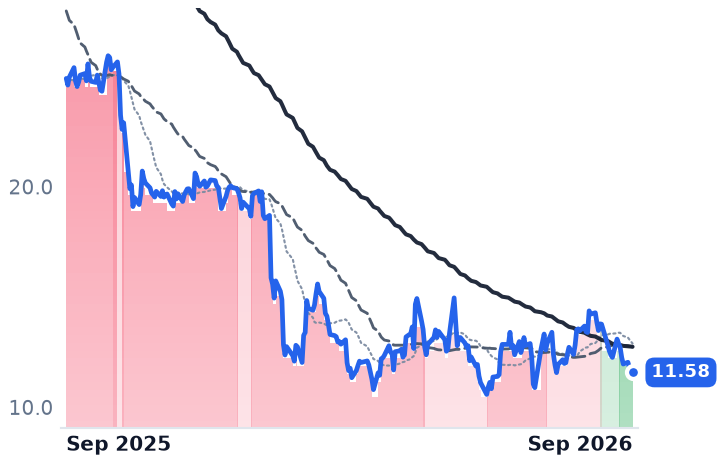
FICO | Fair Isaac | Data, Analytics & Intelligence | 🔴 Cont. Bear | −22.7% | −43.1% |
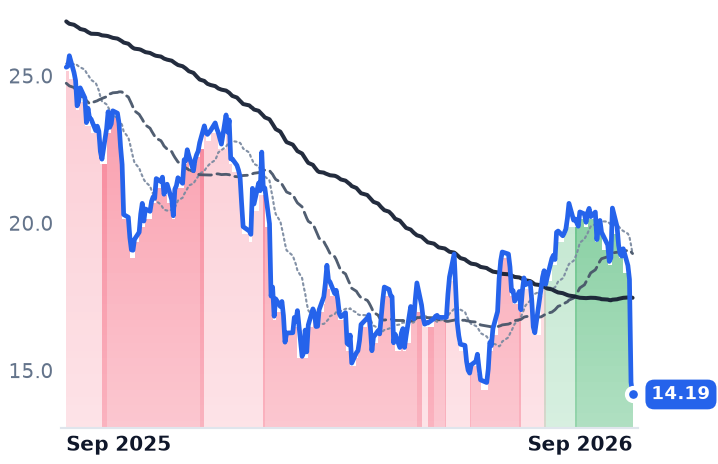
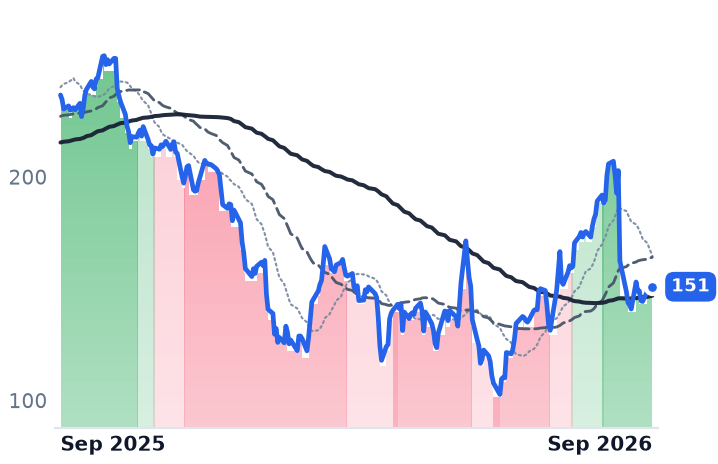
ALKT | Alkami Technology | Commerce & Digital Payments | 🌱 Emerging Bull | −29.2% | −43.9% |
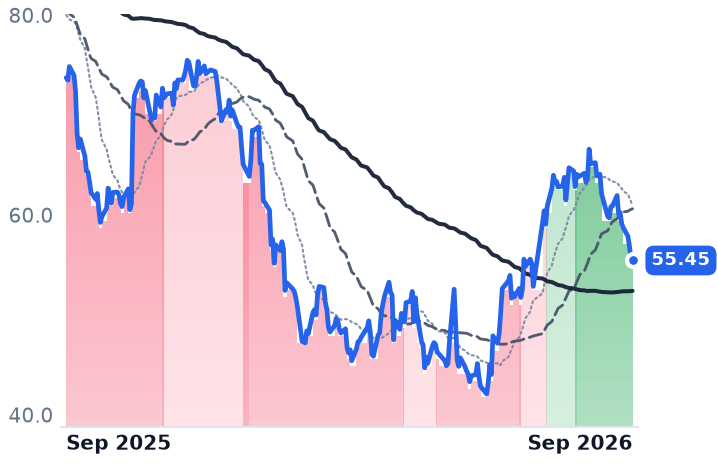
QTWO | Q2 | Commerce & Digital Payments | 🌱 Emerging Bull | −12.4% | −24.8% |
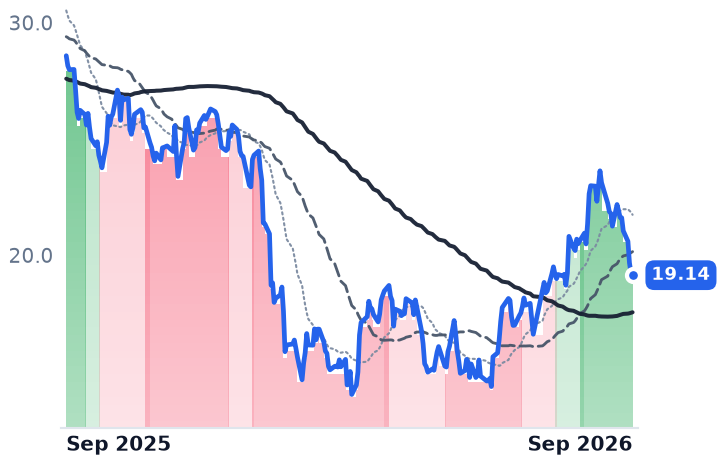
NCNO | nCino | Commerce & Digital Payments | 🌱 Emerging Bull | −6.6% | −33.0% |
BL | BlackLine | Other | 🔴 Cont. Bear | −11.7% | −48.4% |
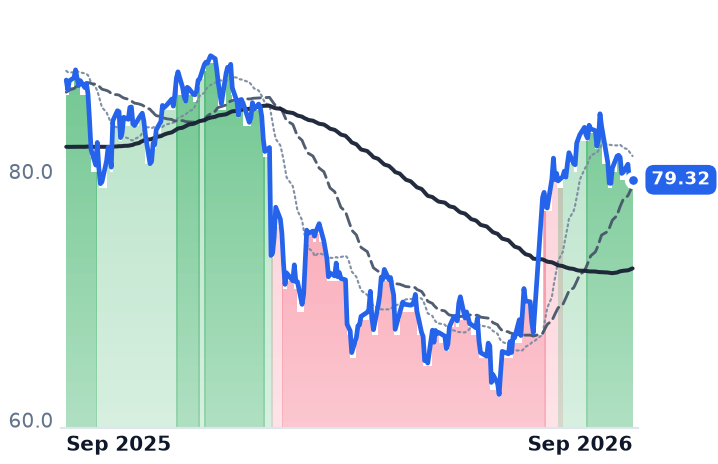
GWRE | Guidewire Software | Industry-Specific Platforms | 🌱 Emerging Bull | −19.9% | −36.2% |
SSNC | SS&C Technologies | Enterprise Resource Planning | 🌱 Emerging Bull | −4.4% | −9.2% |
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | −5.5% | −36.9% |
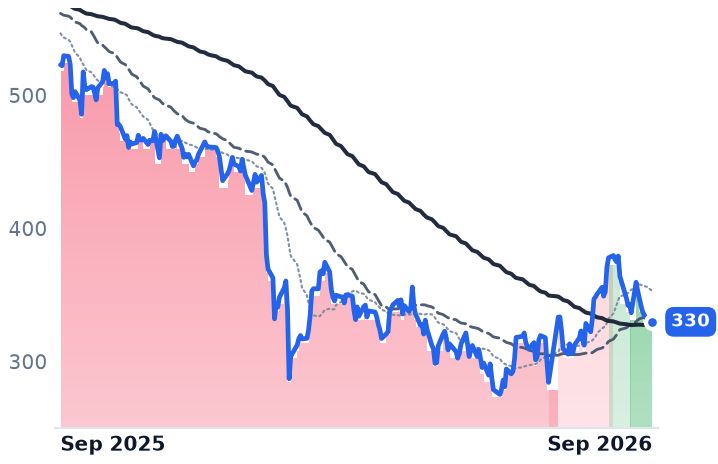
VERX | Vertex | Commerce & Digital Payments | 🔴 Cont. Bear | −13.7% | −53.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FICO | $15.2B | 19.3x | 15.6x | 6.0x | 5.8x | 7.0x | 6.7x | 16.1x | 7.0% |
ALKT | $1.4B | n/m | 16.2x | 2.8x | 2.7x | 4.9x | 4.7x | 273.4x | 3.8% |
QTWO | $4.6B | 41.8x | 26.4x | 5.2x | 5.1x | 9.0x | 8.8x | 27.0x | 5.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NCNO | $2.4B | 73.1x | 17.2x | 3.9x | 3.7x | 6.3x | 6.0x | 28.7x | 5.5% |
BL | $1.5B | 38.0x | 10.4x | 2.0x | 2.0x | 2.7x | 2.6x | 18.5x | 11.4% |
GWRE | $13.3B | 97.8x | 38.8x | 9.0x | 7.8x | 14.1x | 12.1x | 63.9x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SSNC | $18.2B | 21.8x | 10.9x | 2.7x | 2.7x | 5.7x | 5.6x | 11.3x | 9.6% |
TYL | $16.7B | 52.4x | 32.1x | 6.7x | 6.6x | 14.3x | 13.9x | 29.9x | 4.4% |
VERX | $2.8B | n/m | 20.4x | 3.4x | 3.3x | 5.5x | 5.3x | 53.5x | 1.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FICO | Revenue | +27.2% | +3.7% | +4.6% |
| EPS | +44.6% | +6.1% | +8.6% | |
ALKT | Revenue | +19.9% | +14.4% | +14.4% |
| EPS | +59.0% | +30.1% | +26.1% | |
QTWO | Revenue | +12.5% | +10.2% | +10.0% |
| EPS | +17.9% | +23.8% | +17.2% | |
NCNO | Revenue | +9.8% | +8.9% | +8.6% |
| EPS | +25.2% | +45.3% | +19.9% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
GWRE | Revenue | +23.8% | +17.2% | +15.6% |
| EPS | +41.5% | +20.0% | +27.5% | |
SSNC | Revenue | +8.4% | +5.1% | +4.9% |
| EPS | +17.7% | +8.6% | +8.4% | |
TYL | Revenue | +8.7% | +9.9% | +9.8% |
| EPS | +14.8% | +18.9% | +14.1% | |
VERX | Revenue | +10.7% | +10.4% | +11.3% |
| EPS | +30.8% | +22.3% | +23.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fair Isaac raised the wholesale royalty it charges for a mortgage credit score from $4.95 to $10 for 2026, a unilateral increase passed through by the credit bureaus and the resellers who assemble three-bureau reports. The money arrived exactly as designed. In the quarter ended 30 June, mortgage-origination revenue grew 97% and accounted for 62% of the Scores segment, whose revenue reached $458.9m against $324.3m a year earlier.
The trouble is what a price set by one company invites. On 3 September, Federal Housing Finance Agency director Bill Pulte directed Fannie Mae and Freddie Mac to approve every eligible lender to use VantageScore 4.0, converting a pilot that began on 1 May into a market-wide choice. Fair Isaac — which sells credit scores licensed through the bureaus and decisioning software to lenders, and carries a $19.0bn market value — closed the next session down 16.7%, and has kept sliding since.
Ten dollars against one
The rival is not priced to compete at the margin. TransUnion cut VantageScore 4.0 to $0.99 for mortgage lenders and bundles it free with a FICO score purchase through 2026; Experian made it free indefinitely; Equifax has committed to $1 through the end of 2027. VantageScore says its 4.0 model had already taken more than 9% of mortgage securitizations backed by the two government-sponsored enterprises by the end of August — before the directive.
Chief executive Will Lansing did not dispute the setup on the July 29 call. "It is a reality that Vantage is selling scores and is sending them along with FICO Scores... gaming is a reality and we're going to have gaming," he said. "The rules of the road, the environment that we're operating in is a gaming environment. The FHFA has put it in place. The GSEs have accepted it. And so that's the world we have." His defense was the product: "10T is absolutely the best score in the world for measuring credit default risk."
Volume will not rescue the toll. The Mortgage Bankers Association forecast about $2.2trn of single-family originations in 2026, roughly 8% above 2025, and has since trimmed that to about $2.12trn. Essentially all of the 97% is price.
Meanwhile the reported numbers are the best in years: revenue up 25.7%, operating margin of 53.8% against 48.9%, and guidance raised to $2.53bn for the fiscal year. Diluted shares fell 7.6% year on year, so earnings per share grew 41% on net income growth of 30.5% — about ten points of the EPS gain bought rather than earned, helped by a $1.5bn term loan drawn in June to fund an accelerated repurchase. The shares are down 42.7% over twelve months and trade at 25.3x trailing and 20.5x forward earnings, against roughly 44x forward at the twelve-month high close. Consensus already has fiscal 2027 revenue growth halving to 14%.
Paid by the seat instead
The contrast is not with every software vendor that rallied this summer — the rebound off the June low swept in public-sector and insurance-systems companies with no bank exposure at all. It is with the two firms billed per registered digital user. Q2 Holdings, which sells digital-banking software to regional and community banks and credit unions, reported subscription annual recurring revenue of $826m, up 15%, and $2.76bn of remaining performance obligations. Revenue growth decelerated to 12.6%, but gross margin expanded to 59.2% from 53.6% and operating income nearly tripled. It trades at 19.2x forward earnings against 37.6x trailing — the market paying for the margin ramp.
Alkami, its smaller Plano, Texas rival, showed annual recurring revenue of $511.7m, up 21%, on 23.6m registered users, up 13%. Then on 23 September its board concluded a review of strategic opportunities and chose to stay independent, reaffirming revenue guidance of $528m–$531m and adjusted EBITDA of $96m–$98m word for word. The shares fell 19.3% to $14.60 — below the $18.17 they closed at on 31 July, before advisers began approaching buyers. More than a deal premium came out.
nCino, which sells loan-origination and onboarding software to the same institutions, shows what the seat model avoids: its US mortgage subscription revenue fell 1% to $20.6m last quarter while everything else accelerated to 12%, and management blamed higher-for-longer rates driving churn among independent mortgage banks.
What the de-rating is actually pricing
None of Fair Isaac's meters has turned. The de-rating is a forecast, and a specific one: that a royalty set unilaterally is worth less when a regulator hands every lender a substitute at a tenth of the price. Seat-based vendors face pressure of a different kind — Q2's growth is slowing, Alkami's has halved from 28.9% to 15.9%, and per-institution pricing limits how far account-level expansion carries either — but no memo from Washington can replace a bank's core software in a quarter.
Equifax's dollar price runs through the end of 2027. Fair Isaac's fiscal-year guidance, due with fourth-quarter results, is the first place management has to say what it thinks that costs.