

Ralph Lauren Raised Fiscal-2027 Guidance After Average Selling Prices Rose 15%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
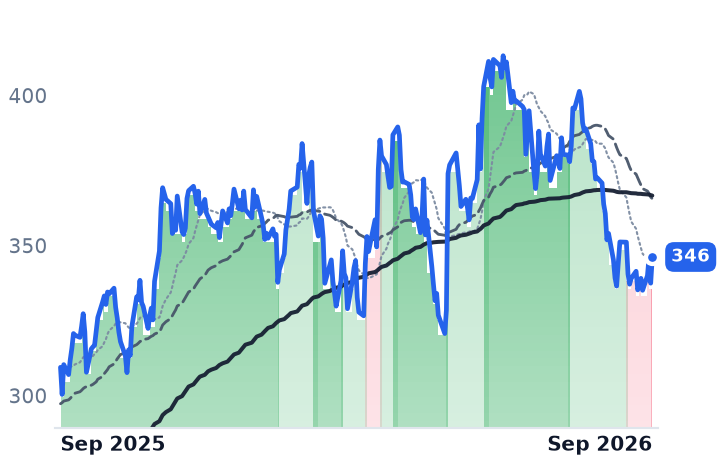
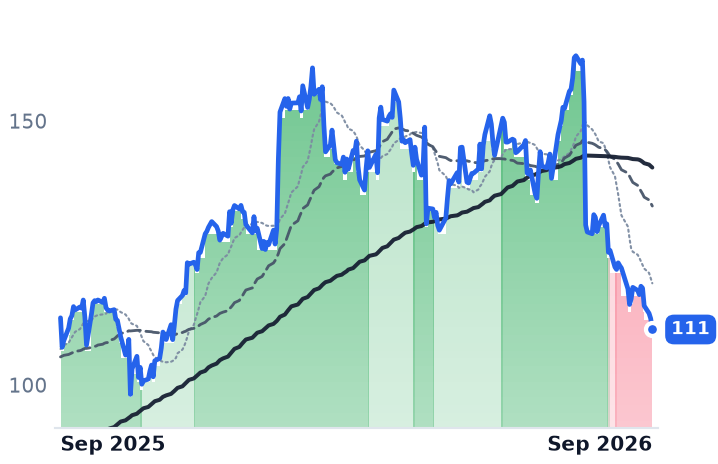
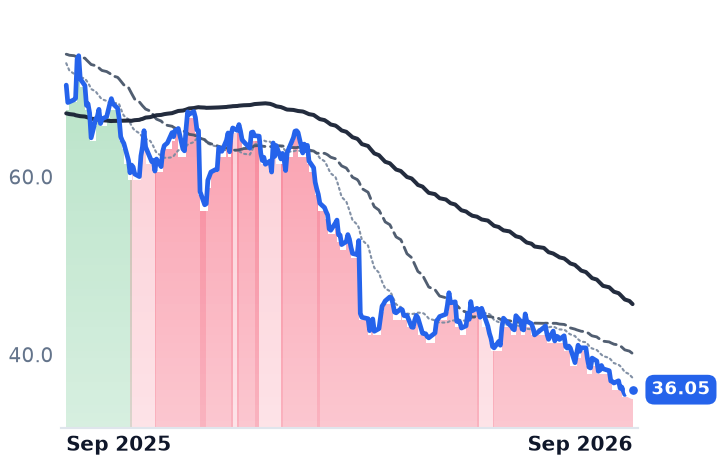
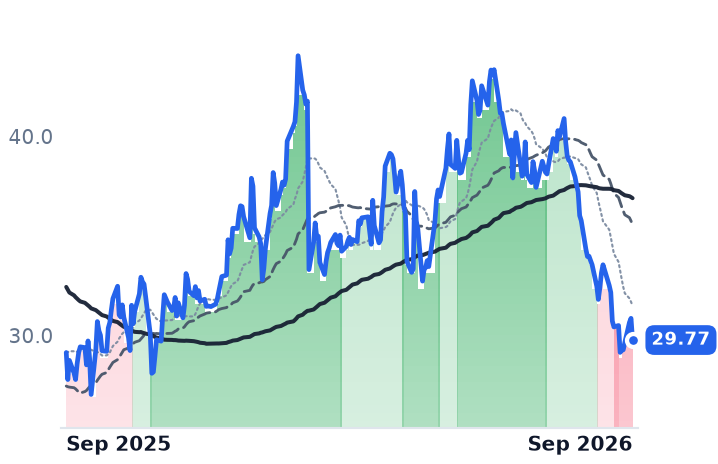
A premium apparel maker whose business is accelerating has spent six weeks being sold. Ralph Lauren grew June-quarter revenue 14% and raised its full-year outlook on 6 August, gross margin reaching 73.7% as average selling prices rose; the shares have walked down since 10 August with no company news and no single session losing more than about 3%, leaving the forward earnings multiple at 18.3x — roughly where it sat in 2024 and 2025, when revenue grew 3% to 7%.
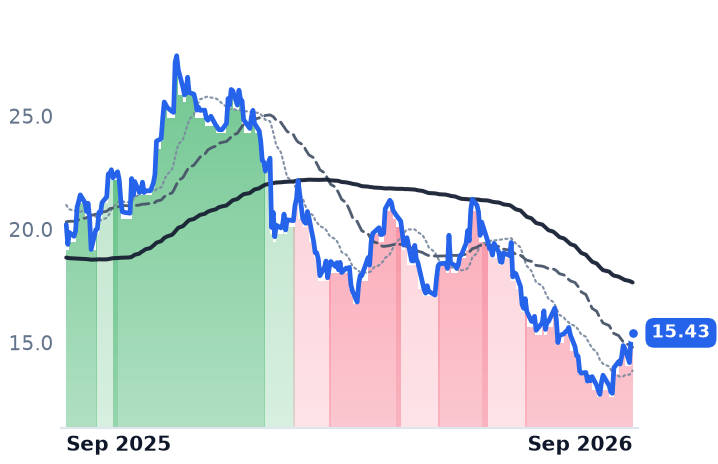
The two nearest American comparables earned their de-ratings honestly. PVH's wholesale revenue fell in every region and its spring-2027 European order book is committed lower; Oxford Industries cut full-year earnings guidance below last year's result and fell 16% in a single session. Ralph Lauren is the one whose numbers do not fit the selling.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
RL | Ralph Lauren | Premium Lifestyle | 🟢 Cont. Bull | −4.8% | +11.9% |
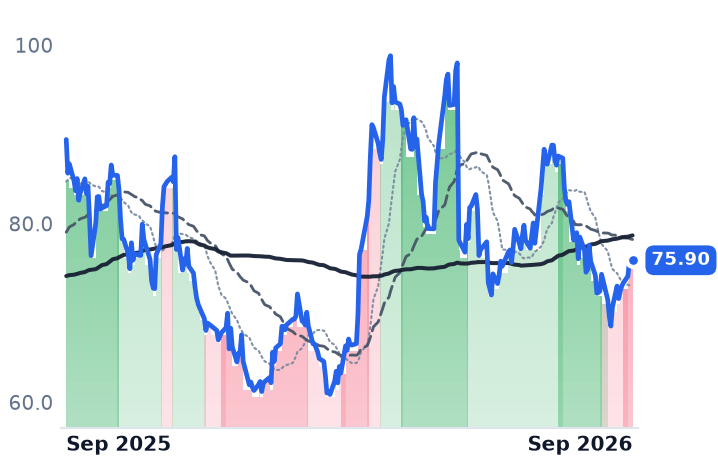
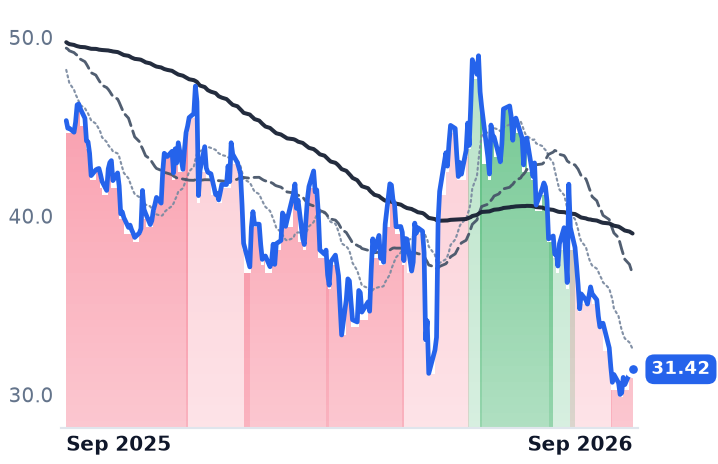
PVH | PVH | Premium Lifestyle | 🌱 Emerging Bull | +1.8% | −15.1% |
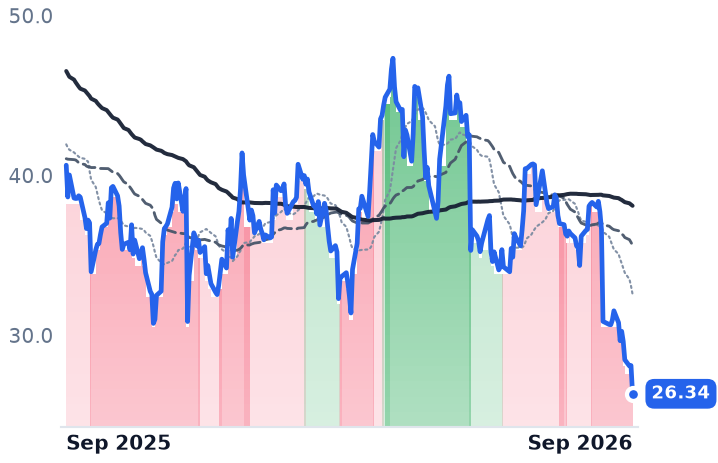
OXM | Oxford Industries | Premium Lifestyle | 🔴 Cont. Bear | −28.1% | −35.2% |
| Compared against · context, not the story | |||||
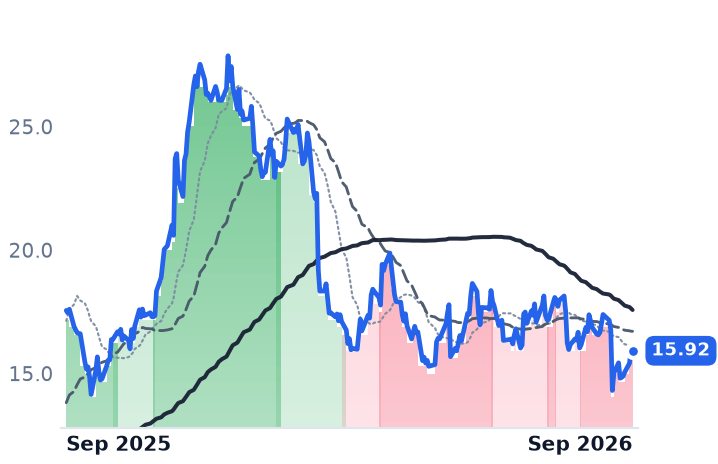
ZGN | Ermenegildo Zegna | Premium Lifestyle | 🟢 Cont. Bull | −8.7% | +30.9% |
TPR | Tapestry | Handbags & Accessories | 🟢 Cont. Bull | −15.0% | −2.0% |
CPRI | Capri | Handbags & Accessories | 🔴 Cont. Bear | +16.0% | −23.7% |
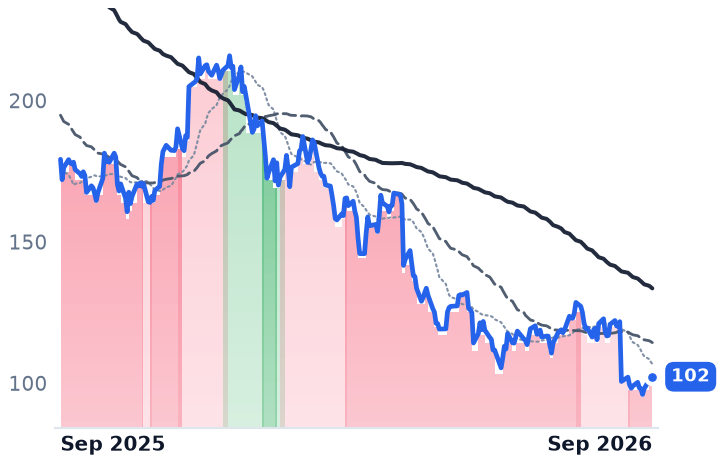
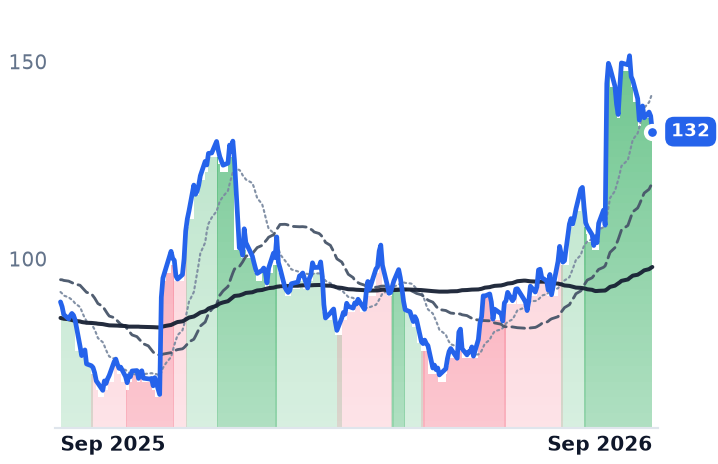
LULU | Lululemon Athletica | Athletic & Activewear | 🔴 Cont. Bear | −13.4% | −42.9% |
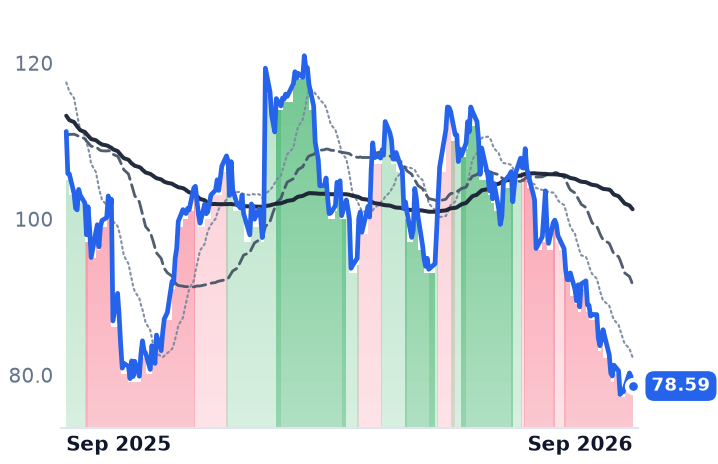
DECK | Deckers Outdoor | Premium Lifestyle Footwear | 🔴 Cont. Bear | −11.7% | −29.3% |
NKE | NIKE | Athletic & Performance | 🔴 Cont. Bear | −8.8% | −48.7% |
BIRK | Birkenstock | Premium Lifestyle Footwear | 🔴 Cont. Bear | −10.4% | −30.7% |
KTB | Kontoor Brands | Denim & Casual | 🟢 Cont. Bull | −18.2% | −18.1% |
LEVI | Levi Strauss | Denim & Casual | 🟢 Cont. Bull | −7.1% | −13.8% |
CRI | Carter's | Childrenswear | 🟢 Cont. Bull | −12.4% | +2.1% |
AEO | American Eagle Outfitters | Specialty Apparel | 🔴 Cont. Bear | −4.6% | −9.3% |
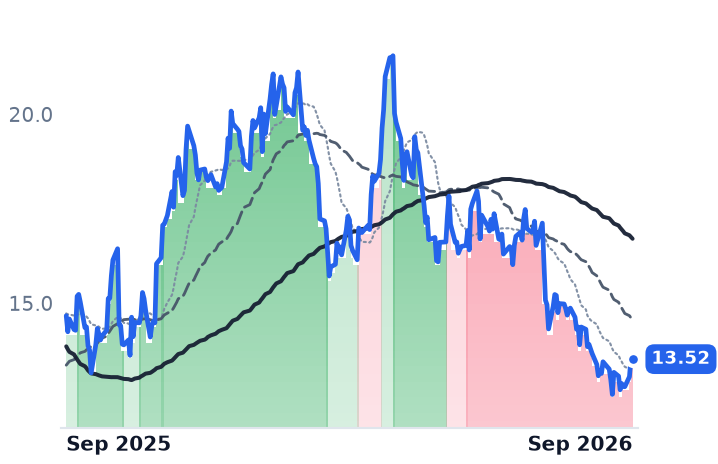
ANF | Abercrombie & Fitch | Specialty Apparel | 🌱 Emerging Bull | +21.9% | +48.5% |
VFC | V.F | Outdoor & Adventure | 🔴 Cont. Bear | −2.4% | −7.8% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +0.3% | +16.8% |
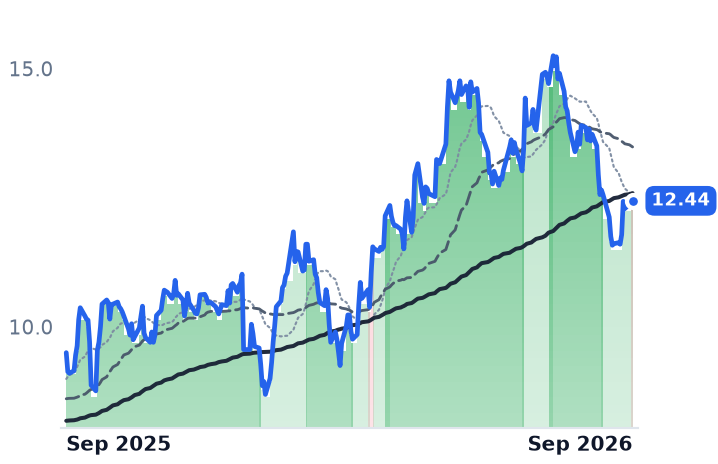
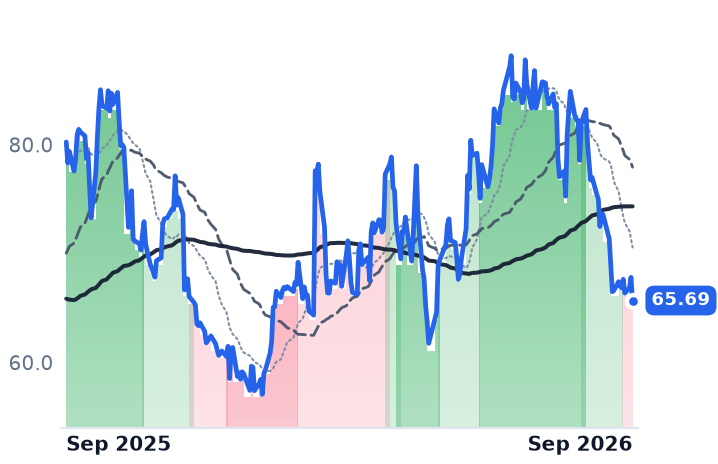
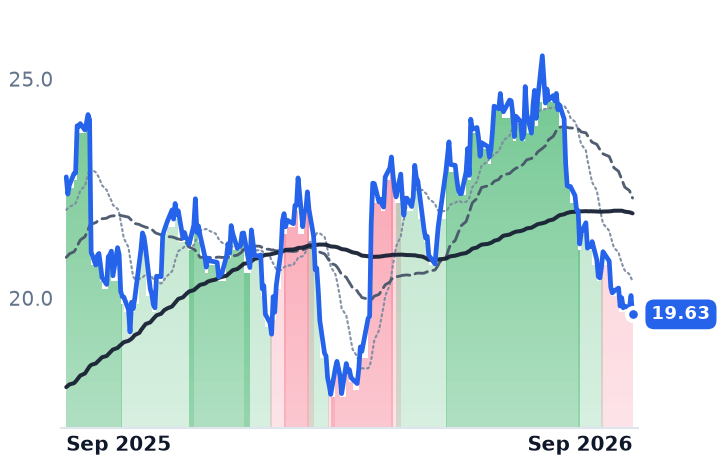
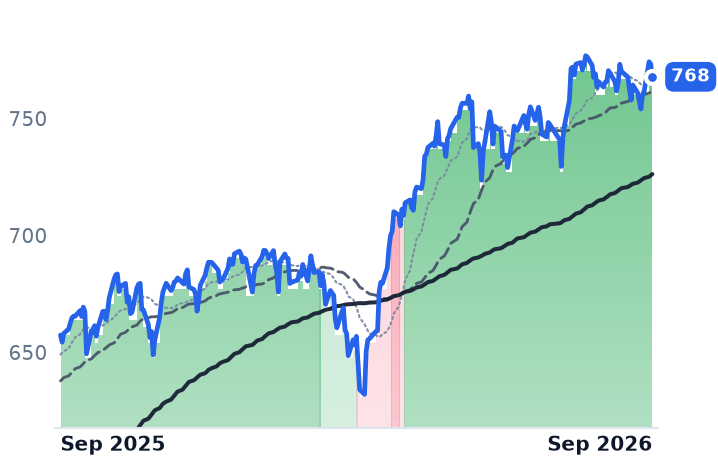
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RL | $21.1B | 21.5x | 18.3x | 2.5x | 2.4x | 3.6x | 3.5x | 15.1x | 4.9% |
PVH | $3.5B | n/m | 6.3x | 0.4x | 0.4x | 0.7x | 0.7x | 10.6x | 20.4% |
OXM | $391.6M | n/m | 14.8x | 0.3x | 0.3x | 0.4x | 0.4x | 15.9x | 13.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ZGN | $3.3B | 37.5x | 30.3x | 1.5x | 1.6x | 2.6x | 2.9x | 9.2x | 10.4% |
TPR | $23.0B | 15.2x | 14.2x | 2.9x | 2.7x | 3.7x | 3.4x | 12.2x | 7.9% |
CPRI | $1.5B | 10.1x | 6.0x | 0.4x | 0.4x | 0.7x | 0.7x | 11.5x | 5.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LULU | $14.0B | 9.0x | 9.7x | 1.3x | 1.2x | 2.2x | 2.2x | 5.1x | 6.6% |
DECK | $11.2B | 11.7x | 11.0x | 2.0x | 1.9x | 3.5x | 3.3x | 7.3x | 10.7% |
NKE | $61.9B | 27.5x | 28.1x | 1.3x | 1.3x | 3.3x | 3.3x | 19.9x | 1.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BIRK | $6.0B | 15.2x | 16.4x | 2.3x | 2.5x | 4.1x | 4.6x | 9.3x | 5.5% |
KTB | $3.4B | 12.3x | 11.5x | 1.1x | 1.2x | 2.3x | 2.5x | 10.1x | 11.7% |
LEVI | $8.3B | 13.2x | 14.0x | 1.3x | 1.2x | 2.1x | 2.0x | 10.1x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CRI | $1.2B | 13.1x | 10.4x | 0.4x | 0.4x | 0.9x | 0.9x | 7.0x | 10.3% |
AEO | $2.5B | 13.5x | 8.7x | 0.5x | 0.4x | 1.4x | 1.3x | 7.4x | 1.0% |
ANF | $3.2B | 6.4x | 6.6x | 0.6x | 0.6x | 1.0x | 1.0x | 4.1x | 11.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VFC | $5.2B | 18.8x | 12.3x | 0.5x | 0.5x | 1.0x | 1.0x | 11.7x | 11.2% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
RL | Revenue | +13.6% | +8.8% | +5.3% |
| EPS | +35.1% | +15.9% | +11.0% | |
PVH | Revenue | +3.0% | +0.2% | +1.7% |
| EPS | −6.6% | +10.8% | +3.4% | |
OXM | Revenue | −2.3% | −1.3% | +2.3% |
| EPS | −66.2% | −20.9% | +33.3% | |
ZGN | Revenue | +7.1% | +8.2% | +6.9% |
| EPS | +7.9% | +34.9% | +19.0% | |
TPR | Revenue | +14.7% | +7.1% | +5.4% |
| EPS | +37.4% | +14.1% | +11.7% | |
CPRI | Revenue | −20.8% | −2.2% | +2.5% |
| EPS | +38.9% | +51.2% | +18.4% | |
LULU | Revenue | +4.7% | +3.9% | +4.5% |
| EPS | −9.1% | −5.7% | +7.7% | |
DECK | Revenue | +9.4% | +8.2% | +7.4% |
| EPS | +16.1% | +9.3% | +10.9% | |
NKE | Revenue | +0.7% | +0.6% | +4.4% |
| EPS | −30.5% | +22.1% | +28.6% | |
BIRK | Revenue | +13.7% | +14.0% | +13.1% |
| EPS | +15.9% | +23.4% | +18.5% | |
KTB | Revenue | +19.4% | −9.7% | +4.2% |
| EPS | +13.2% | −2.7% | +21.4% | |
LEVI | Revenue | +7.5% | +4.9% | +6.0% |
| EPS | +13.0% | +12.0% | +15.6% | |
CRI | Revenue | +2.6% | +4.4% | +1.3% |
| EPS | −37.8% | −2.7% | +12.1% | |
AEO | Revenue | +2.8% | +5.6% | +3.4% |
| EPS | −19.0% | +28.1% | +12.0% | |
ANF | Revenue | +6.8% | +3.9% | +3.8% |
| EPS | −7.7% | +8.9% | +9.6% | |
VFC | Revenue | −2.4% | +1.9% | +3.1% |
| EPS | +12.1% | +29.2% | +24.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Ralph Lauren raised its outlook for the year to March 2027 on 6 August, after a quarter in which it charged roughly 15% more for the average item and still grew comparable store sales at its own stores and websites by low double digits. Revenue rose 14% to $2.0bn and adjusted earnings per share 22% to $4.59, and the company lifted its full-year constant-currency growth outlook to about 5% to 6%.
That combination is the whole premium-apparel argument in one quarter. A brand like this earns three different kinds of money — units shipped to department stores at a margin fixed months before the selling season, sales through its own 504 stores and digital shops where realized price sets the gross margin, and royalties on fragrance, eyewear and home goods on inventory it never touches. All three worked at once, and the shares have fallen 15.9% since, from $401.37 on 10 August to $337.47 on 23 September, without a single session down more than about 3% and without a disclosed company event.
The meters that worked
Gross margin reached 73.7%, up 140 basis points, which the company attributed to price realization and channel and geographic mix "more than offsetting incremental pressure from tariffs and other product costs." North America wholesale revenue rose 22%, though roughly 15 points of that came from resumed shipments to a returning luxury account and a timing shift out of the prior quarter; European wholesale rose 8% in constant currency. Asia revenue rose 24% to $589m on comparable sales up 23%, with digital commerce up 32%. Inventory fell 3% in constant currency — nothing waiting to be marked down.
For the full fiscal year to March 2026, revenue grew 14.6% and operating income 26.5%, against revenue growth of 2.9% and 6.7% in the two preceding years.
What a broken meter looks like
PVH Corp, which owns Calvin Klein and Tommy Hilfiger and sells mostly through other retailers' order books, is the counter-example. June-quarter revenue fell 3.2% to $2.097bn, wholesale fell 6% across every region, Calvin Klein fell 7% and licensing revenue fell 13% — the royalty stream contracting rather than carrying the profit pool. The company also took a $439m non-cash goodwill impairment, and its spring-2027 European wholesale order book is already committed down mid-single digits. "We are really leaning into cost as a real driver of EBIT margin expansion," chief executive Stefan Larsson told investors on 3 September. PVH trades at 6.3x forward earnings and 0.73x book.
Oxford Industries, which sells Tommy Bahama and Lilly Pulitzer almost entirely through its own stores, restaurants and websites, is the third case and the cleanest demand signal. It fell 15.7% in the session after its 3 September report on 2.05m shares — roughly eight times the surrounding daily volume — after cutting full-year sales guidance to $1.43bn–$1.47bn and adjusted earnings to $1.60–$2.00 a share against $2.11 last year, while raising the quarterly dividend to $0.70, an annualized $2.80 the guidance no longer covers. Chairman and chief executive Thomas Chubb named the cause: "What we did this year is I think we just went too far too fast in shifting up the pricing tiers." Entry-level Lilly Pulitzer dresses under $200 went from about half the assortment to a third. Tommy Bahama comps turned positive. At 14.8x forward earnings on a consensus that has been cut 21%, it is the expensive one of the three.
The refunds nobody's margin earned
One reason reported profitability across the group is unreadable: the Supreme Court struck down tariffs imposed under the International Emergency Economic Powers Act on 20 February 2026, and refunds began flowing in April. PVH booked $107m in the June quarter — about $1.80 of earnings per share, leaving an underlying operating margin nearer 6% than the reported 11.1%. Oxford booked $42m, worth $2.07 of its $3.25 reported earnings per share. Ralph Lauren disclosed no such benefit; its margin gain is the only one of the three that the business itself produced.
The verdict
Two of the three de-ratings are earned. PVH's money is other retailers' commitments and those commitments are shrinking; Oxford priced its core customer out of its own dress racks and told investors spring 2027 is the first corrected season. Ralph Lauren's decline is the one nothing in the filings explains — sixteen analysts rated it a buy against two holds as of 10 September, and forward estimates have risen, not fallen. The likelier reading is a sector-wide repricing of discretionary consumption: over the same thirty days the S&P 500 exchange-traded fund rose 0.6% while Kontoor fell 21%, Lululemon 17%, Tapestry 16% and Nike 12%, with Abercrombie & Fitch the notable gainer.
What the reader is left holding is a valuation question rather than an operating one. At 18.3x forward earnings, down from 21.2x in August, Ralph Lauren is priced the way it was priced in 2024 and 2025, when it grew low single digits and its Asian business had not yet compounded at this rate. Either the market has decided that 15% price increases cannot repeat into a slowing consumer, or it has stopped distinguishing between the brand that raised guidance and the two that cut it.