

Accenture Put $1bn Behind Anthropic Evaluation Work, a Week Before Its 2027 Guidance
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
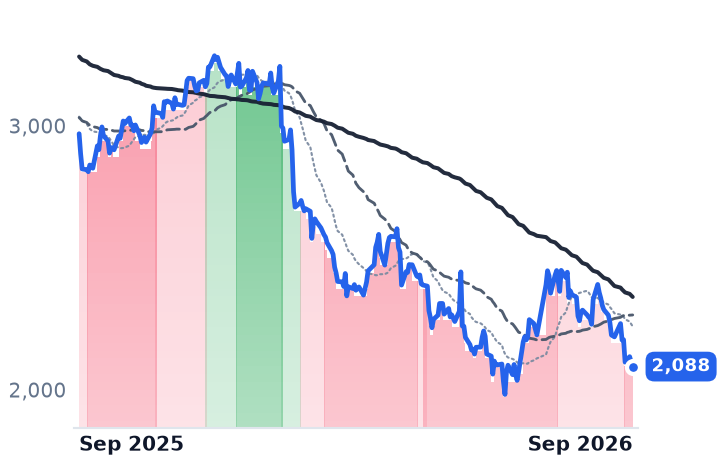
Accenture's shares have recovered 47% from their June low without the business improving: reported revenue growth slowed to 5.6%, new bookings fell 2% to $19.32bn, and the company retired the generative-AI bookings line investors had been using as a scoreboard. On 18 September it committed at least $1bn over five years to staff safety evaluations for Anthropic — work sold as a capability rather than a pool of billable hours.
The group splits. Cognizant is decelerating but raised full-year adjusted earnings guidance to $5.70-$5.82 a share. Genpact is the only member accelerating, with its outcome-priced segment up 24.1%, and it is the worst performer of the five over thirty days. Accenture gives its first fiscal-2027 guidance on 1 October.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
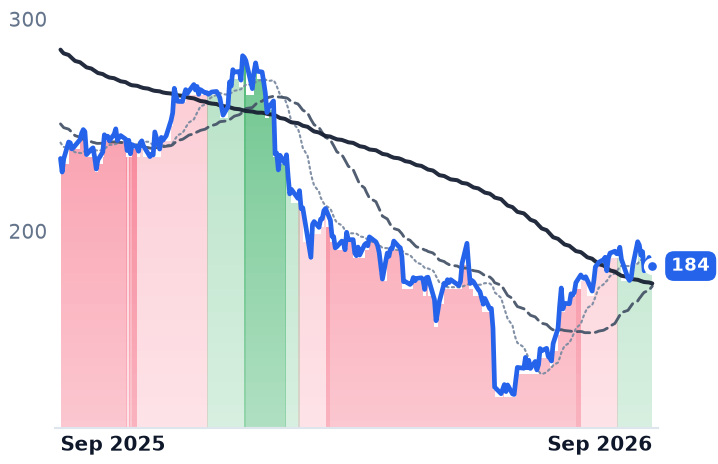
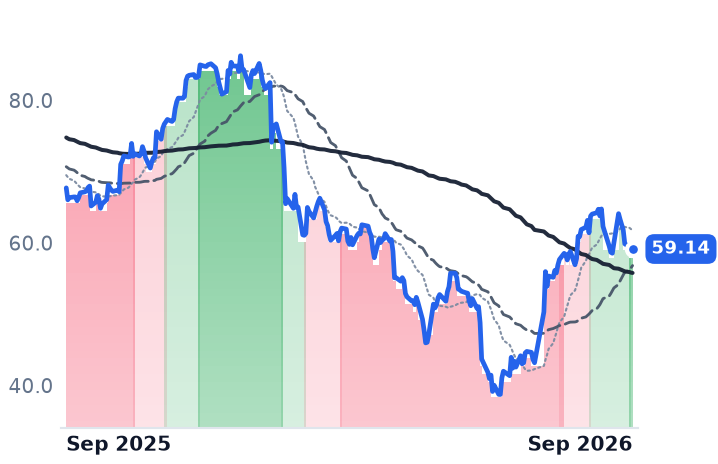
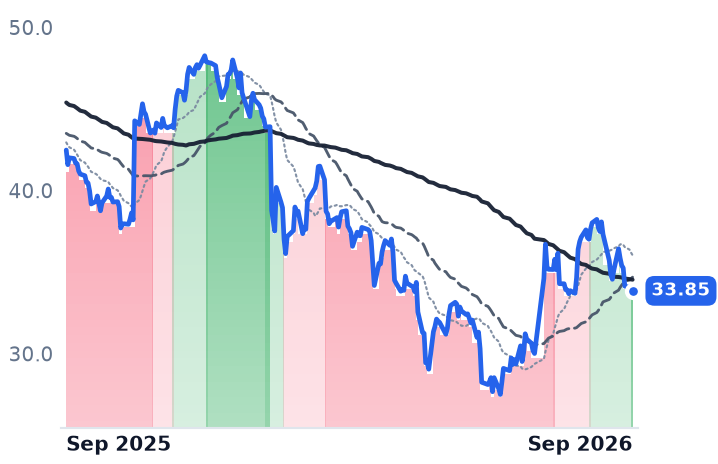
ACN | Accenture | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −2.2% | −21.7% |
CTSH | Cognizant Technology Solutions | Enterprise Consulting & Systems Integration | 🔴 Cont. Bear | −6.4% | −12.7% |
G | Genpact | Business Process & Analytics Services | 🔴 Cont. Bear | −8.8% | −20.3% |
| Compared against · context, not the story | |||||
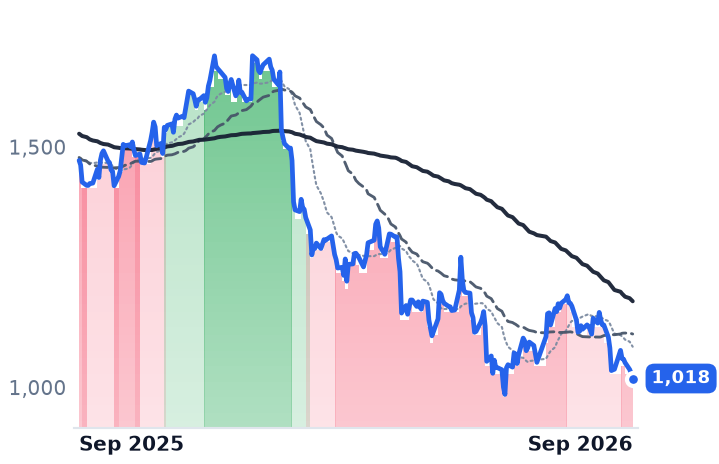
INFY.NS | Infosys | Information Technology Services | 🔴 Cont. Bear | −9.6% | −30.8% |
TCS.NS | Tata Consultancy Services | Information Technology Services | 🔴 Cont. Bear | −8.2% | −29.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACN | $112.3B | 14.5x | 12.5x | 1.5x | 1.5x | 4.8x | 4.6x | 8.7x | 11.2% |
CTSH | $26.6B | 12.7x | 10.3x | 1.2x | 1.2x | 3.8x | 3.8x | 7.0x | 9.8% |
G | $5.7B | 10.0x | 8.2x | 1.1x | 1.1x | 3.0x | 2.9x | 7.5x | 10.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INFY.NS | $4.7T | 15.0x | — | 2.5x | — | 8.1x | — | 9.6x | 7.7% |
TCS.NS | $8.6T | 17.2x | 15.4x | 3.1x | 2.9x | 8.2x | 7.8x | 11.8x | 5.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ACN | Revenue | +5.9% | +3.9% | +4.9% |
| EPS | +7.6% | +5.7% | +7.0% | |
CTSH | Revenue | +5.2% | +4.7% | +5.2% |
| EPS | +10.8% | +9.8% | +10.5% | |
G | Revenue | +7.3% | +7.1% | +8.0% |
| EPS | +13.9% | +9.6% | +11.8% | |
INFY.NS | Revenue | +0.4% | +5.9% | +3.7% |
| EPS | +1.6% | +5.7% | +4.5% | |
TCS.NS | Revenue | +4.0% | +8.9% | +3.9% |
| EPS | +4.0% | +9.1% | +4.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Accenture agreed on 18 September to commit at least $1bn over five years to a new kind of staffing: teams of embedded evaluators who red-team models, run alignment assessments and test safeguards. The counterparty, the AI developer Anthropic, committed the same amount, and the arrangement is non-exclusive on both sides. Accenture's Faculty unit leads the work; the shares rose about 6% premarket.
That matters because of how Accenture — the Dublin-based firm that sells strategy, systems integration, cloud and outsourced operations to large corporates and governments, with 799,000 employees — actually earns money. Revenue is headcount multiplied by utilization multiplied by a realized bill rate. Every hour software automates is an hour nobody invoices, which is the entire bear case on the industry and the reason the stock fell nearly 18% in one session on 18 June, its worst day on record, after management trimmed full-year local-currency growth guidance to 3-4% citing weak US federal work. On Thursday 1 October, at 8:00 a.m. Eastern, Accenture reports its fiscal fourth quarter and issues its first full-year fiscal-2027 guidance.
What the last print actually said
Reported revenue growth decelerated to 5.6% in the May quarter, roughly 3% in local currency. New bookings fell 2% to $19.32bn, split $10.26bn consulting and $9.06bn managed services — so the hour-billed half booked more work while the outcome-priced half grew faster, 5% in local currency against consulting's 1%. Gross margin slipped to 32.77% from 32.87%.
The labor meters, though, look healthy. Utilization rose to 93% from 92%, attrition excluding involuntary terminations fell to 14% from 16%, and headcount grew about 1% against 5.6% revenue growth — revenue per employee of $91,489, up 5.7% over twelve months. "Demand for large scale reinvention remains strong—104 quarterly client bookings of $100 million or more year-to-date, up 13%," chair and chief executive Julie Sweet said on 18 June. What vanished that day was the scoreboard: Accenture retired its advanced-AI bookings disclosure, arguing AI now runs through everything it sells, after cumulative bookings of about $11.5bn since 2023.
The mirror and the control
Cognizant, the Teaneck outsourcer whose delivery is mostly offshore across financial services, healthcare, products and communications, tells the same story in a different accent. June-quarter revenue of $5.5bn grew 4.5%, decelerating, with gross margin down 30 basis points and net income off 1.4% — yet adjusted operating margin expanded for a sixth straight quarter and full-year adjusted earnings guidance was raised to $5.70-$5.82 a share. Headcount fell 900 sequentially to 356,700. "Our organic revenue growth momentum continued in the second quarter and was at the high end of our expectations," chief executive Ravi Kumar S said on 29 July. The shares fetch 10.28x forward earnings, below the roughly 14-15x they carried in May.
Genpact is the test that breaks the thesis it was meant to prove. The former General Electric back office runs accounts payable, record-to-report and procurement for banks and insurers, and it is the only member of this group accelerating — revenue growth of 5.6%, then 6.7%, then 7.1% — with gross margin widening to 36.50%. Its Advanced Technology Solutions segment rose 24.1% to $363.3m, 27% of revenue, sold as annuitized recurring contracts with minimum volume commitments rather than per-person billing; chief executive Balkrishan Kalra told investors the firm is on track for more than $1bn of agentic contract value in 2026. The legacy back office grew about 2%. Genpact trades at 8.22x forward earnings and is the worst thirty-day performer of the five names here, down 9.9%.
What the rebound is made of
From the 22 June low Accenture has recovered 47% and Cognizant 41%, while Infosys and Tata Consultancy Services — running the same offshore pyramid, and sold just as hard on the day Accenture cut guidance — fell 4.4% and 1.9% over the same stretch. Delivery model did not separate them; listing venue and the direction of consensus revisions did. Over the past thirty days all five fell.
So the honest split: the business earns the part of the recovery attributable to pricing discipline — utilization at 93%, falling attrition, revenue per employee up 5.7% while the payroll barely grew. It does not earn the rest. Accenture at 14.54x trailing earnings against 21.4x at its fiscal-2025 year-end is a de-rated share price partly restored, not an order book reaccelerating; consensus itself models fiscal-2027 revenue growth of 3.9%. And Genpact proves the labor meter is not what is being repriced: the one company whose revenue is least tied to the hour is the one being sold hardest.
Accenture spends around $9bn a year buying capability — $4.18bn of it this year on three operational-technology security firms — and has now agreed to spend $1bn more on evaluators it did not previously employ. Next Thursday it has to say what all of that is worth in fiscal 2027, without the AI bookings number it used to publish.