

Clearway Cut 2026 Cash Guidance 8% on Weak Wind and Kept Its $2.70 Target for 2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Clearway's shares have fallen since late June, and the reason is weather, not the price of power. The company trimmed the midpoint of its 2026 cash available for distribution guidance by about 8%, to $430–470m, on wind and solar output that came in below normal — while leaving the 2027 target of $2.70 a share untouched.
Nothing in the contract book deteriorated: roughly 90% of generation is sold under agreements averaging about 12 years of remaining life, the three Texas wind farms were restructured past 2040 in June, and North American wind power purchase agreements hit a record $79.40 per megawatt-hour. What did change is the discount rate, and a funding plan that still needs most of $1bn of equity.
The two names filed beside Clearway do not share the story. XPLR is up over twelve months while paying no distribution at all; Sunrun is down by nearly half on a repealed tax credit that touches neither of the others.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CWEN | Clearway Energy | Wind & Solar Developers | ⚠️ Emerging Bear | −5.0% | +11.0% |
XIFR | XPLR Infrastructure | Renewable & Infrastructure Assets | 🟢 Cont. Bull | −4.2% | +10.2% |
RUN | Sunrun | Residential Solar Installers | 🔴 Cont. Bear | −1.5% | −46.6% |
| Compared against · context, not the story | |||||
ENPH | Enphase Energy | Inverters & Power Electronics | 🔴 Cont. Bear | −7.4% | −7.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWEN | $6.3B | 40.3x | — | 4.0x | 3.8x | 7.6x | 7.2x | 14.3x | 10.7% |
XIFR | $1.0B | 16.1x | 9.5x | 0.9x | 0.8x | 4.9x | 4.4x | 8.8x | -62.2% |
RUN | $2.1B | 5.1x | 6.9x | 0.6x | 0.7x | 1.7x | 1.9x | 23.4x | -65.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENPH | $4.9B | 36.1x | 18.4x | 3.7x | 4.1x | 7.8x | 8.7x | 27.9x | 3.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CWEN | Revenue | +14.5% | +11.5% | +12.2% |
| EPS | −116.0% | −318.9% | +60.4% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −849.6% | −44.0% | −144.3% | |
RUN | Revenue | +29.7% | +3.5% | +12.9% |
| EPS | −8.2% | −65.9% | −38.3% | |
ENPH | Revenue | −19.1% | +6.2% | +10.8% |
| EPS | −28.8% | +14.0% | +18.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Clearway Energy told investors on August 5 that its wind turbines and solar farms had produced less power than a normal year, and cut its 2026 guidance for cash available for distribution — the money a generation owner can actually pay out — to $430–470m from $470–510m, about 8% off the midpoint. In the same release it left the 2027 target of $2.70 a share, and the 2030 range of $2.90–3.10, exactly where they were.
That combination is the whole question in contracted renewables right now. Clearway owns roughly 5,000 net megawatts of wind and solar plus about 2,500 net megawatts of California gas, sells nearly all of it forward, and is judged on a cash figure that a bad wind year can dent without touching a single contract. Its shares have fallen 16.2% over three months. If the cut were a repricing of what renewable output is worth, the contracts would show it. They do not.
The operating record
The June quarter was, on the income statement, the strongest in some time: revenue of $481m, up 22.7%, with operating income of $116m, up 36.5%. Cash available for distribution was $167m. "While we are lowering our 2026 financial guidance due to factors outlined in our mid-July operational preview, our team is focused on maintaining our trademark operational excellence to uphold our historic track record of meeting our financial targets," said Craig Cornelius, president and chief executive, in the August 5 results release.
The contract meters are intact. As of March 31 the weighted-average remaining life of the renewables and storage offtake agreements was approximately 12 years, with roughly 90% of generation sold to mostly investment-grade counterparties, per the first-quarter filing. The three Texas wind farms were restructured in June at better pricing and terms running past 2040. In January Clearway signed 1.17 gigawatts of twenty-year agreements with Google across three states, more than $2.4bn of investment with first power in 2027. Industry pricing agrees: LevelTen's index put North American wind agreements at a record $79.40 per megawatt-hour, with wind up 17.5% year on year in the second quarter even as solar slipped 4.8% from its own record.
What is actually repricing
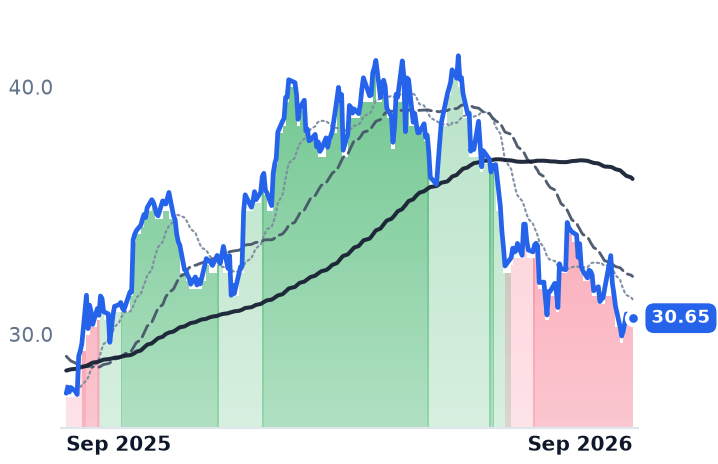
Rates. The Federal Reserve raised its target 25 basis points on September 16 to 3.75–4.00%, its first increase since 2023, and the thirty-year Treasury reached 5.29% — the highest reading since 2007, the same move this page described last week. Clearway's $0.4750 quarterly dividend annualizes to $1.90, a 6.20% yield at $30.65, leaving barely 90 basis points over a government bond. The shares changed character in the summer: the 50-day average sat above the 200-day through late June and has been below it since July.
The second pressure is self-inflicted arithmetic. Clearway plans to issue $0.5–1.0bn of external equity through 2029 and has raised roughly $50m so far. Cornelius told the quarterly call the company acts on acquisitions when its cost of capital is "especially accretive" and steps out "when it's not where we'd want it to be." At 0.68 times book and 14.3 times trailing earnings before interest, taxes, depreciation and amortization, it is not where he would want it.
The two names beside it
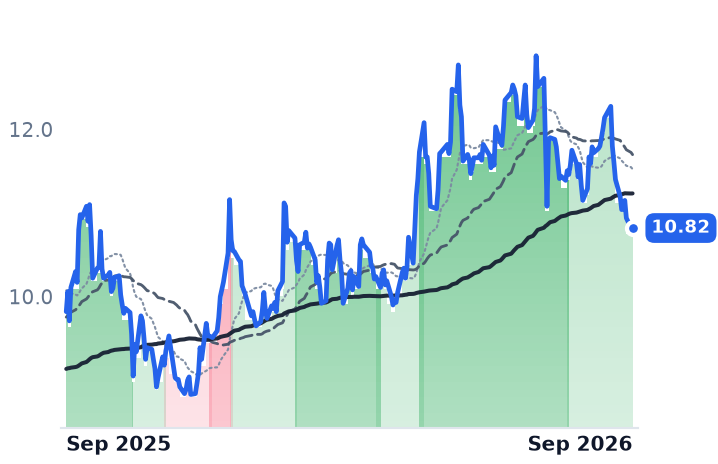
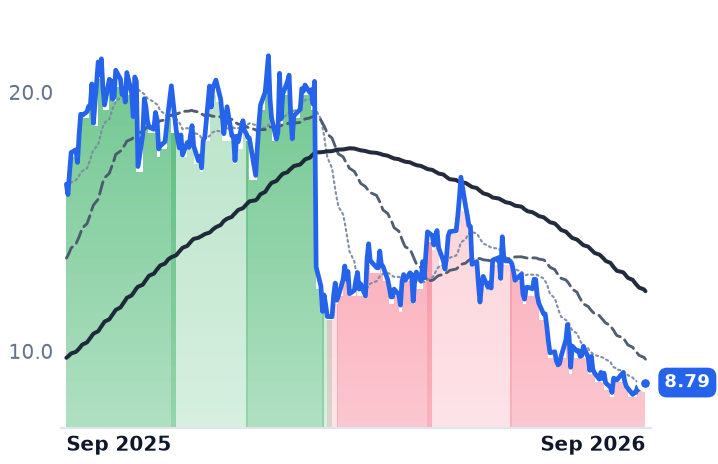
They are not the same business. XPLR Infrastructure, the former NextEra yieldco that suspended its distribution and now funds itself, is up 10.2% over twelve months paying nothing; its $1.02bn market value stands against $600–700m of guided free cash flow before growth and 0.32 times book, which prices the roughly $2.8bn of maturities and convertible-equity-portfolio-financing buyouts still to clear — only a $150m buyout and a $500m note repayment are done. Sunrun, the residential installer, is down 46.6% over the year because Congress repealed the Section 25D homeowner credit for systems placed in service after December 31, 2025, with no phase-down; its net subscriber value fell to $9,444 from $17,004 and cash generation guidance came down to $200–375m. Neither mechanism touches a megawatt-hour sold into a wholesale market.
The verdict
Clearway earns part of its decline. A resource miss is real cash, and a fleet that depends on wind is entitled to a bad wind year. What the operating record does not explain is a 19.6% fall over six months against lengthening contracts, record contract pricing and a 13.5-gigawatt sponsor pipeline; the likelier reading is the discount rate plus an equity plan the market can see coming. At $30.65 the shares are 11.4 times a 2027 cash target management reaffirmed in the same breath as the cut.
Which leaves one uncomfortable loop. Most of that $1bn of equity is still unissued, and the chief executive has said plainly that Clearway steps out when its own shares are not where he wants them.