

Alcon's Implant Sales Grew 1% as Bausch + Lomb's Premium Lens Revenue Nearly Tripled
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
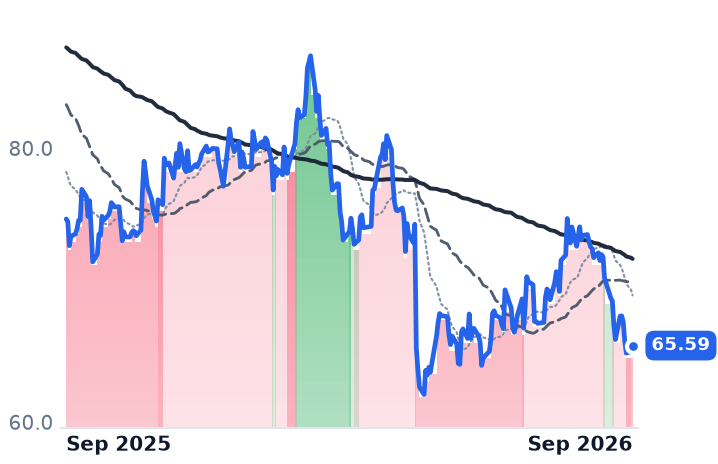
Cataract patients are buying the out-of-pocket lens upgrade faster than they ever have — and the company that invented the category captured almost none of the increase. Alcon's advanced-technology lens penetration rose about 180 basis points in the US last quarter against a historical run-rate near 50, yet its implantable revenue barely moved, while Bausch + Lomb's surgical segment grew 16% and its premium portfolio went from 6% to 13% of that segment's sales.
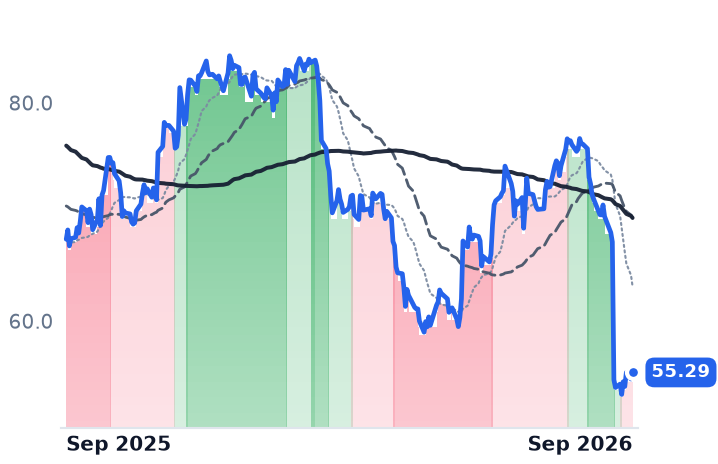
Alcon raised 2026 core earnings growth guidance to 12–15% in constant currency and still de-rated to 19 times forward earnings, from roughly 27 times in January 2025. Cooper Companies is the opposite case: it cut its contact-lens growth guidance for the second time in two quarters and lost a fifth of its value in one session. One of these de-ratings was earned on the day; the other is still looking for its reason.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ALC | Alcon | Eye Care Devices & Lenses | 🔴 Cont. Bear | −11.0% | −12.4% |
COO | The Cooper Companies | Eye Care Devices & Lenses | 🔴 Cont. Bear | −27.1% | −18.1% |
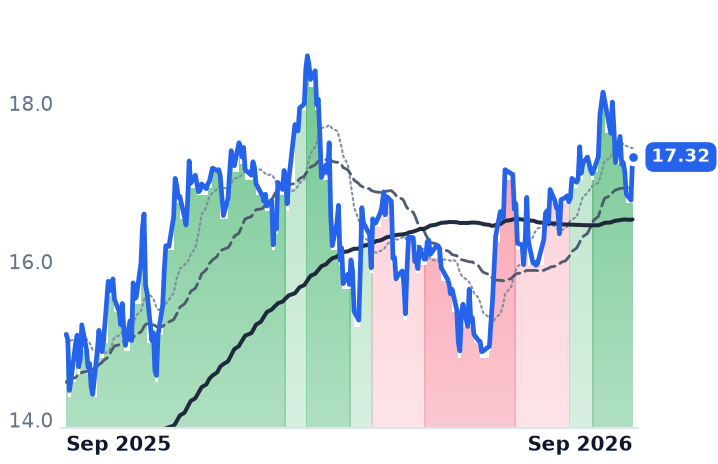
BLCO | Bausch + Lomb | Eye Care Devices & Lenses | 🟢 Cont. Bull | +0.0% | +14.9% |
| Compared against · context, not the story | |||||
STAA | STAAR Surgical | Eye Care Devices & Lenses | ⚠️ Emerging Bear | −11.2% | −22.2% |
SYK | Stryker | Orthopedic Implants & Trauma | 🔴 Cont. Bear | −15.7% | −25.5% |
ABT | Abbott Laboratories | Other | 🌱 Emerging Bull | −11.1% | −22.5% |
BSX | Boston Scientific | Spinal Surgery & Neuromodulation | 🔴 Cont. Bear | −8.3% | −54.0% |
GEHC | GE HealthCare Technologies | Diagnostic Imaging & Devices | ⚠️ Emerging Bear | −10.7% | −11.0% |
TFX | Teleflex Incorporated | IV & Vascular Access | 🟢 Cont. Bull | −9.7% | +2.9% |
BAX | Baxter International | Dialysis & Infusion Therapy | 🟢 Cont. Bull | −10.6% | +3.7% |
ZBH | Zimmer Biomet | Orthopedic Implants & Trauma | 🌱 Emerging Bull | −7.2% | −5.9% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.3% | +17.3% |
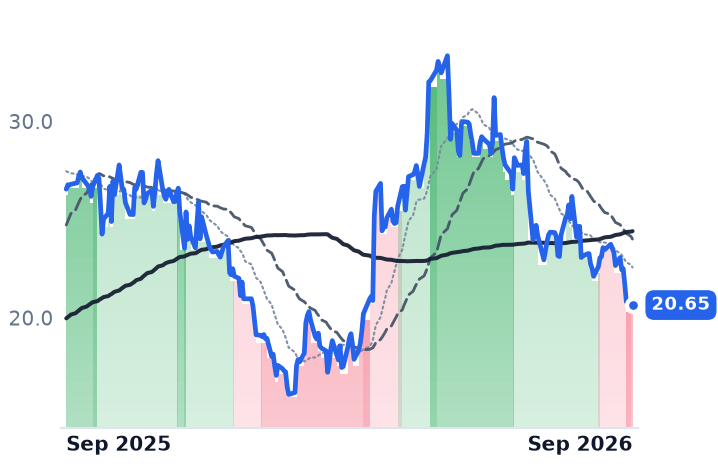
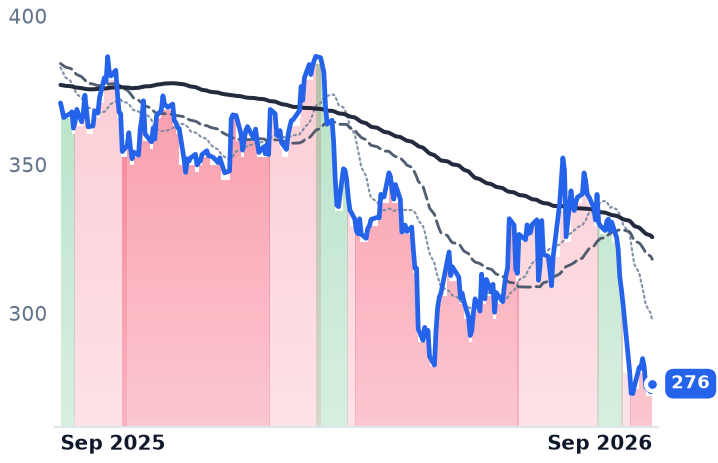
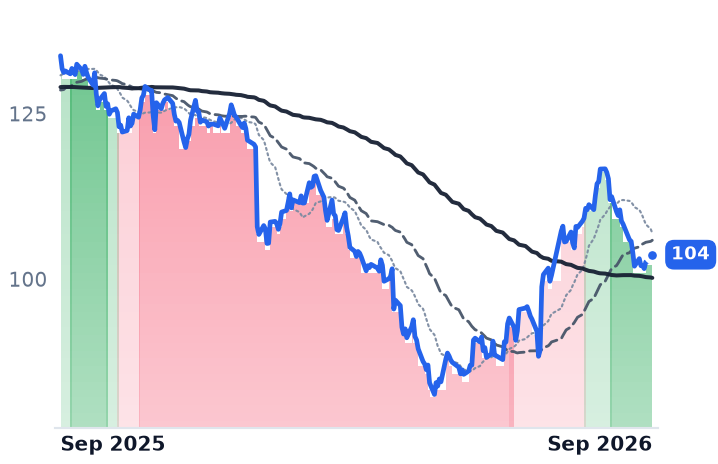
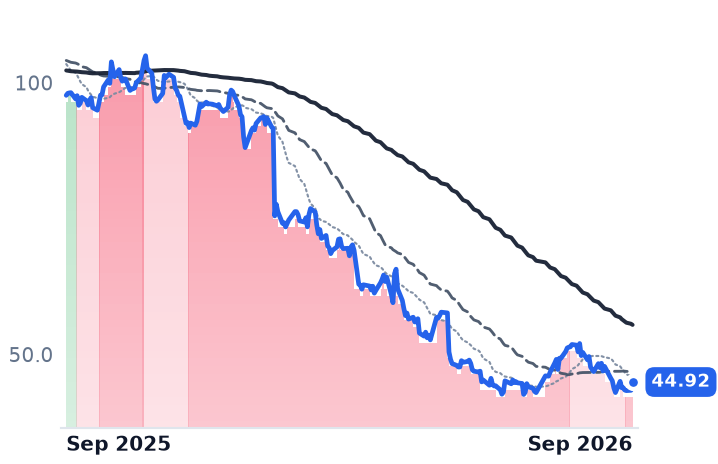
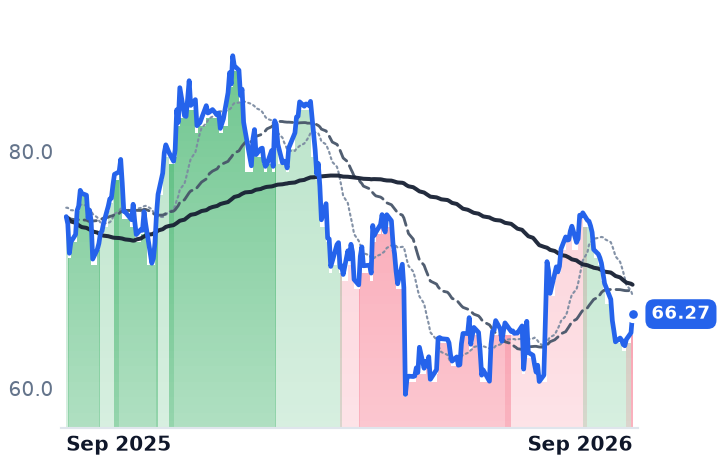
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALC | $32.0B | 50.5x | 19.0x | 3.0x | 2.9x | 5.2x | 5.2x | 17.8x | 5.3% |
COO | $10.8B | 18.9x | 12.2x | 2.5x | 2.5x | 4.0x | 4.0x | 14.5x | 6.3% |
BLCO | $6.2B | n/m | 21.8x | 1.2x | 1.1x | 2.0x | 2.0x | 14.7x | 2.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
STAA | $1.6B | n/m | 49.2x | 5.5x | 4.8x | 7.2x | 6.3x | 100.9x | -3.5% |
SYK | $105.5B | 28.3x | 18.3x | 4.1x | 3.9x | 6.3x | 5.9x | 18.7x | 4.5% |
ABT | $147.1B | 23.5x | 15.4x | 3.3x | 2.9x | 5.8x | 5.2x | 16.1x | 5.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BSX | $63.9B | 17.3x | 13.1x | 3.0x | 3.0x | 4.3x | 4.2x | 13.4x | 5.7% |
GEHC | $27.6B | 18.4x | 12.4x | 1.4x | 1.3x | 3.3x | 3.0x | 11.3x | 5.5% |
TFX | $5.8B | n/m | 18.3x | 2.2x | 2.6x | 4.2x | 4.8x | n/m | 6.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BAX | $8.9B | n/m | 9.0x | 0.8x | 0.8x | 2.6x | 2.6x | 22.3x | 8.0% |
ZBH | $18.4B | 23.1x | 11.2x | 2.2x | 2.1x | 3.1x | 3.1x | 13.0x | 9.9% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ALC | Revenue | +6.6% | +5.9% | +6.0% |
| EPS | +12.7% | +13.5% | +13.0% | |
COO | Revenue | +3.7% | +4.1% | +4.9% |
| EPS | +10.9% | +3.6% | +8.4% | |
BLCO | Revenue | +8.2% | +5.9% | +5.5% |
| EPS | +50.1% | +38.4% | +32.4% | |
STAA | Revenue | −25.2% | +29.5% | +8.4% |
| EPS | −96.8% | +2797.8% | +46.7% | |
SYK | Revenue | +8.7% | +8.8% | +7.8% |
| EPS | +10.6% | +11.6% | +11.3% | |
ABT | Revenue | +12.8% | +9.0% | +7.3% |
| EPS | +6.2% | +10.7% | +11.6% | |
BSX | Revenue | +6.2% | +4.4% | +7.0% |
| EPS | +8.3% | +3.9% | +10.8% | |
GEHC | Revenue | +6.1% | +4.7% | +4.7% |
| EPS | +7.7% | +10.6% | +11.4% | |
TFX | Revenue | −31.2% | +4.3% | +4.6% |
| EPS | −48.6% | +52.0% | +10.6% | |
BAX | Revenue | +2.5% | +2.0% | +2.7% |
| EPS | −18.8% | +3.8% | +7.6% | |
ZBH | Revenue | +4.7% | +3.6% | +4.0% |
| EPS | +4.4% | +6.3% | +7.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
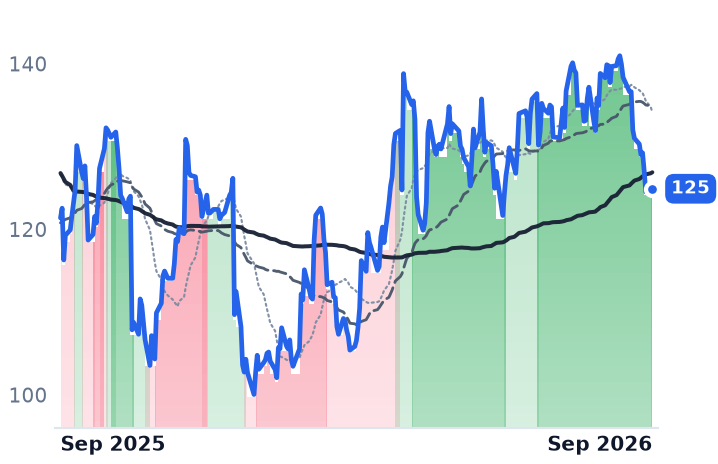
Alcon lifted its full-year profit outlook on August 11 and its shares have drifted lower nearly every week since, from $74.87 on the day of the results to $65.59. There was no single session that did the damage. The Geneva-based company — which sells cataract-surgery consoles, the lenses implanted during that operation, and contact lenses and dry-eye drops on the other side of the house — told investors its core operating margin had widened 160 basis points to 20.6%, its core gross margin had reached 64.7%, and that 2026 core earnings would now grow 12–15% in constant currency rather than the range it had guided to before.
What is actually at issue is one product: the advanced-technology intraocular lens, the upgrade a cataract patient pays for out of pocket on top of the reimbursed standard implant. Alcon's own arithmetic makes it the most valuable dollar in the business — management puts one point of upgrade penetration at $15m of revenue, against $10m for a point of overall market growth. In the second quarter that penetration rose about 180 basis points in the US and 110 globally, against a historical average near 50. The patient upgrade is accelerating at three times its normal pace.
The implant line did not follow
Alcon's surgical franchise grew 7% to $1.6bn, but the growth came from hardware and disposables: equipment up 25% on its UNITY console, consumables up 5%, and implantables up 1%, with intraocular lenses up 2% "despite competitive pressure." US cataract procedure volumes were flat in the quarter on the company's own estimate, below what it would normally expect, with international volumes up low single digits.
The missing dollars are findable. Bausch + Lomb — the 1853-vintage eye-health company that is still roughly 87% owned by Bausch Health, and that sells lens care, prescription eye medicines and surgical implants — reported revenue up 9% to $1.394bn and raised its own full-year guidance, with surgical the fastest-growing of its three end markets at 16%. Inside it, premium intraocular lenses grew 175% and the premium portfolio moved from 6% of surgical revenue to 13% in a year. Alcon still owns the socket — a 2026 practitioner preference survey puts its Vivity lens first at 39.7% and Clareon PanOptix Pro at 34.5%, ahead of Johnson & Johnson's Tecnis Odyssey at 24% and Bausch + Lomb's enVista Envy at 17% — but the newest entrant is where the growth rate is.
Alcon's response has been speed of conversion rather than price. "Nearly all PanOptix accounts have been converted to PanOptix Pro with the platform now representing approximately 90% of PanOptix implants," chief executive David Endicott told investors on the August 11 call. On why faster surgery sells more lenses, he was blunter: "If you can imagine doing 20 cataracts in a day, you'd probably do 21."
What the sector did to the price
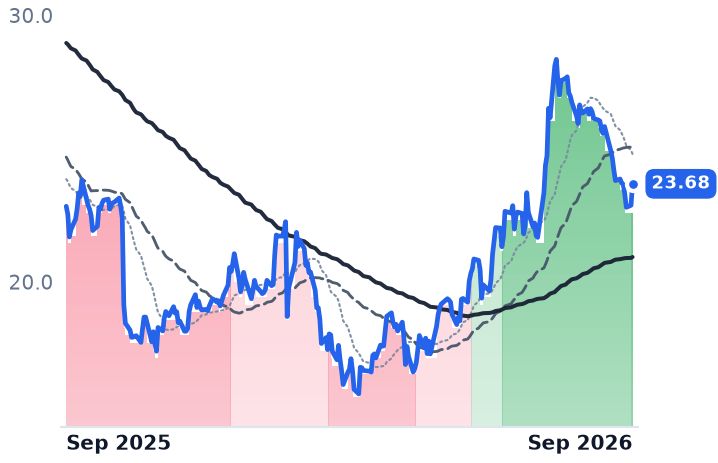
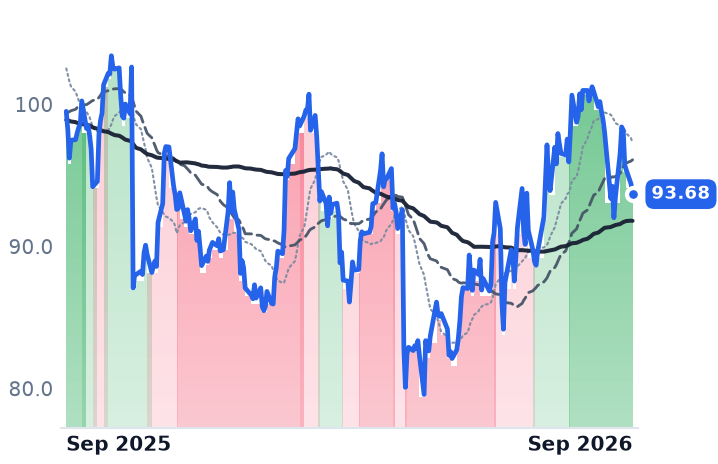
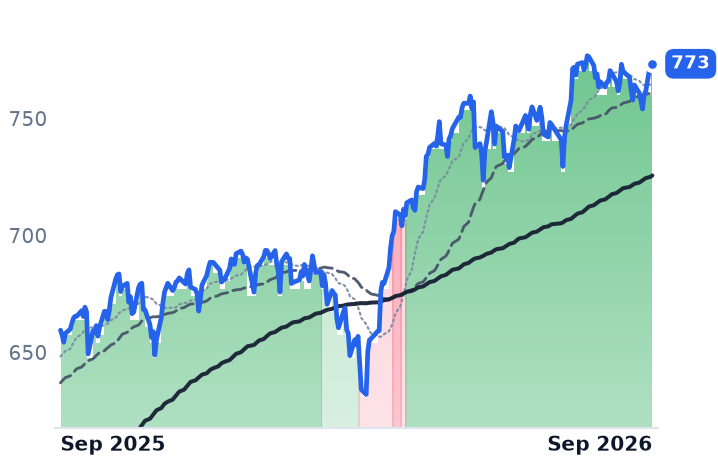
Alcon's 10.9% slide over the past month sits inside a medical-device drawdown, not outside it: Stryker fell 16.1%, GE HealthCare 11.4%, Abbott 11.1% and Boston Scientific 10.8% over the same stretch while the S&P 500 exchange-traded fund rose 1.0%. The named mechanism is trade policy — the US Commerce Department opened a Section 232 national-security investigation into imports of medical equipment, devices and protective equipment on September 2, a process that can run up to 270 days. A Swiss manufacturer shipping into the United States is the most exposed of this group; Alcon already assumes a 10–12.5% duty on US imports through year-end and expects a $60m tariff refund in the third quarter, about $40m of which it plans to spend on launches.
The de-rating that was earned in a day
Cooper Companies, which sells CooperVision contact lenses alongside a CooperSurgical fertility and women's-health unit, fell 18.8% on September 10, from $67.26 to $54.62. CooperVision revenue was flat at $717m, the company cut full-year CooperVision growth guidance for the second time in two quarters, from a peak of 4.5–5.5% to 1–2%, guided the fourth quarter to between minus 2% and flat, and the board ended a sale process by keeping CooperSurgical. Chief executive Albert White attributed the shortfall to a deliberate reduction of US channel inventory: "The consumption in the U.S. market here has been running pretty steady all year in the mid-single digits… So the entire reason for the reduction in the revenue guidance for CooperVision was tied to just channel inventory. That's it." He also conceded the commercial gap — "we don't have enough salespeople out there. Like, hindsight 20/20, we should have moved faster on this" — and is adding coverage at more than 5,000 additional retail doors. Brokers marked it down accordingly, with JPMorgan cutting its target to $58 from $71 and Stifel to $70 from $85.
Where the three now trade separates them further. Alcon changes hands at 19 times forward earnings against roughly 27 times in January 2025, with consensus still modeling $3.45 of 2026 earnings per share, up nearly 13%; its trailing multiple is meaningless because reported operating income collapsed to $11m on the discontinuation of its PowerVision accommodating-lens programs. Cooper is the cheapest at 12.2 times forward, down from about 22 times, with record quarterly free cash flow of $273m and leverage under two times. Bausch + Lomb, still loss-making on a reported basis, trades at 21.8 times forward earnings — down from roughly 34 times in January 2025 even though the shares are up 13.6% over twelve months, because the estimates grew faster than the price.
The verdict
The common label over these three companies is doing no work. Bausch + Lomb has risen on every horizon measured; Cooper's fall is dated, explained and priced; only Alcon's decline lacks an author. Roughly speaking, the sector's tariff drift accounts for most of it — Alcon's month looks like Abbott's. What the business genuinely owes is the implant line: the premium upgrade is compounding faster than it ever has, and a competitor with a lens approved in December 2024 is taking a visible share of the increase while Alcon's implantable revenue rounds to no growth at all.
That changes what the next print has to prove. Margin expansion and console placements are no longer the question; the question is whether the company that defined the premium cataract lens can keep the patient's own money flowing through its own product. The upgrade is selling better than ever. Whose lens goes in is suddenly open.