

Vistra's First Gas Data-Center Contract Starts in a Year It Has 94% Sold Forward
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Vistra has finally contracted data-center load out of its gas fleet rather than its nuclear plants — and the power does not flow until the third quarter of 2027, a year it had already sold roughly 94% of its generation forward as of early August. The contract is real; most of its margin is deferred.
The two Texas merchant power names are no longer one story. Vistra's June quarter showed revenue down 5.5% to $4.02bn but gross margin up to 23.5% from 22.0%, with 2026 adjusted EBITDA guidance of $6.8–7.6bn reaffirmed. NRG's revenue rose 64% on an acquired fleet while gross margin fell to 14.5% from 16.5%, adjusted earnings per share slipped to $1.49, and the diluted share count went from 190.4m to 210.0m. Vistra's price is discounting something its results do not show. NRG's is discounting something they do.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +3.8% | −30.9% |
NRG | NRG Energy | Integrated Retail & Generation | 🔴 Cont. Bear | −7.7% | −38.1% |
| Compared against · context, not the story | |||||
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | −3.3% | −21.3% |
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | −3.7% | −30.5% |
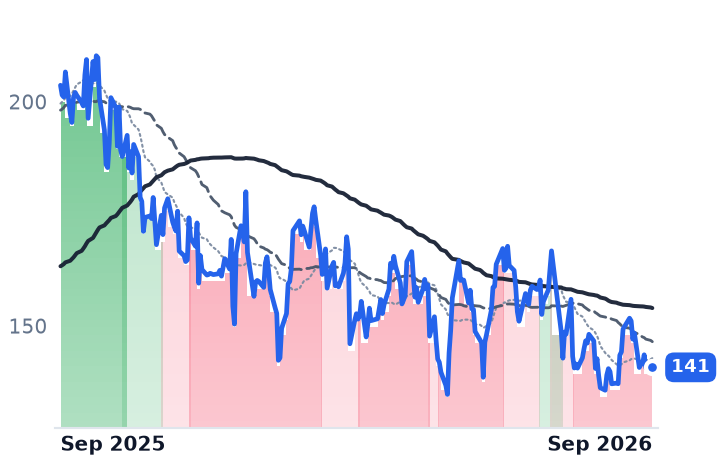
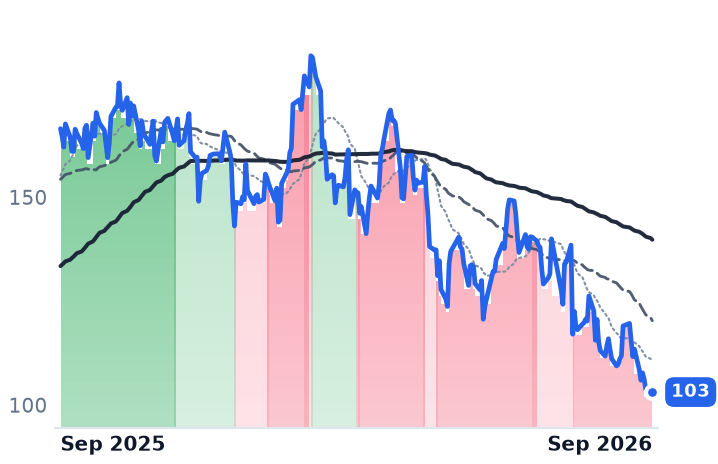
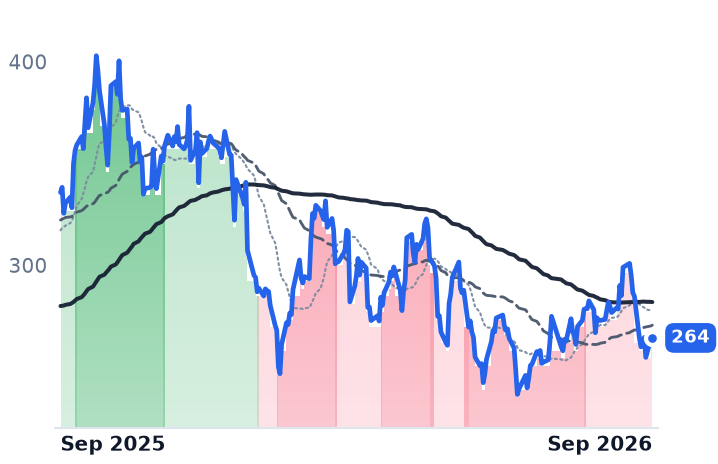
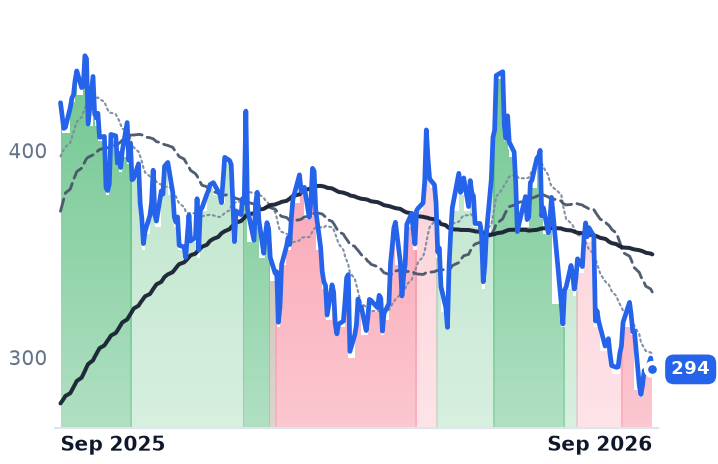
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VST | $47.3B | 23.4x | 16.5x | 3.0x | 2.1x | 22.8x | 16.4x | 10.3x | 2.9% |
NRG | $21.7B | 26.9x | 11.6x | 0.6x | 0.6x | 3.6x | 3.8x | 10.6x | 1.6% |
CEG | $94.6B | 25.6x | 21.8x | 3.0x | 2.8x | 3.2x | 3.0x | 13.9x | 0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $14.2B | n/m | 15.2x | 4.0x | 3.2x | 9.0x | 7.2x | 29.6x | 3.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VST | Revenue | +15.7% | +10.2% | +4.8% |
| EPS | +78.3% | +20.0% | +18.4% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
CEG | Revenue | +36.6% | +2.7% | +5.5% |
| EPS | +28.9% | +10.4% | +26.4% | |
TLN | Revenue | +84.0% | +15.8% | +4.6% |
| EPS | +247.6% | +48.4% | +17.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
On September 21 Vistra's Luminant marketing arm signed a 20-year agreement to supply up to 207 megawatts to the first phase of a Permian Basin data center being developed by New Era Energy & Digital. The power comes from Vistra's 1,180 MW gas-fired plant at Odessa, immediately adjacent to the 493-acre site, and Vistra takes a 5% non-voting interest in the supplied portion of the campus once deliveries begin, along with a right of first refusal on later development there.
It is the first data-center load Vistra — a $47bn generator running about 38,700 MW of nuclear, gas, coal, solar and batteries alongside a retail book of roughly 4.3 million customers — has contracted out of its gas fleet rather than out of its PJM nuclear plants. That matters mostly for when the money arrives. Deliveries begin in the third quarter of 2027, and as of August 3 Vistra had already hedged approximately 100% of expected 2026 generation, about 94% of 2027 and about 72% of 2028. A contract signed today reaches the income statement through the thin unhedged residual of 2027 and the open tail beyond it. Twenty years of contracted load is a balance-sheet event long before it is an earnings one.
What the Texas market actually pays
Chief executive Jim Burke has been blunt about the spot economics. ERCOT wholesale power around $30 a megawatt-hour, he told investors on the second-quarter call, is "not going to get new stuff built". Burke has held his forecast of 115 to 120 gigawatts of ERCOT load in 2030 unchanged since May 2024 "even though the queues have certainly grown" — management is discounting the announced interconnection pipeline, not underwriting it. The fuel-free revenue line is capped too: PJM's capacity auction announced in July cleared at $325 per megawatt-day for a third consecutive auction, 2.5% below the prior $333.44, and federal regulators have extended that collar through the next auction, which closes December 15.
Against that backdrop Vistra's reported business has held. June-quarter revenue fell 5.5% to $4.02bn, the fourth consecutive quarterly decline, yet gross margin rose to 23.5% from 22.0% and operating margin to 13.8% from 12.1%; adjusted EBITDA rose about 30% to $1.77bn and the 2026 guidance range of $6.8–7.6bn was reaffirmed, with a 2027 range of $7.4–7.8bn set last November still standing. The shares are down 35.4% over twelve months. Vistra trades at 10.29 times trailing enterprise value to EBITDA against 13.93 times for Constellation Energy, the nuclear-weighted comparison, and at 16.46 times forward earnings against 23.44 times trailing — earnings multiples distorted by hedge accounting, which swung 2025 diluted earnings per share to $2.21 from $7.00.
NRG's deterioration is in the accounts
NRG, a Houston supplier selling power, gas and smart-home services to roughly six million customers, is the opposite case. June-quarter revenue rose 64% to $11.06bn — bought, through the roughly $12.0bn LS Power fleet acquisition funded with $4.9bn of new notes and stock — while gross margin fell to 14.5% from 16.5%. Texas segment margin absorbed a 13% rise in the cost to serve retail load, a $77m hit, plus $45m of lost load from customer mix and attrition; Houston round-the-clock power averaged $33 a megawatt-hour against a 2026 planning assumption of $52. Diluted shares rose from 190.4m to 210.0m as acquisition stock swamped buybacks. The bright line is Vivint Smart Home, which delivered $301m of adjusted EBITDA and 2.45 million customers, up 8%. NRG closed at $102.55 on September 21, its lowest close of the year, days after Morgan Stanley trimmed its target to $159. Its flagship 1.2 GW hyperscaler plant still has no final investment decision and targets operation in late 2029.
Treating these two as one merchant-power trade no longer survives the evidence. Over the past month Vistra rose 3.8% while NRG fell 7.8%. Vistra's guidance is intact, its nuclear output is floored by a federal credit that only phases out above $25 a megawatt-hour, and it now has dated contracted megawatts — Meta from late 2026, Amazon Web Services from late 2027, New Era from mid-2027. NRG's de-rating is earned by margin compression and dilution; what is no longer obvious is how much further it should run, with the shares at 11.56 times forward earnings, roughly half Constellation's, and 2026 guidance of $5.325–5.825bn in adjusted EBITDA reaffirmed.
Texas is about to make the distinction between announced and signed megawatts a matter of public record: the grid operator's audit of every data center in its interconnection queue, ordered by Governor Greg Abbott, is due by December 10. Vistra has one contract with a delivery date. Most of the queue has a press release.