

Cactus' Best Quarter Came From Baker Hughes' Old Business; It Guides That Unit Down 10%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
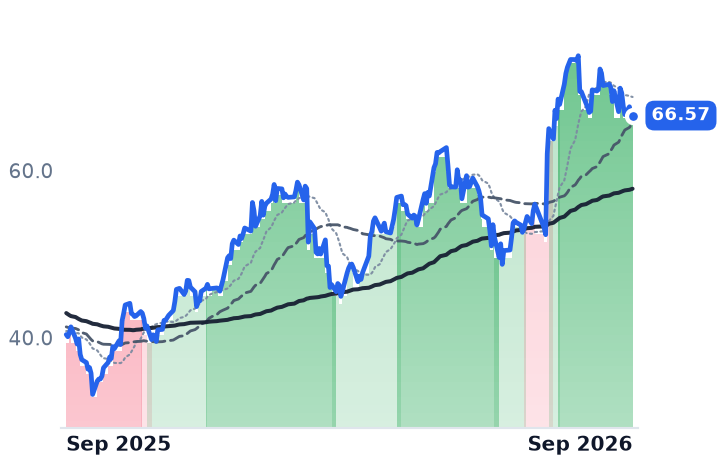
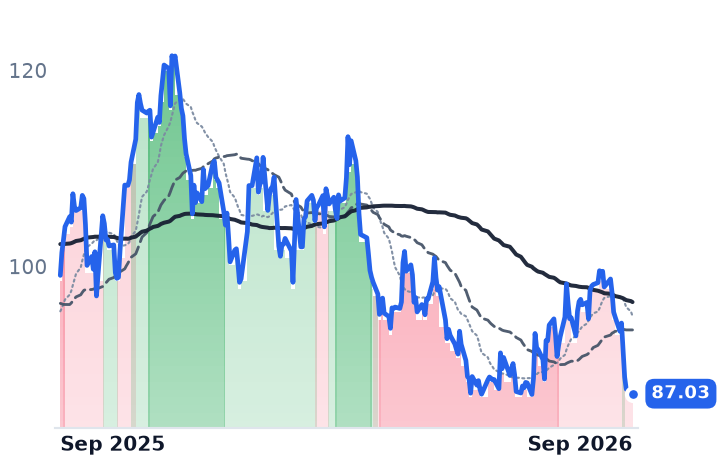
Four Permian-facing oilfield suppliers have risen together for a year, and the strongest of them since June is the one with no recurring volume at all. Cactus sells and rents wellhead and pressure-control equipment per rig and per well — and its growth came from a business it bought, not built: pressure-control revenue of $644.2m in the first half, up 74.1% year over year, almost entirely from the 65% interest it took in Baker Hughes' surface pressure control unit. Management guides that segment down 10% sequentially in the third quarter.
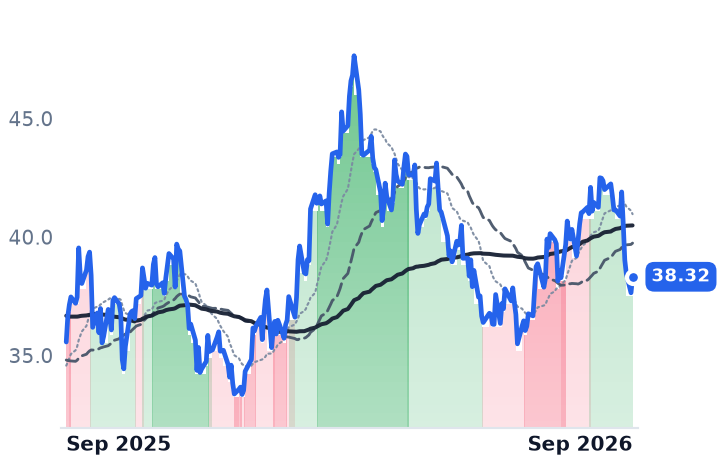
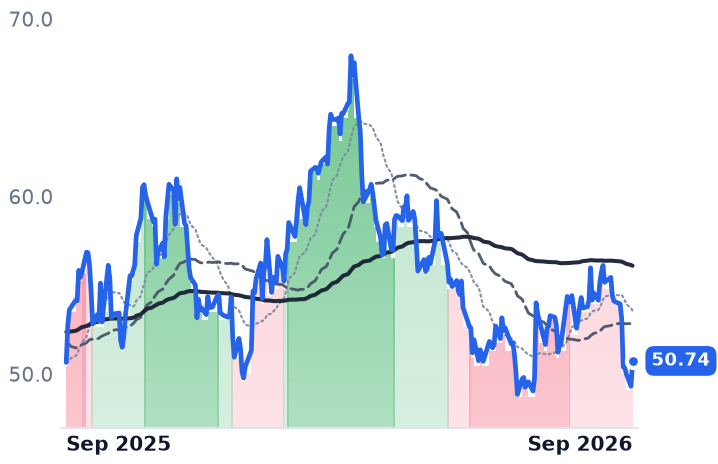
Cactus is nonetheless the cheapest of the group, at 22.3x forward earnings with a 7% trailing free-cash-flow yield. Select Water Solutions, the one genuinely compounding contracted water volumes, carries 30.6x forward for 11% consensus earnings growth and is spending ahead of the cash. Atlas Energy Solutions has lost money at the operating line four quarters running.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
WHD | Cactus | Wellhead & Pressure Control | 🟢 Cont. Bull | −2.2% | +64.9% |
WTTR | Select Water Solutions | Water Services & Energy Solutions | 🟢 Cont. Bull | +4.5% | +91.4% |
AESI | Atlas Energy Solutions | Proppant & Logistics | 🔴 Cont. Bear | −1.4% | +1.1% |
| Compared against · context, not the story | |||||
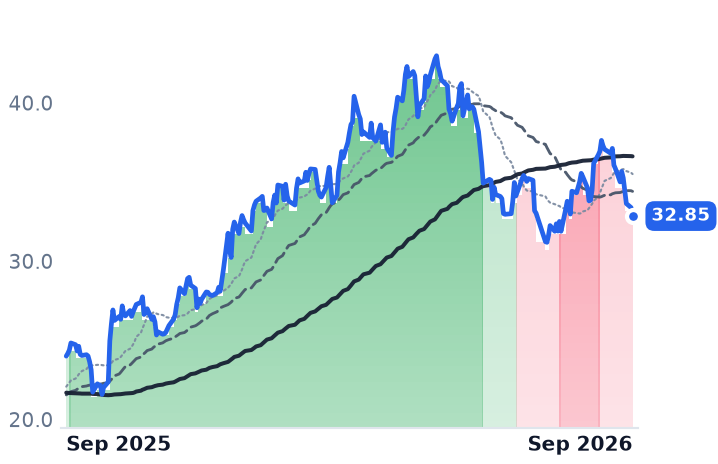
SND | Smart Sand | Oil & Gas Equipment & Services | 🟢 Cont. Bull | +9.0% | +149.5% |
EXE | Expand Energy | Appalachian Shale Gas | 🔴 Cont. Bear | −9.7% | −12.2% |
RRC | Range Resources | Appalachian Shale Gas | ⚠️ Emerging Bear | −7.1% | +7.7% |
EQT | EQT | Appalachian Shale Gas | 🔴 Cont. Bear | −5.7% | +0.2% |
HAL | Halliburton | Well Services & Stimulation | ⚠️ Emerging Bear | −5.1% | +36.9% |
SLB | Slb | Well Services & Stimulation | 🟢 Cont. Bull | −3.5% | +53.2% |
LBRT | Liberty Energy | Well Services & Stimulation | ⚠️ Emerging Bear | −2.4% | +49.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WHD | $4.6B | 56.0x | 22.3x | 3.4x | 2.7x | 4.8x | 3.8x | 11.8x | 7.0% |
WTTR | $2.2B | 74.1x | 30.6x | 1.5x | 1.4x | 8.1x | 7.5x | 10.4x | -3.7% |
AESI | $1.5B | n/m | — | 1.4x | 1.3x | 33.0x | 31.6x | 20.4x | -12.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SND | $222.7M | 19.2x | 52.3x | 0.6x | 1.0x | 4.4x | 7.6x | 8.1x | 15.6% |
EXE | $22.7B | 8.4x | 10.9x | 1.7x | 1.7x | 2.7x | 2.7x | 3.9x | 11.2% |
RRC | $9.8B | 11.5x | 10.3x | 3.0x | 2.8x | 6.2x | 5.8x | 7.6x | 12.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQT | $33.8B | 11.9x | 13.3x | 3.6x | 3.6x | 5.3x | 5.3x | 6.3x | 11.2% |
HAL | $28.1B | 17.6x | 14.4x | 1.3x | 1.3x | 8.3x | 8.3x | 8.3x | 6.1% |
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LBRT | $3.2B | 25.6x | 69.9x | 0.8x | 0.7x | 5.8x | 5.3x | 6.8x | -10.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
WHD | Revenue | +59.2% | +5.4% | +4.7% |
| EPS | +18.0% | +18.0% | +15.2% | |
WTTR | Revenue | +12.0% | +4.8% | +6.2% |
| EPS | +169.0% | +11.4% | +59.6% | |
AESI | Revenue | +2.5% | +14.8% | +18.8% |
| EPS | +109.2% | −80.1% | −299.1% | |
SND | Revenue | −25.4% | — | — |
| EPS | −47.9% | — | — | |
EXE | Revenue | +15.4% | −4.0% | +6.1% |
| EPS | +50.0% | −5.1% | +22.8% | |
RRC | Revenue | +17.7% | +2.5% | +8.1% |
| EPS | +40.2% | −4.7% | +21.6% | |
EQT | Revenue | +11.3% | −1.1% | +11.4% |
| EPS | +38.2% | −5.5% | +38.1% | |
HAL | Revenue | +2.0% | +5.4% | +4.3% |
| EPS | +3.1% | +23.2% | +16.1% | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
LBRT | Revenue | +19.1% | +8.5% | +14.5% |
| EPS | −534.7% | −46.7% | +353.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Cactus, which engineers, sells and rents wellhead equipment, frac stacks and production trees to drillers, earned most of this year's growth from a business it did not build. On 2 January 2025 it closed the purchase of a 65% majority interest in Baker Hughes' Surface Pressure Control operations, forming the Cactus International joint venture. Pressure Control revenue for the first six months of 2026 reached $644.2m, up $274.1m, or 74.1%, on the same period last year — a rise the company's quarterly filing attributes primarily to international contributions from that venture.
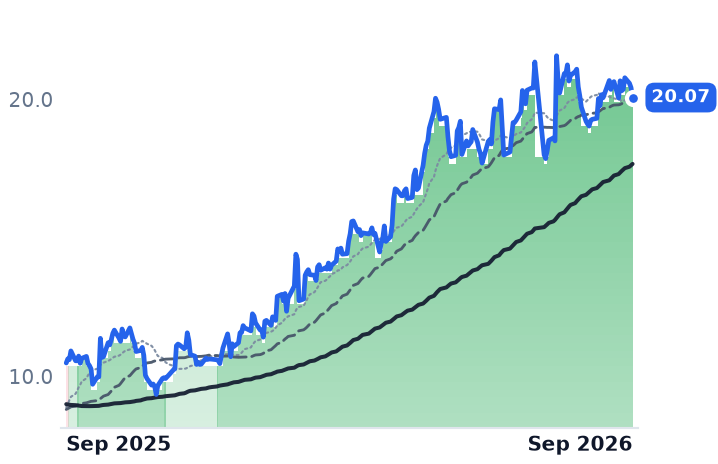
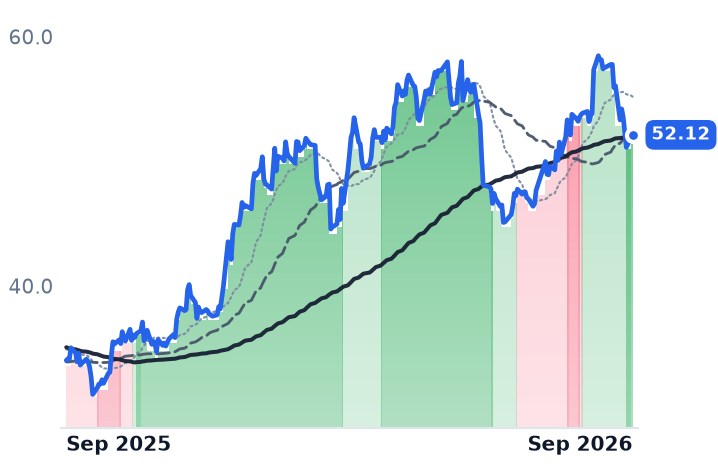
That matters beyond one filing because Cactus has been carried along — and lately ahead of — a group of Permian water, sand and wellhead suppliers whose year-long advance is usually explained by recurring, contracted fee income. Over the three months to 22 September, Cactus gained 25.5% against Select Water Solutions' 10.1%. The name with no volume tail after the frac crew leaves outran the name built to collect one, and the engine behind it is an order book management now guides lower.
One quarter did the work
Cactus' second-quarter revenue was $449.5m, up 64.3% year over year, with operating income up 37.5% — revenue growing far faster than profit, the signature of acquired growth. Pressure Control revenue rose 14.6% sequentially to $344m, primarily on Middle East deliveries executed faster than expected "despite continued conflict disruption and associated logistics challenges," according to the 29 July release. Chairman and chief executive Scott Bender said of the period: "The second quarter was a particularly strong period for our business. Order and shipment momentum continued in our Spoolable Technologies segment, and the acceleration of initial deliveries from previously discussed Latin America orders into the second quarter contributed to improved sales and margin mix relative to expectations."
The market took three sessions to respond, then moved fast: the shares closed at $52.32 on 29 July, $62.00 the next day and $73.27 by 17 August, and have held an uptrend since 6 August, with the 50-day average above the 200-day. Cactus reported adjusted earnings before interest, taxes, depreciation and amortization of $133m at a 29.5% margin, raised the quarterly dividend 7% to $0.15, and ended June with $365.8m of cash and no bank debt.
On the call, management guided third-quarter Pressure Control revenue down 10% versus the second quarter, while guiding Spoolable Technologies — spoolable pipe, roughly a quarter of group revenue and the one genuinely domestic read in the business — up a further 15-20%. Spoolable revenue rose 17.4% sequentially to $106m.
The water name is the one paying for its future
Select Water Solutions, which gathers, recycles and disposes of produced water for Permian producers, is the group's actual fee-based converter, and its June quarter was its best: Water Infrastructure revenue of $101.6m, up 25.6% year over year at a 58.3% gross margin before depreciation, with group operating income more than doubling. In August it amended a 12-year agreement covering more than 875,000 dedicated and right-of-first-refusal acres in the Northern Delaware Basin. It is also funding that conversion out of pocket, having raised 2026 net capital spending guidance to $250m-$290m against roughly $93m of quarterly EBITDA; trailing free cash flow is negative, a yield of -3.7%. Chief financial officer Chris George told investors the company is building "a tremendous portfolio of long-term contracted cash flows."
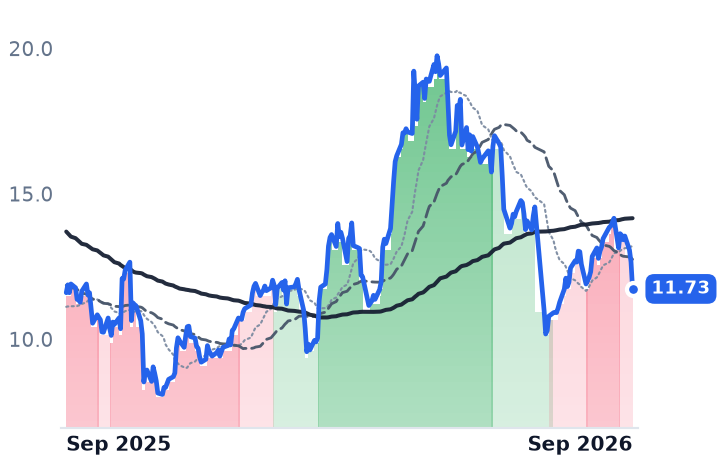
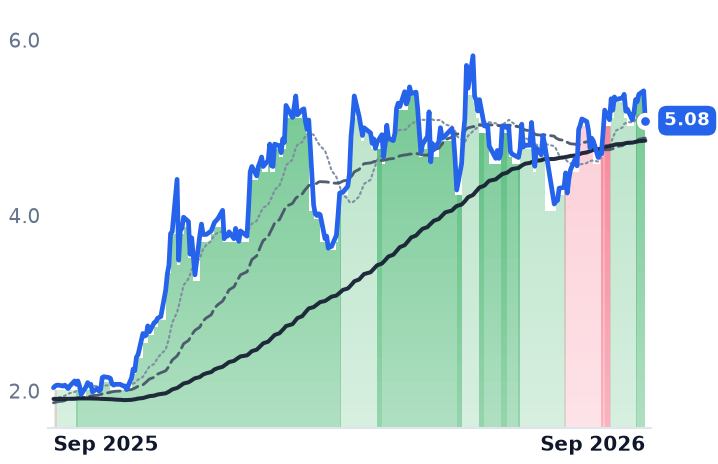
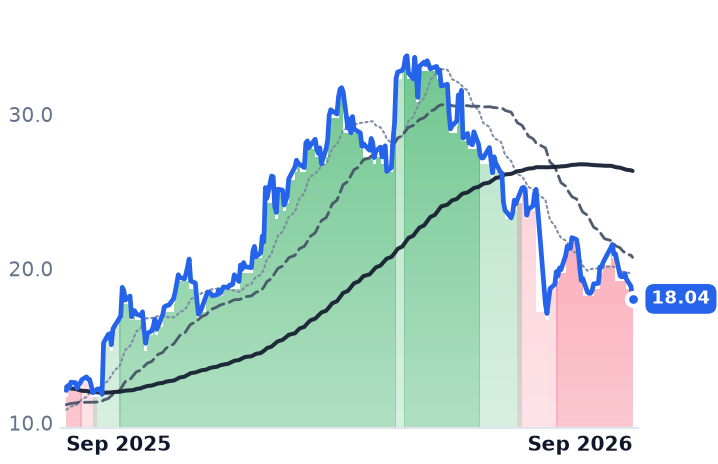
Atlas Energy Solutions, the Permian frac-sand miner and Dune Express conveyor operator, sits outside the advance entirely: gross margin of 5.9% against 18.1% a year earlier, proppant at about $17.70 a ton, a fourth consecutive quarterly operating loss, and $914.2m of long-term debt against $168.2m of cash while it keeps paying a $0.25 quarterly dividend. Its shares are down 22.9% over three months. Smart Sand, the Northern White sand microcap, reads the same completions cycle the other way — revenue up 34.1% with gross margin widening to 17.2%.
What the group actually shares
Not a water mechanism. Crude above $100 in September, a rig count of 595 (up 53 from a year ago) and frac spreads at 184 crews re-rated the entire service complex — Halliburton rose 45%, SLB 54% and Liberty 55% over twelve months, and the Dallas Fed's third-quarter survey recorded the prices-received-for-services index swinging from -30.0 to 9.3. Select's outperformance is real but sits inside that tide, and its premise — that produced-water fees grow whether or not wells are drilled — is currently untested, because wells are being drilled.
So the group splits three ways. Select earns its operating improvement and pays for the next leg before the cash arrives, at 30.6x forward earnings for 11% consensus growth. Atlas earns its de-rating. Cactus has the strongest reported quarter and the only positive free-cash-flow yield of the three, near 7%, at 22.3x forward against 56x trailing — and the least durable source of growth, since backlog conversion releases orders already won rather than winning new ones.
The October print is the test of exactly that. A guided 10% sequential decline is a company telling investors its best quarter was a delivery schedule; what shows up underneath it is the business.