

Chewy Grew Sales 7.3% and Gross Profit 3.4% — Overhead Cuts Made Its 41% Profit Jump
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Chewy's July quarter was its biggest ever and produced almost no incremental gross profit. Net sales reached $3.33bn while gross profit rose only 3.4%; operating income still jumped 41% to $98.4m, entirely out of selling and administrative expense, which fell to 18.4% of sales. Petco's mirror image: comparable sales up 0.6%, sales flat, and operating profit up to 3.2% of sales on expense discipline against fixed store costs.
Both businesses are improving. Neither is improving where the pet dollar is actually growing — veterinary care and prescriptions now exceed 40% of US pet spending, and pet-owning households have slipped to 67% from 69% in 2024. Consensus needs Chewy's earnings up 48.5% next year on revenue growth that never exceeds 7.3%. That is a margin forecast wearing a growth label.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CHWY | Chewy | Pet & General Specialty | 🔴 Cont. Bear | −19.7% | −47.6% |
WOOF | Petco Health and Wellness | Pet & General Specialty | 🔴 Cont. Bear | −16.7% | −31.6% |
CART | Maplebear | Pet & General Specialty | 🟢 Cont. Bull | −15.0% | +4.2% |
| Compared against · context, not the story | |||||
AMZN | Amazon.com | Online Marketplaces | 🟢 Cont. Bull | −1.4% | +13.5% |
WMT | Walmart | Warehouse Clubs | 🔴 Cont. Bear | +3.4% | +7.7% |
FRPT | Freshpet | Pet Food & Nutrition | 🟢 Cont. Bull | −21.7% | +17.5% |
ZTS | Zoetis | Animal Health | 🔴 Cont. Bear | −5.0% | −48.7% |
IDXX | IDEXX Laboratories | Specialty & Veterinary Diagnostics | 🔴 Cont. Bear | −6.5% | −18.8% |
TSCO | Tractor Supply | Sporting Goods & Outdoor | 🔴 Cont. Bear | −9.7% | −43.7% |
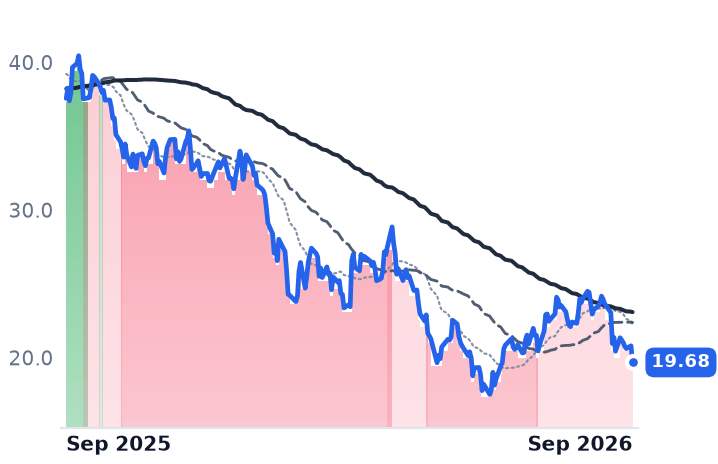
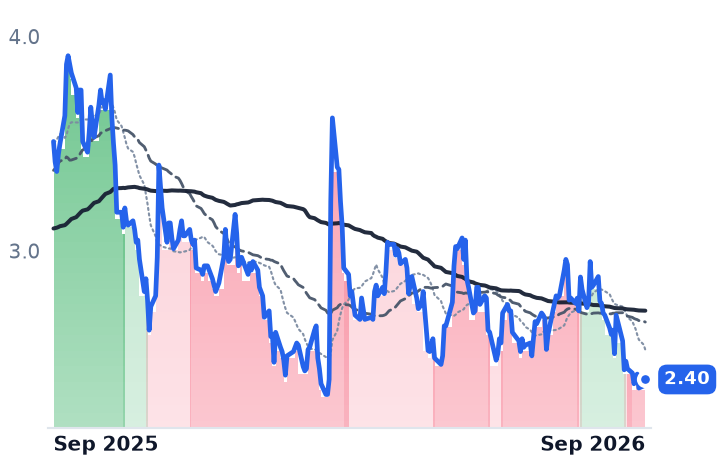
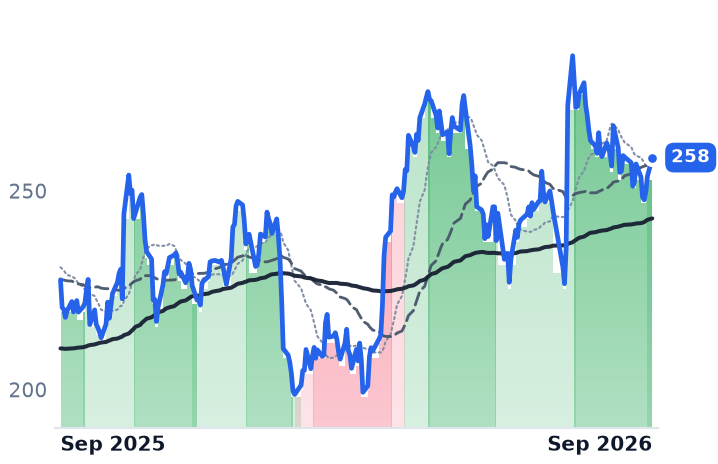
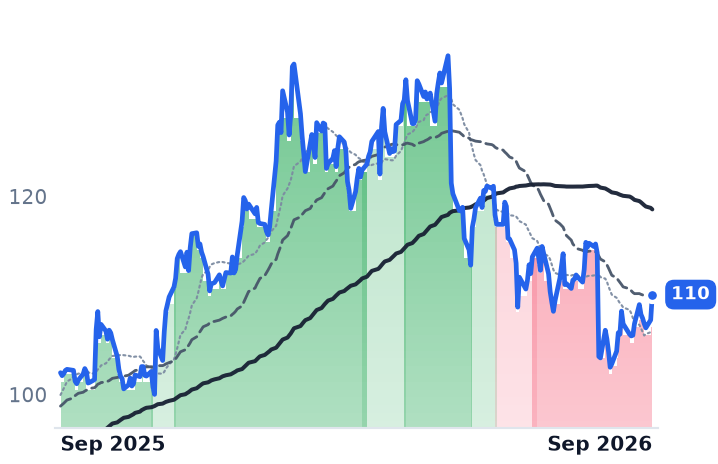
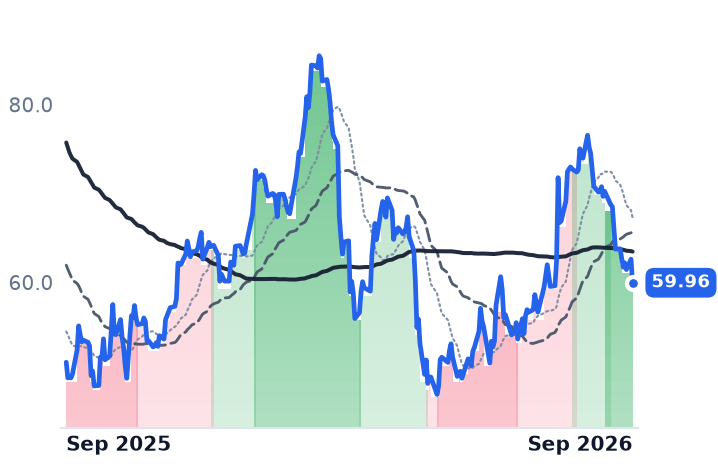
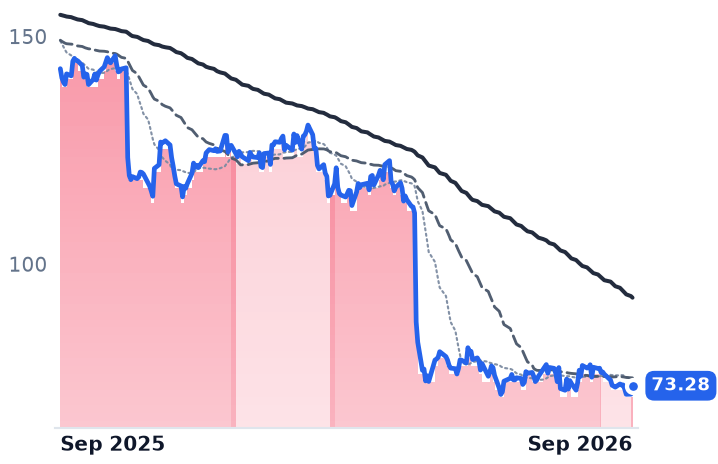
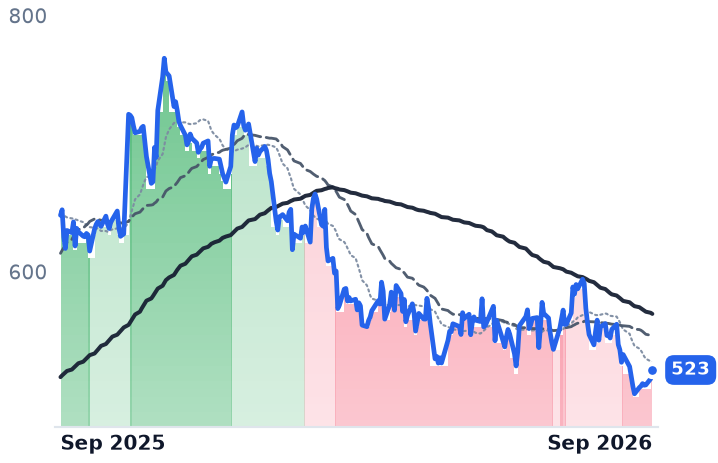
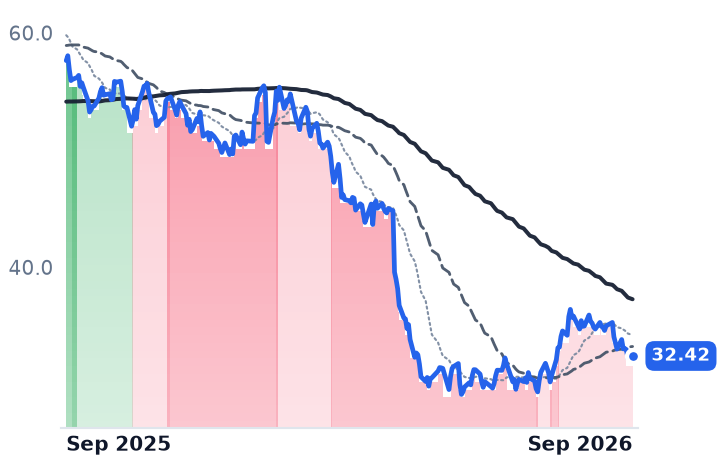
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CHWY | $8.1B | 37.8x | 25.2x | 0.6x | 0.6x | 2.1x | 2.0x | 21.8x | 7.0% |
WOOF | $682.5M | 21.6x | 9.7x | 0.1x | 0.1x | 0.3x | 0.3x | 5.5x | 45.2% |
AMZN | $2.9T | 21.2x | 21.1x | 3.7x | 3.5x | 7.3x | 6.8x | 11.9x | -0.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WMT | $1.0T | 47.9x | 45.1x | 1.5x | 1.4x | 5.9x | 5.6x | 23.8x | 1.4% |
FRPT | $3.2B | 15.7x | 33.7x | 2.7x | 2.6x | 6.9x | 6.7x | 13.3x | 5.3% |
ZTS | $31.1B | 11.9x | 10.7x | 3.3x | 3.2x | 4.6x | 4.5x | 7.3x | 6.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IDXX | $41.7B | 38.7x | 36.1x | 9.4x | 8.9x | 15.1x | 14.3x | 28.0x | 2.0% |
TSCO | $16.0B | 14.9x | 14.3x | 1.0x | 1.0x | 3.2x | 3.0x | 11.4x | 3.6% |
CART | $10.4B | 23.4x | 19.0x | 2.6x | 2.5x | 3.6x | 3.4x | 13.1x | 11.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CHWY | Revenue | +6.7% | +7.3% | +6.8% |
| EPS | −32.6% | +48.5% | +36.3% | |
WOOF | Revenue | −2.7% | +0.6% | +1.1% |
| EPS | −275.3% | +68.5% | +3.2% | |
AMZN | Revenue | +15.9% | +14.6% | +16.0% |
| EPS | +76.8% | −16.1% | +30.8% | |
WMT | Revenue | +4.7% | +5.1% | +4.8% |
| EPS | +6.0% | +10.5% | +12.7% | |
FRPT | Revenue | +11.1% | +8.5% | +8.0% |
| EPS | −20.4% | −3.9% | +11.3% | |
ZTS | Revenue | +3.8% | +4.4% | +5.1% |
| EPS | +9.5% | +7.6% | +8.4% | |
IDXX | Revenue | +9.9% | +8.8% | +9.1% |
| EPS | +13.4% | +12.9% | +13.2% | |
TSCO | Revenue | +3.8% | +5.5% | +6.9% |
| EPS | +1.8% | +8.3% | +11.2% | |
CART | Revenue | +14.3% | +10.7% | +10.4% |
| EPS | +28.8% | +27.2% | +17.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Chewy shipped more pet food in its July quarter than in any quarter of its history, and the extra volume brought almost no extra gross profit with it. Net sales of $3.33bn were up 7.3% year over year, an acceleration from 4.8% the quarter before. Gross profit grew 3.4%.
That gap is the story of both American pet retailers this season, and it matters because of where each is now spending. Chewy borrowed for the first time — a $600m term loan — to buy veterinary clinics; Petco, which runs roughly 1,500 stores with about 300 wholly owned veterinary hospitals inside them, resumes hospital expansion in 2027. Both are chasing the part of the pet wallet that is growing, because the part they were built on is not.
Where the profit came from
Chewy's operating income rose 41% to $98.4m. Every dollar of that gain came from below the gross line: selling, general and administrative expense fell 70 basis points to 18.4% of sales on warehouse automation and fulfilment utilization, and roughly $15m of the quarter's adjusted-EBITDA outperformance was timing — tariff refunds, vendor rebates, discrete items. "We are north of 50% of our volume flowing through automated states, and we will continue to grow that over time," chief financial officer Christopher Deppe told investors on the September 9 call, adding that confidence in a long-term path to 10%-plus EBITDA margin "is stronger at this point."
Management describes gross margin as flat year over year at 30.4%. On the cost allocation in Chewy's filed income statement the ratio fell about 110 basis points, to 29.3%. The two definitions differ; the direction of travel does not, and the company has guided third-quarter gross margin down sequentially with a mid-single-digit fuel headwind.
The customer base grew the same modest way. Active customers reached 21.7m and net sales per active customer $602, each up 3.8%, with 43,000 of the new actives arriving through the acquired SmartPak business. Autoship subscriptions hit a record 84.6% of net sales. "Chewy continues to outperform the broader pet category by roughly 2x to 3x," chief executive Sumit Singh said on the same call — a claim about relative share in a category management itself called broadly flat.
Petco tells the same arithmetic from the store side. Second-quarter net sales of $1.5bn were flat with comparable sales up 0.6%, a second straight positive quarter off two years of decline. Operating income rose 11% to $47.8m because SG&A grew by $1m. "Q2 marks our seventh consecutive quarter of delivering on our profitability and cash flow goals, allowing us to significantly bring down our overall leverage," chief financial officer Sabrina Simmons said on September 2. The company has retired $170m of debt in nine months against $1.48bn of gross borrowings.
The dollar that is moving
Morgan Stanley Research puts veterinary care, prescriptions and diagnostics at more than 40% of US pet spending and rising, with its April survey finding 67% of households owning a pet, down from 69% in 2024 and affordability now the top reason cited for not owning one. Meanwhile the consumables dollar is contested at the top of the funnel: 79.6% of surveyed consumers shopped pet products on Amazon against 53.1% at Chewy.
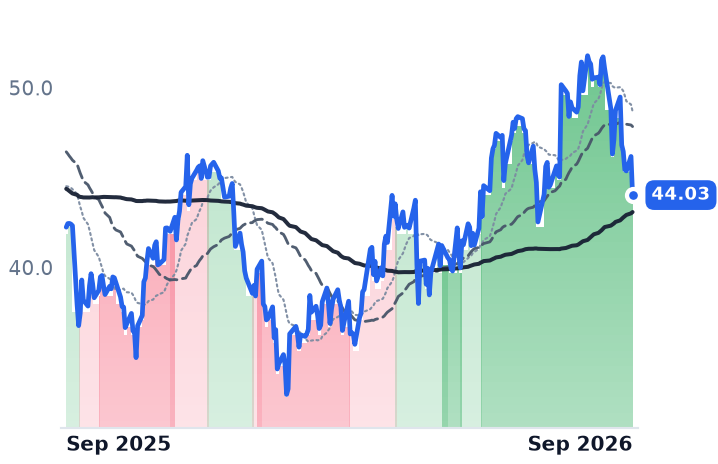
The shares have registered this as a category verdict. Over twelve months Chewy is down 47.6% and Petco 31.6%, alongside Zoetis, Tractor Supply and IDEXX — while Amazon and Walmart rose. JPMorgan's Doug Anmuth cut Chewy to Neutral on September 11, taking his target to $24, the second downgrade in two days; the average sell-side target is still $31.09. The Federal Reserve's September 16 rate increase lands on two newly levered balance sheets.
The verdict
Chewy at 25.2x forward earnings against 37.8x trailing is not being priced for the quarter it reported; it is being priced for the one consensus requires, with earnings up 48.5% next year on revenue growth that never exceeds 7.3% through 2031. That is margin, and the gross line has stopped supplying it — automation and advertising must. Petco at 9.7x forward against 21.6x trailing, 5.5x trailing enterprise value to EBITDA and 0.57x book, is an equity stub priced as an option on deleveraging, and $170m a year of paydown is the meter that matters.
Both managements are right that their businesses improved. Cost programs, though, have an end; the gross line does not. Chewy's veterinary clinics and fresh food grew at triple-digit rates last quarter off bases small enough that management does not size them separately — and that is the whole bet, on both sides of the segment.