

Patent Royalties, Not Module Sales, Took Vicor's Quarterly Growth Guidance Past 20%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
The two strongest reported businesses in AI power management have de-rated this quarter, while the one whose shipped business went backwards re-rated on a legal calendar.
Vicor lifted third-quarter guidance on September 21 entirely on royalties from a Vertical Power Delivery patent licence granted five days earlier — its fourth OEM or hyperscaler licensee — and the shares have gained 45.2% across four sessions. Its June quarter shows the other half: revenue up 1.6%, gross margin down from 65.3% to 58.0%, operating income down 23.2%, net income up 20.8%.
Monolithic Power grew enterprise-data revenue 164% to $380.6m and Analog Devices expanded gross margin to 67.3% with communications revenue up 84% — and both fell over the past three months. Vicor is paid for permission; the other two are paid per socket.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
VICR | Vicor | Other | ⚠️ Emerging Bear | +40.5% | +387.9% |
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | +7.4% | +50.4% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +5.2% | +58.9% |
| Compared against · context, not the story | |||||
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +4.6% | +53.9% |
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +10.0% | +24.9% |
GFS | GLOBALFOUNDRIES | Logic Foundries | ⚠️ Emerging Bear | +5.1% | +45.6% |
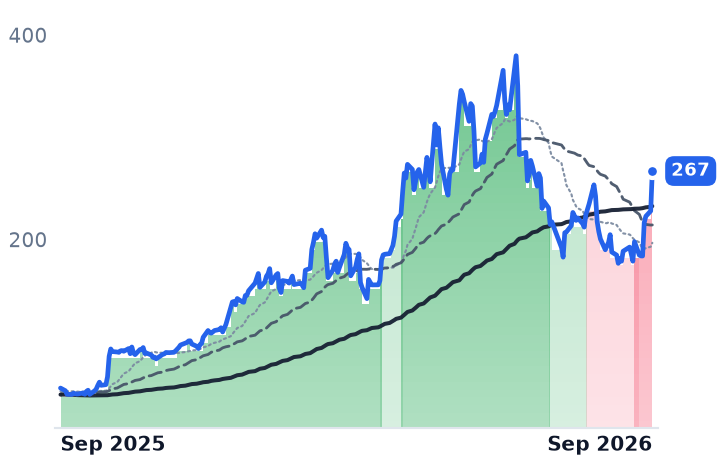
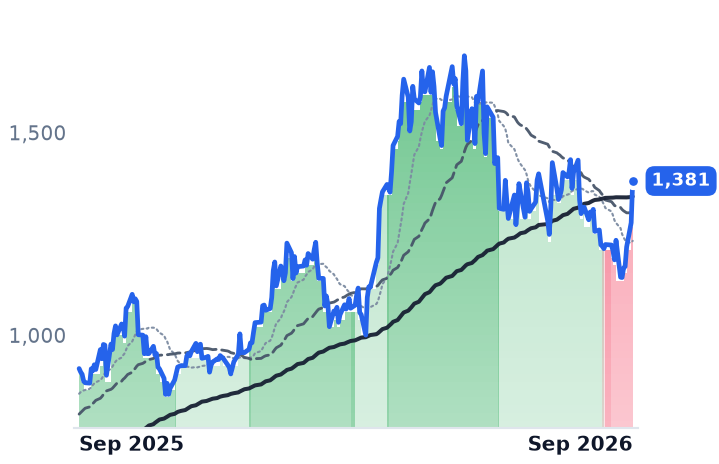
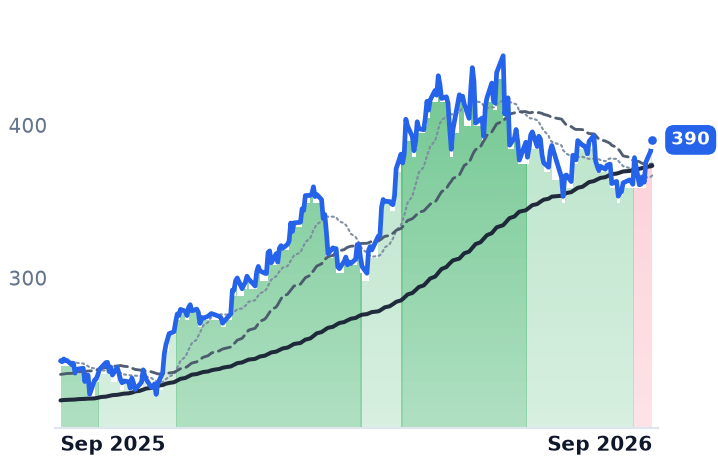
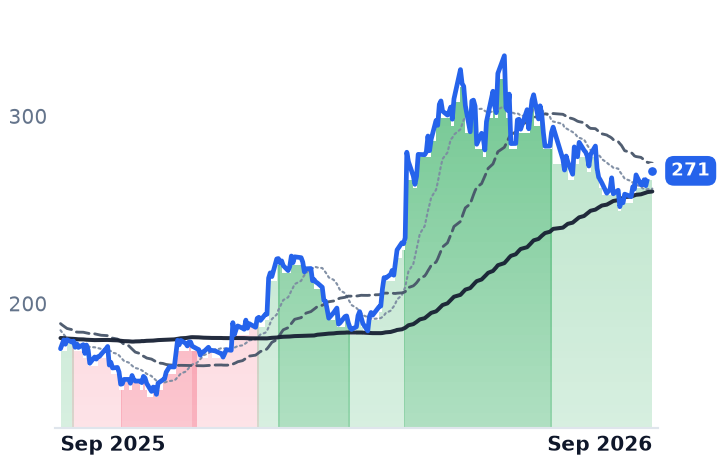
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $12.2B | 84.1x | 78.1x | 25.7x | 20.2x | 45.3x | 35.6x | 91.8x | 0.4% |
MPWR | $67.8B | 84.2x | 50.3x | 20.7x | 16.3x | 37.5x | 29.6x | 66.1x | 0.9% |
ADI | $190.1B | 46.1x | 30.3x | 13.7x | 12.6x | 20.8x | 19.1x | 30.2x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TXN | $243.5B | 40.3x | 31.3x | 12.5x | 11.1x | 21.5x | 19.0x | 27.9x | 2.2% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
GFS | $26.4B | 37.2x | 24.8x | 3.8x | 3.6x | 13.9x | 13.2x | 12.7x | 3.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VICR | Revenue | +33.1% | +55.6% | +22.2% |
| EPS | +58.9% | +73.2% | +33.0% | |
MPWR | Revenue | +49.2% | +28.7% | +20.2% |
| EPS | +54.8% | +31.0% | +20.2% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.1% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
GFS | Revenue | +8.0% | +12.3% | +14.0% |
| EPS | +17.7% | +30.5% | +33.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vicor told investors on September 21 that third-quarter revenue would grow more than 20% sequentially instead of the nearly 10% it had previously guided, and said the whole increase came from royalties on a patent licence signed five days earlier. The Andover, Massachusetts maker of modular power converters — brick-format DC-DC parts sold to OEMs and contract manufacturers — granted the non-exclusive licence on September 16 to an artificial-intelligence systems maker that retains the right to buy the covered modules from somebody else entirely.
That is the pivot worth understanding, because three companies are now competing to deliver thousands of amps at under a volt into an AI accelerator, and they are being paid in three different currencies: a royalty set by a court schedule, dollar content per board built, and a broad analog catalog that has quietly become a data-center business. Only one of those currencies is priced off units shipped.
The licence is the product
Vicor's own release names the mechanism without euphemism: "Unlicensed hyperscalers first reached out after their computing systems were banned from importation because of infringing NBMs," it said on September 21, referring to the February 2025 exclusion order in which the International Trade Commission upheld two Vicor patents and barred importation of unlicensed computing systems containing infringing power modules, with Delta Electronics, Foxconn and Quanta among the respondents. "Since the first patent to VPD was only recently asserted, it is still possible to secure a license at an early stage of escalation with a low royalty rate," chief executive Patrizio Vinciarelli said in the same release.
The shipped business is going the other way. June-quarter revenue of $143.4m grew 1.6% year on year; gross margin fell from 65.3% to 58.0%; operating income dropped 23.2% to $34.9m. Net income still rose 20.8% to $49.8m — roughly $15m of it earned below the operating line. An earlier licence had already lifted second-quarter guidance from $126m to $142m. Two licences in four months, each one re-setting a quarter's revenue line, and a gross profit line that fell 9.8% while they did it.
Paid by the board
Monolithic Power, the Kirkland, Washington designer of power-management chips built into accelerator reference designs, is the other meter and it is working. June-quarter revenue grew 47.6% to $980.6m, a fourth straight quarter of acceleration; enterprise-data revenue rose 164.3% to $380.6m and reached 38.8% of the total, up from 32.7% three months earlier, according to the company's results. Operating income grew 84.4% on gross margin held flat at 55.2%. Its recent catalyst was capacity, not litigation: a long-term agreement announced September 9 puts its process into GlobalFoundries' 300mm Singapore fab, with volume production expected in early 2027. The concentration risk is real — a research note questioning its allocation on Nvidia's next platform took 7.4% off the shares on September 14 — but the stock closed September 22 some 20.8% above that day.
Analog Devices was supposed to be the control here: a broad-catalog industrial and automotive house that should not track the accelerator socket at all. It does. Revenue grew 39.6% to $4.02bn, gross margin expanded to 67.3% from 63.1% three quarters earlier, and communications revenue grew 84% with data center now four-fifths of that segment. "Power availability has become the primary constraint to further AI progress," chief executive Vincent Roche told investors on August 19. On July 7 it closed a $1.5bn purchase of Empower Semiconductor, aimed squarely at the in-package conversion socket Monolithic Power occupies and Vicor patents. Management guided fourth-quarter gross margin about 1.5 percentage points higher on rising utilization — the opposite of a destocking cycle.
What the prices did with all this
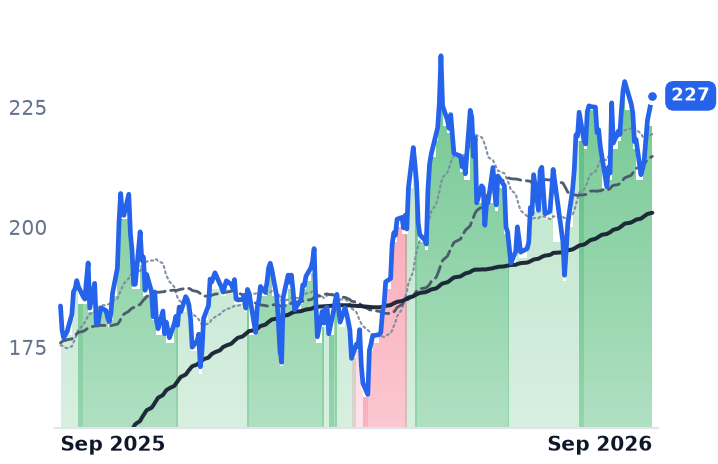
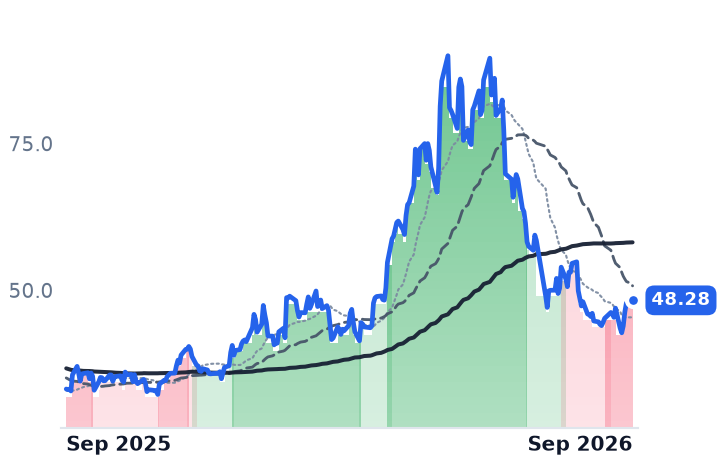
Over three months Vicor fell 27.0%, Analog Devices 12.4% and Monolithic Power 10.2%, with Texas Instruments down 18.5% alongside them; the Federal Reserve's 25 basis-point increase on September 16 raises the discount applied to late-decade earnings but does not explain a single one of last week's moves. The two names whose reported meters are strongest de-rated; the one whose gross profit shrank rose 17.1% on Tuesday and 45.2% across four sessions.
Analog Devices is the cheapest of the three at 19.1 times forward gross profit against 20.8 times trailing — the multiple that matters here because margins differ too widely for sales comparisons to mean anything — with a 2.6% trailing free-cash-flow yield. Monolithic Power sits at 29.6 times forward against 37.5 times trailing while its gross profit grew 47.8%. Vicor is the most expensive at 35.6 times forward, and its 78.1 times forward earnings sits barely below 84.1 times trailing, a gap of 7% against 34% at Analog Devices and 40% at Monolithic Power — consensus embedding almost no earnings growth this fiscal year, and now plainly stale.
The honest split: Monolithic Power and Analog Devices have earned nothing that looks like a de-rating, and the burden falls on whoever thinks accelerating revenue and widening operating margins should be capitalized at less. Vicor's shipped business earned its fall; its recovery was granted by an exclusion order. Royalties are cash, and a licensee that can source modules elsewhere still pays. But an income stream set by how many hyperscalers face an import ban has no run rate, and the company itself says the low rate is available early in escalation.
The fourth licence was signed six days ago. The fifth has no date on it, and the modules keep shipping either way.