

Nutex Health Cut $52.3m of Arbitration Costs and Turned a Loss Into $65.8m of Profit
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A freestanding-emergency-room operator posted its best profit in years on revenue that shrank, and the money came from a federal docket rather than a patient. Nutex Health's June-quarter revenue fell 13.6% to $210.75m while gross margin went from 51.2% to 67.0% — the swing traced to a vendor contract reset to pay-on-collected and Washington cutting the per-party dispute fee from $115 to $15.
The cash is arriving; the durability is what consensus doubts, modelling earnings per share flat in 2027 and down 9.1% in 2028. Privia Health, filed under the same industry heading, earns from Medicare shared savings and fell on a beat-and-raise; BrightSpring earns on pharmacy scripts. One label, three unrelated engines, and only Nutex's depends on a rulemaking.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
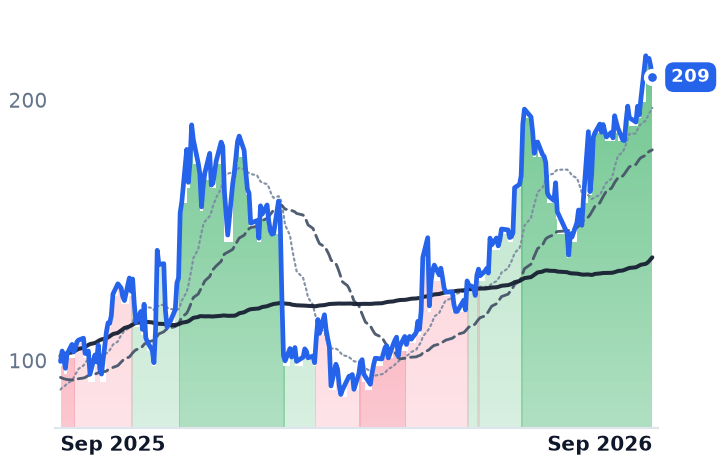
NUTX | Nutex Health | Provider Networks & Management | 🟢 Cont. Bull | +11.3% | +109.4% |
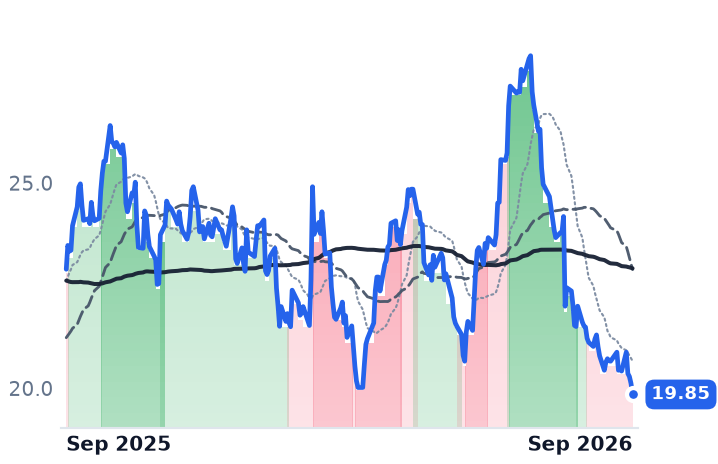
PRVA | Privia Health | Provider Networks & Management | ⚠️ Emerging Bear | −5.6% | −13.3% |
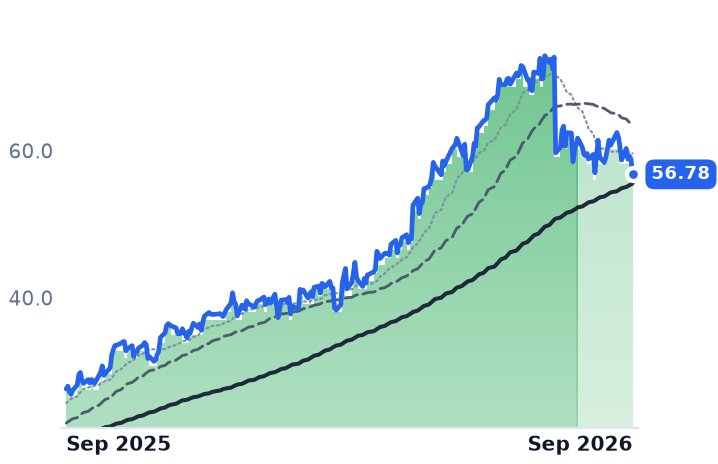
BTSG | BrightSpring Health Services | Provider Networks & Management | 🟢 Cont. Bull | −4.6% | +105.7% |
| Compared against · context, not the story | |||||
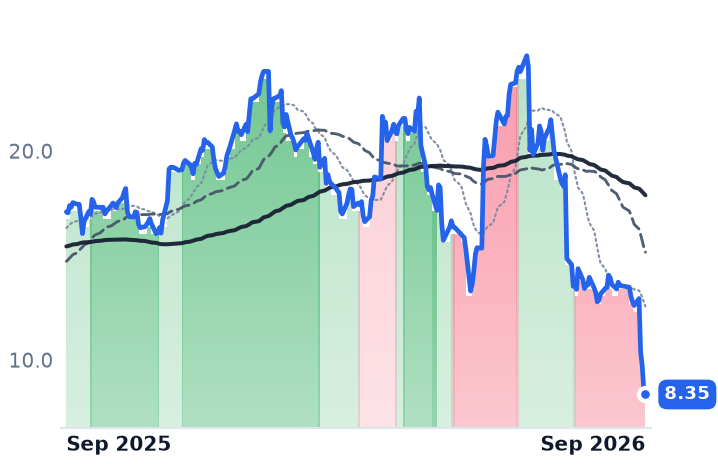
ALHC | Alignment Healthcare | Medicare Advantage Specialists | ⚠️ Emerging Bear | −37.8% | −51.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NUTX | $1.4B | 8.0x | 7.5x | 1.7x | 1.6x | 3.3x | 3.2x | 4.1x | 19.1% |
PRVA | $2.5B | 88.3x | 77.1x | 1.1x | 1.0x | 13.9x | 13.4x | n/m | -1.9% |
BTSG | $11.1B | 39.7x | 31.2x | 0.8x | 0.7x | 6.3x | 5.9x | 20.3x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALHC | $2.7B | 65.3x | 72.1x | 0.6x | 0.5x | 4.7x | 4.1x | 27.0x | 7.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NUTX | Revenue | −11.2% | +10.6% | +5.2% |
| EPS | +97.5% | +0.3% | −9.1% | |
PRVA | Revenue | +17.0% | +9.2% | +11.8% |
| EPS | +95.6% | +62.0% | +37.0% | |
BTSG | Revenue | +20.5% | +13.6% | +14.2% |
| EPS | +73.1% | +26.9% | +21.8% | |
ALHC | Revenue | +32.3% | +24.7% | +24.1% |
| EPS | −276.9% | +139.1% | +73.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Nutex Health, which runs 21 micro-hospitals and freestanding emergency rooms across eight states, collected less revenue in its June quarter than a year earlier and still turned its best profit in years. Revenue fell 13.6% to $210.75m. Net income was $65.8m, against a $17.7m loss in the same quarter of 2025. Same-hospital visits rose 6.3%, so almost none of that came from the waiting room.
It came from one line in the cost stack. Total arbitration costs fell $52.3m, booked as a reduction to contract services expense, and gross margin went from 51.2% to 67.0%. Nutex stays out of network almost everywhere on purpose, bills the insurer, and when the offer is low it files the claim into the federal independent dispute resolution process created by the No Surprises Act. That process is now enormous: arbitrators awarded providers nearly $15bn in 2025, more than triple the prior year, and the programme costs roughly $3bn a year to run. Nutex's earnings line is, in a real sense, set by rulemaking.
How the dollar is actually earned
Nutex submits 50% to 60% of its claims into arbitration, prevails in more than 85% of determinations and collects over 80% of what it is awarded. Management has said normalised revenue per visit has run near $4,200 since the process opened in July 2024 and should stay around there — an award rate, never a posted price. The friction shows on the balance sheet: receivables stood at $351.7m at 30 June, up from $319.4m at year-end and equal to roughly 152 days of billings.
Two things cut the cost of running that machine at once. Vendor HaloMD's fees were amended to a pay-on-collected basis, retroactive and extended to 2029, effective 30 June. And a federal final rule dated 28 May 2026 cut the per-party administrative fee from $115 to $15 and allowed up to 50 line items to be batched into a single dispute. "We will not have to record 100% of the IDR costs on every potential legal determination win, as we will now be only accruing costs using a similar collection percentage that we use for our accrual of revenue," chief financial officer Jon Bates told investors. Chief executive Dr Tom Vo was blunter about the strategy: "We can stay out-of-network and still do well... the IDR process is a tool for us to get that fair and reasonable rate." The accruals are converting: operating cash flow of $109.7m in the first half, up 40%, against $31.1m of net long-term debt.
Whose dollar it is not
The tempting story is that provider gains are payer losses in one book. They are not. No Surprises Act protections, and therefore arbitration, do not apply to Medicare Advantage or Medicaid; they cover employer, marketplace and individual plans. Alignment Healthcare, a Medicare Advantage insurer whose shares fell 35.5% in five sessions to 18 September, was hit by hospital and skilled-nursing cost trend flagged at the Baird healthcare conference plus whistleblower accounting allegations. Different money. Insurers and benefit consultants say the arbitration bill is being passed into next year's premiums instead.
Privia Health, filed under the same industry heading, earns from a third pocket: a management fee on the collections of independent practices it does not own, plus lagging annual settlements from the Medicare Shared Savings Program. Its second quarter was strong — practice collections of $970.0m and care margin of $132.1m, implemented providers up 10.1% to 5,644, and guidance raised across every metric to full-year adjusted earnings before interest, tax, depreciation and amortisation of $145–155m, about 16.7x its $2.50bn market value. The shares fell 9.0% on the print and 9.8% more since, on the timing of shared-savings cash: management expects only 70% to 80% of the year's adjusted EBITDA to convert to free cash flow, and that assumes the 2025 settlements land by year-end. Over twelve months Privia is down 12.2% while Nutex is up 124.6%. BrightSpring Health Services, the third name under the label, grew revenue 23.0% on specialty pharmacy scripts at administered rates and trades near 31x forward earnings — an engine sharing no mechanism with either.
What the market is paying for
Nutex is cheap and the cheapness is the argument rather than an oversight: 7.5x forward earnings and 4.1x trailing enterprise value to earnings before interest, tax, depreciation and amortisation, against a consensus carried by three analysts that has earnings per share flat in 2027 and down 9.1% in 2028. The step-change is earned, banked and turning into cash. What it is not is compounding: visit growth is single-digit and capped by construction at three to five hospitals a year, and the cost relief came from a fee schedule and a vendor signature that can each happen only once.
A coalition of 67 health care and advocacy groups asked Congress this month to reopen the No Surprises Act. Nutex's margin has an address in Washington, and now everyone knows it.