

Coupang Won Back Its Members After the Breach but Guided Margin Recovery Out to Mid-2027
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Coupang's shoppers returned; its margins did not. The Korean retailer's second quarter carried a $556m operating loss on revenue that grew 3.9% — and about $410m of that loss is a single record privacy fine, with roughly six percentage points of the growth slowdown attributable to a weak won rather than lost volume.
The cause is dated and has nothing to do with lending: a November 2025 breach of 33.7m customer records, $1.17bn of compensation vouchers paid from January, and stranded delivery capacity built for volumes that did not arrive. Founder Bom Kim has guided Product Commerce margins back to pre-incident levels by the middle of 2027.
That is an earned de-rating. Harder to explain is the last month, when MercadoLibre and Sea — both accelerating, both with clean credit books — fell alongside it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
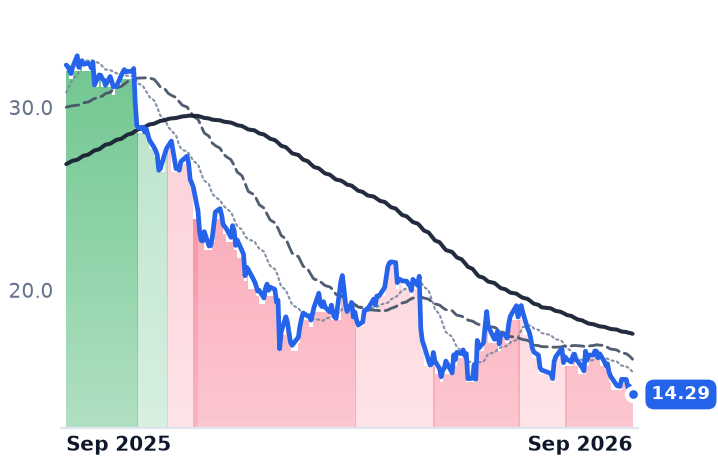
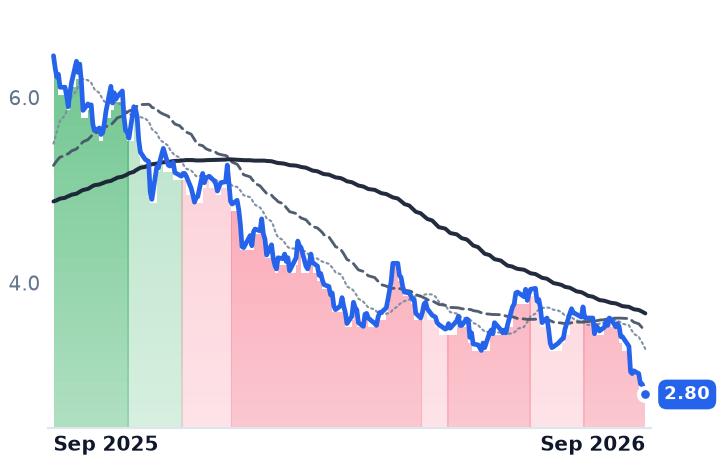
CPNG | Coupang | Regional/Niche E-commerce | 🔴 Cont. Bear | −13.1% | −55.8% |
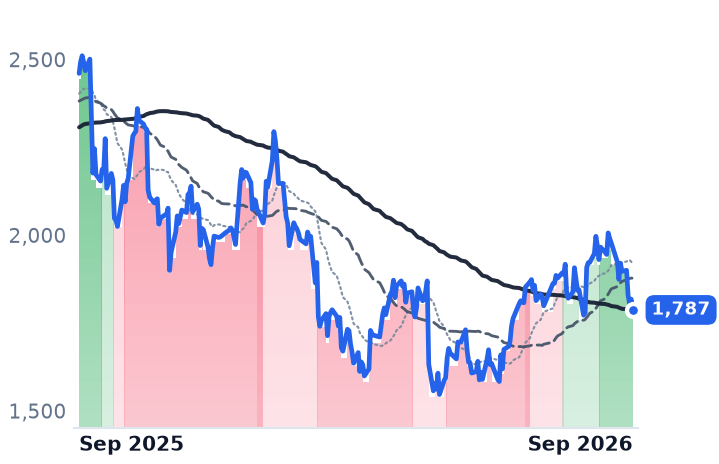
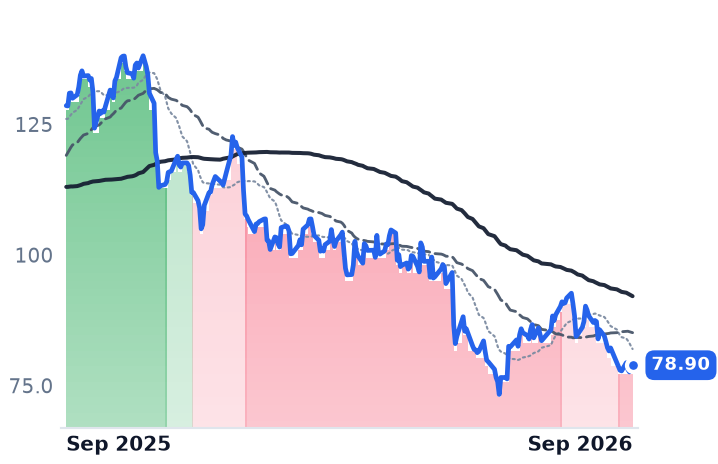
MELI | MercadoLibre | Online Marketplaces | 🌱 Emerging Bull | −8.2% | −27.4% |
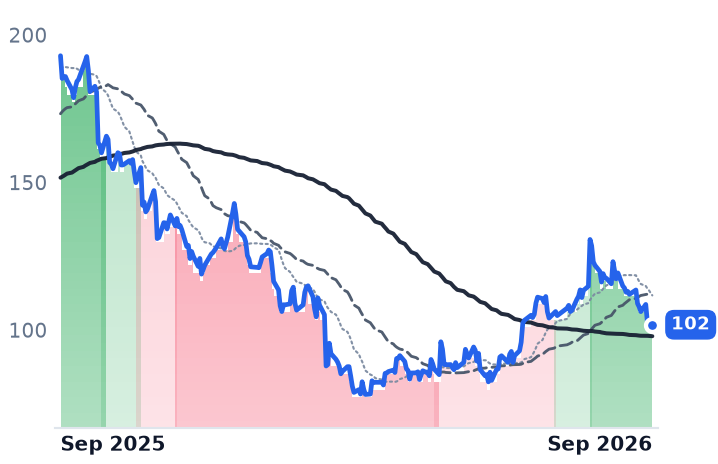
SE | Sea | Online Marketplaces | 🌱 Emerging Bull | −12.0% | −47.2% |
| Compared against · context, not the story | |||||
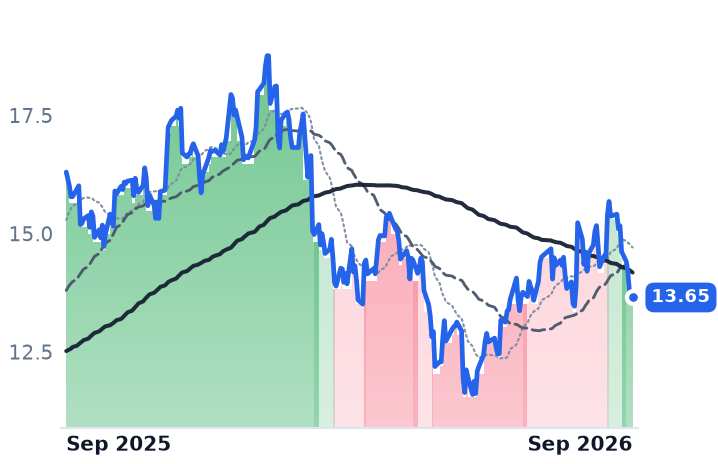
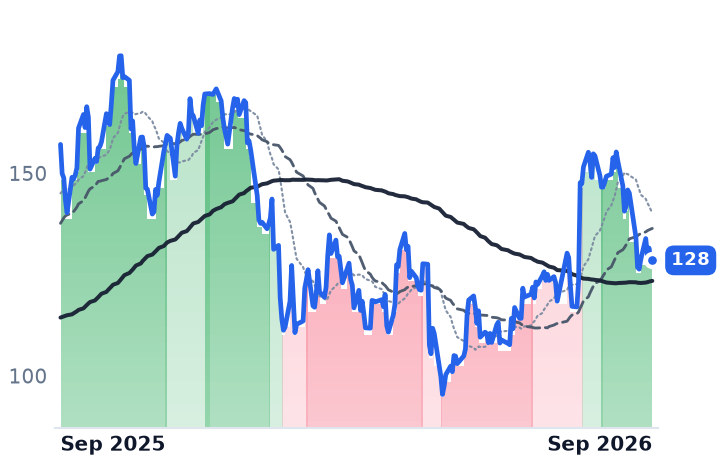
NU | Nu | Emerging Markets & Specialized Banking | 🟢 Cont. Bull | −7.5% | −16.3% |
GRAB | Grab | Marketplace & Commerce Platforms | 🔴 Cont. Bear | −20.6% | −56.7% |
PDD | PDD | Online Marketplaces | 🔴 Cont. Bear | −9.4% | −38.6% |
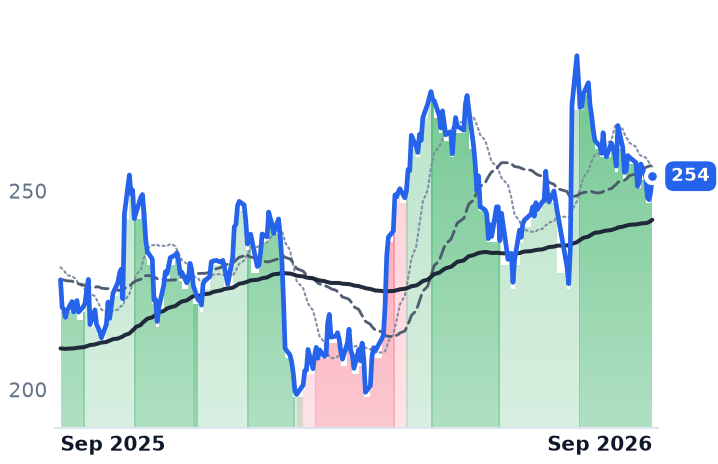
SHOP | Shopify | Marketplace & Commerce Platforms | 🟢 Cont. Bull | −14.2% | −18.2% |
AMZN | Amazon.com | Online Marketplaces | 🟢 Cont. Bull | −3.2% | +11.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CPNG | $25.7B | n/m | — | 0.7x | 0.7x | 2.6x | 2.4x | 787.8x | 0.4% |
MELI | $90.6B | 48.6x | 47.1x | 2.6x | 2.2x | 6.0x | 5.1x | 32.3x | 13.8% |
SE | $61.1B | 37.6x | 27.7x | 2.2x | 1.9x | 5.0x | 4.4x | 21.6x | 5.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NU | $58.9B | 18.6x | 14.0x | 3.4x | 2.7x | 7.7x | 6.2x | 21.4x | 6.4% |
GRAB | $14.1B | 38.3x | 33.1x | 4.0x | 3.4x | 9.1x | 7.9x | 27.2x | -0.6% |
PDD | $136.4B | 9.2x | — | 2.2x | — | 3.8x | — | 7.2x | 11.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SHOP | $130.1B | 98.1x | 54.7x | 10.5x | 8.8x | 21.9x | 18.4x | 80.5x | 1.6% |
AMZN | $2.9T | 21.2x | 21.1x | 3.7x | 3.5x | 7.3x | 6.8x | 11.9x | -0.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CPNG | Revenue | +6.3% | +13.9% | +12.3% |
| EPS | −410.1% | −162.9% | +123.7% | |
MELI | Revenue | +45.2% | +28.3% | +24.9% |
| EPS | −6.2% | +44.1% | +41.7% | |
SE | Revenue | +40.1% | +22.8% | +15.1% |
| EPS | +15.4% | +29.3% | +24.9% | |
NU | Revenue | +54.4% | +21.7% | +14.0% |
| EPS | +42.6% | +32.7% | +26.4% | |
GRAB | Revenue | +20.8% | +20.7% | +17.8% |
| EPS | +97.8% | +48.8% | +36.2% | |
PDD | Revenue | +15.9% | +13.2% | +10.1% |
| EPS | +10.4% | +17.8% | +15.1% | |
SHOP | Revenue | +27.4% | +24.2% | +26.6% |
| EPS | +25.1% | +28.2% | +34.3% | |
AMZN | Revenue | +15.9% | +14.6% | +16.0% |
| EPS | +76.8% | −16.1% | +30.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Coupang's customers came back faster than its margins did. The South Korean retailer — it owns the inventory it sells, delivers it overnight on its own Rocket network, and charges a WOW subscription for the privilege — told investors on 4 August that retained and returning shoppers were spending about 16% more than a year earlier. The same quarter carried an operating loss of $556m.
The distance between those two facts is the bill for a data breach disclosed in November 2025, and it is the whole story of a stock that has lost 57% of its value in a year. Coupang committed ₩1.685tn — about $1.17bn — in compensation, four single-use vouchers of roughly $34 each to every one of 33.7m affected customers including cancelled members, paid out from 15 January. In June, South Korea's Personal Information Protection Commission fined the company about $409m, a record penalty, and the charge landed in second-quarter results. Against a company capitalized at $25.7bn, that is real money spent to keep a customer base that, by the chairman's own May account, had recovered nearly 80% of its lost paid membership.
What actually broke
Strip the regulatory charge and the quarter's operating loss narrows to roughly $146m, which management framed as a modest sequential improvement in loss margin. The damage that persists is in gross profit: 28.2% of revenue in the June quarter against 30.0% a year earlier, with gross profit down 2.6% in absolute terms — the only shrinking gross profit among the large emerging-market marketplaces. Fulfillment capacity was built for volumes that never arrived, volume-based supply-chain savings went with them, and marketing stayed elevated to win the members back.
Top-line growth has decelerated for four straight quarters, from 17.8% to 3.9%, to $8.856bn. But roughly six points of that is the won: revenue grew 10% on a constant-currency basis. "The vast majority of our customer spend never moved," founder and chief executive Bom Kim told investors on the 4 August call. "That group is spending at the highest levels in our history and compounding similarly to before last year's data incident." Asked to confirm the recovery timetable, he was flat: "That's correct. We're talking about margin recovery for product commerce next year." Consensus is not waiting: 2026 revenue of $37.01bn, up 6.3%, a loss of $0.51 a share, and no return to profit before 2027.
The month that had nothing to do with Coupang
That is a de-rating a company earns. The puzzle sits beside it. MercadoLibre, which runs Latin America's largest marketplace and the Mercado Pago wallet and lending book, grew revenue 49.8% last quarter to its first $10bn, with 15-to-90-day arrears on a $16.4bn credit portfolio at 7.0%, near historical lows. Sea Limited, which pairs the Shopee marketplace with Garena's games and the Monee lending arm, grew revenue 48.1% and operating income 28.4%, with 90-day non-performing loans on a book of $11.1bn steady at 1.0%. Neither loan book is deteriorating. Both stocks fell with Coupang over the past thirty days, by 7.0% and 13.5% against its 11.7%, through a week in which the Federal Reserve raised rates a quarter point on 16 September and long yields pushed above 5%. Three incompatible business models, one direction: the likelier reading for the month is the discount rate rather than the mechanics.
Over twelve months the dispersion tells the truer story — MercadoLibre down 27.8%, Sea 46.6%, Coupang 57.2% — and only one of the three has a broken earnings line to justify its place at the bottom. Coupang is priced accordingly, at 2.45x forward gross profit and 0.72x trailing sales, with no forward price-to-earnings ratio because there are no forward earnings to divide by.
The vouchers have been paid and the fine is booked. What Coupang has left to prove is that warehouses sized for a customer base it briefly lost fill back up before the middle of next year.