

Two Cancelled Grands Prix Erased Rights Revenue Formula One Had Already Contracted
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A media-rights contract is supposed to pay whether or not anyone turns up. Liberty Media's Formula One found out otherwise: with five races held in the June quarter against nine a year earlier, tracking-stock revenue fell 30.4% to $934m, and Liberty blamed part of it on lower contractual media-rights revenue. Rights fees are earned race by race, so deleting two Gulf events deleted the money under an unchanged contract.
TKO, which owns UFC and WWE, ran the other way — revenue up 18.2% on step-ups from the Paramount and ESPN deals, guidance raised — and its shares still fell over the past year. Live Nation, which owns no content and is paid per ticket, set records on every operating meter while carrying a jury verdict pricing liability at $1.72 a primary ticket. One heading, three ways of being paid, three unrelated problems.
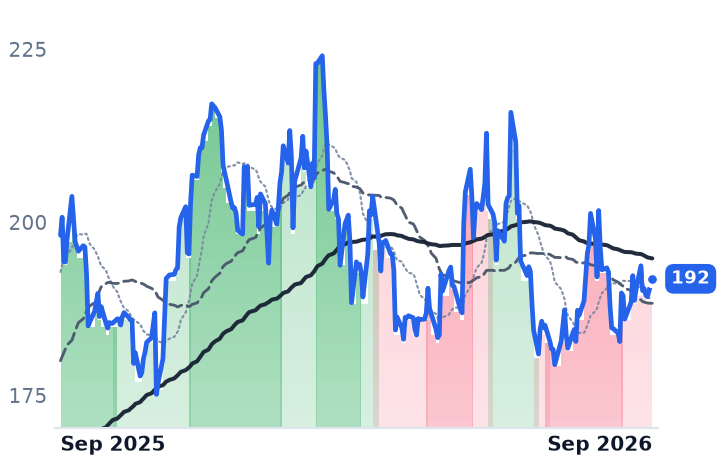
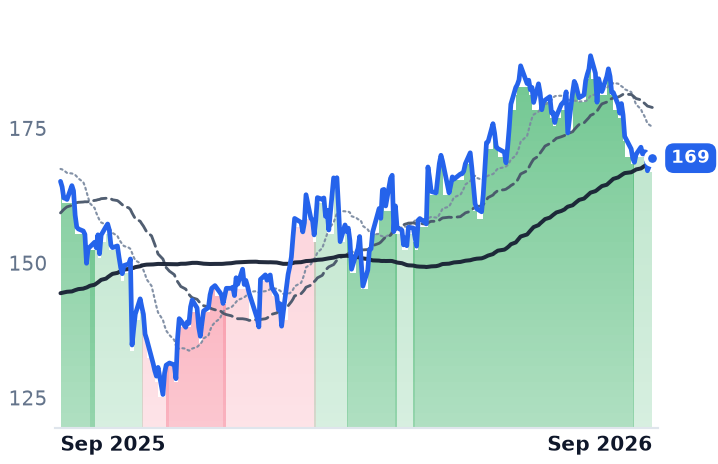
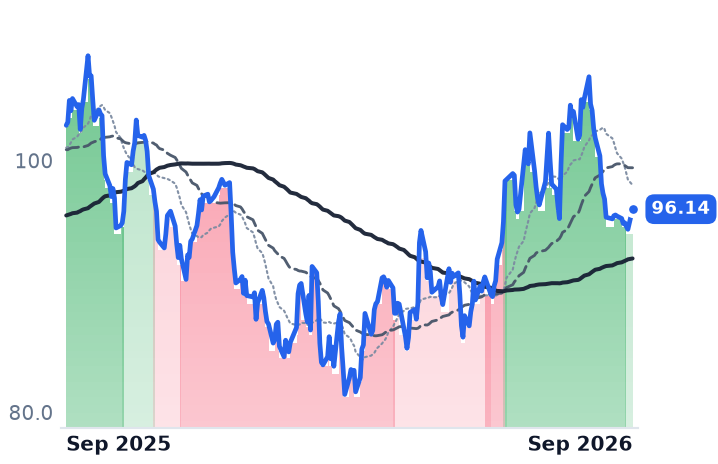
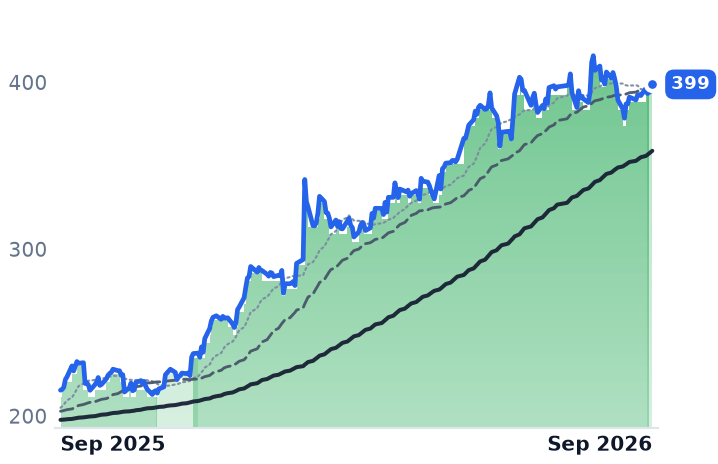
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TKO | TKO | Live Events & Sports Properties | ⚠️ Emerging Bear | −0.8% | −3.2% |
LYV | Live Nation Entertainment | Live Events & Sports Properties | 🟢 Cont. Bull | −8.2% | +2.6% |
FWONK | Liberty Media | Live Events & Sports Properties | 🌱 Emerging Bull | −9.9% | −6.5% |
| Compared against · context, not the story | |||||
MSGS | Madison Square Garden Sports | Live Events & Sports Properties | 🟢 Cont. Bull | −1.0% | +85.1% |
MANU | Manchester United | Live Events & Sports Properties | 🟢 Cont. Bull | −16.9% | +29.8% |
BATRK | Atlanta Braves | Live Events & Sports Properties | 🟢 Cont. Bull | −3.7% | +22.3% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +14.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TKO | $14.4B | 63.5x | 41.3x | 2.7x | 2.5x | 5.0x | 4.6x | 11.6x | 11.6% |
LYV | $39.5B | n/m | — | 1.5x | 1.4x | 3.3x | 3.1x | 24.3x | 3.5% |
FWONK | $24.1B | 47.7x | 53.1x | 5.1x | 5.0x | 15.4x | 15.4x | 18.8x | 3.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MSGS | $9.7B | — | — | 8.4x | 9.0x | 30.4x | 32.4x | 253.4x | 0.6% |
MANU | $3.5B | n/m | 454.3x | 3.9x | 4.7x | 15.6x | 18.8x | 12.2x | -6.6% |
BATRK | $3.2B | 47.4x | — | 2.4x | 4.1x | 7.6x | 12.7x | 27.9x | 4.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TKO | Revenue | +23.3% | +1.0% | +26.5% |
| EPS | +92.2% | +17.8% | +32.7% | |
LYV | Revenue | +12.4% | +9.5% | +9.3% |
| EPS | +65.7% | −653.8% | +52.5% | |
FWONK | Revenue | +7.5% | +10.8% | +7.7% |
| EPS | −20.3% | +21.9% | +29.4% | |
MSGS | Revenue | +10.3% | −2.1% | +3.8% |
| EPS | −72.1% | +202.5% | +133.3% | |
MANU | Revenue | −1.3% | +13.9% | +6.7% |
| EPS | +36.6% | −115.1% | −33.3% | |
BATRK | Revenue | +8.1% | +4.6% | +6.6% |
| EPS | −88.1% | −107.7% | −3088.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
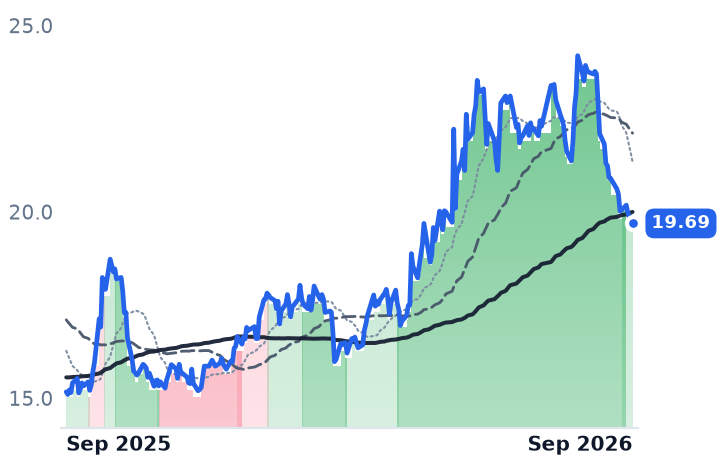
Formula One held five races in its June quarter against nine in the same quarter a year earlier, and the four missing weekends took contracted money with them. Liberty Media, whose Formula One Group tracking stock holds the exclusive commercial rights to the world championship, reported revenue down 30.4% to $934m, operating income down 68.6% and net income of $5m. The company attributed the fall in part to "a decline in contractual media rights revenue and a decline in title sponsorship revenue related to event mix".
That sentence is the mechanism the whole heading turns on. Sports media rights are treated as the safest cash flow in entertainment — negotiated years ahead, escalating on a schedule fixed at signature — but they are recognized per event, so no event means no fee. The Bahrain and Saudi Arabian Grands Prix were cancelled because of the war in the Middle East, cutting the 2026 calendar from 24 races to 22; Liberty's accounts now assume 23 after an October date at Sepang partially replaced Bahrain, and it expects a full calendar in 2027.
Everything else at F1 went up
The per-race meters did not deteriorate. Nearly 3.7m people attended race weekends this season against 3.4m for the same events last year, every 2026 race sold out, and five circuits set attendance records, Silverstone drawing 564,000 over four days. The US media deal repriced upward by two-thirds at renewal: Apple pays roughly $150m a year under a five-year exclusive streaming agreement beginning this year, against the $90m ESPN had been paying. "Demand for our brands remains robust and resilient," chief executive Derek Chang said with the August 6 results.
The equity has nonetheless de-rated, and honestly: the tracking stock's forward price-to-earnings multiple of 53.1x sits above its trailing 47.7x, meaning consensus earnings are falling faster than the share price. Analysts see recovery in 2027 — revenue of $5.28bn, up 10.8% — which is what a race-count problem should look like.
TKO's contracts stepped up; its shares did not
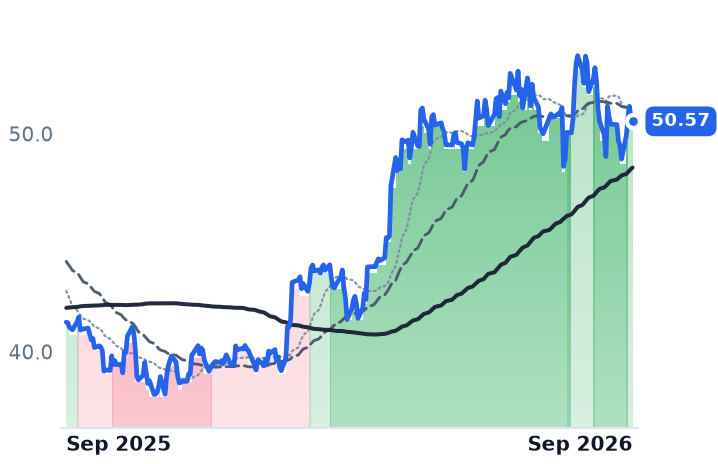
TKO Group Holdings, the New York parent of UFC and WWE, is the same asset class billed differently. Its June-quarter revenue rose 18.2% to $1,547.1m, with gross margin widening to 64.1% from 56.0% — contracted fees landing against a largely fixed cost of producing the slate. UFC media-rights revenue was $325.2m as the Paramount agreement began in January, and WWE's rose 29% to $359.7m on the ESPN deal that started in September 2025. The Paramount contract is $7.7bn over seven years, back-weighted so the escalator is written in at signature. Adjusted EBITDA rose 23% to $649.9m and full-year guidance went up to $2.275–$2.305bn.
"Sports has become the anchor of premium media, commanding unrivaled live audiences and cultural relevance," president Mark Shapiro said on the August 3 call. The shares fell 6.7% over the past twelve months anyway. The available explanation is arithmetic: consensus has revenue growing 23.3% this year and 1.0% next, as the two step-ups annualize. TKO trades at 41.3x forward earnings against 63.5x trailing — the compression is the doubling in expected earnings, and the risk is what happens after.
Paid by the ticket instead
Live Nation Entertainment owns almost none of what it sells. It promotes, operates more than 250 venues, and collects a fee per fee-bearing ticket through Ticketmaster, which holds roughly 86% of ticketing at major concert venues against about 9% for AEG's AXS. Every meter rose in the June quarter: 90m fee-bearing tickets, up 8%, gross transaction value above $10bn, event-related deferred revenue at a record $6.4bn and sponsorship revenue of $383m. "We've seen no consumer issues to date," chief executive Michael Rapino told analysts on July 30.
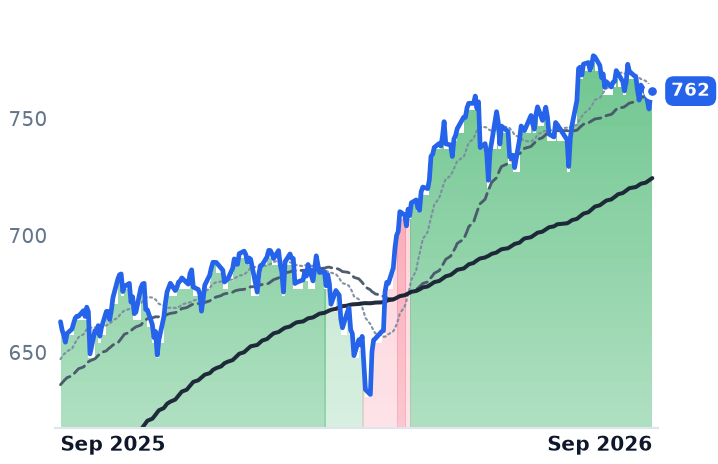
What the meters cannot settle is the April 15 jury verdict, in which a federal jury found Live Nation and Ticketmaster liable on every antitrust count and set damages at $1.72 for each primary ticket sold pursuant to the conduct. The remedy phase — divestiture, structural limits or behavioral conditions — remains undecided, and the shares fell 8.1% in the past month. On negative GAAP earnings the only usable anchor is 24.3x trailing enterprise value to EBITDA, which consensus has collapsing toward the mid-teens by 2027.
The tier nobody watches is deflating
Madison Square Garden Sports, which owns the Knicks and Rangers and nothing else, is the useful control. Its contracted local media-rights revenue fell to $125.7m in fiscal 2026 from $157.4m after MSG Networks restructured its debt and the rights agreement was renegotiated downward. The stock rose 85.2% over the year regardless, on franchise scarcity and a Rangers spin-off. Sports rights are not one market: the national streaming tier is inflating while the regional tier writes itself down.
So the segment's 17% twelve-month gain was never a rights trade — it was the team equities, MSGS alongside the Braves and Manchester United lines, while TKO, Formula One and Live Nation averaged a 4.7% loss against the S&P 500's 15% gain. Nothing is being un-priced that was priced in the first place. F1's fade is earned by a calendar; TKO's is an annualization cliff sitting behind rising cash flow; Live Nation's is a number a jury wrote. The one thing they share is duration — escalators running into the next decade, race contracts, franchise terminal values — and the 10-year Treasury yield touched 5.011% on September 14, its highest since 2023, discounting all of it harder.
The war that pushed those yields up is the same war that deleted two race fees. It is rare to watch a macro shock arrive twice at the same income statement, once through the discount rate and once through the calendar.