

Record Beef Prices Hit Franchisees First: Wendy's Largest Filed Chapter 11 Owing $24.9m
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Record beef costs reach a franchisor's income statement only secondhand — and the layer that actually pays them just cracked. Meritage Hospitality, the largest United States franchisee of Wendy's with 314 restaurants, filed for Chapter 11 on September 17 with the chain's own franchising arm the biggest unsecured creditor.
McDonald's, about 95% franchised, still earned an 84.5% margin on $4.4bn of royalty and rent in the June quarter, while margin dollars from the restaurants it runs itself in the US fell 6%. Shake Shack, which operates nearly all its own Shacks, took the cost directly: food and paper rose to 28.8% of Shack sales and restaurant-level margin fell 90 basis points.
The Wendy's and Shake Shack de-ratings track estimates falling with them. McDonald's is the odd one: trailing earnings up 5.5%, multiple down 22%. Arcos Dorados, its Latin American master franchisee, is the exception — Brazil margins expanded 180 basis points.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MCD | McDonald's | Quick Service - Burgers & Sandwiches | ⚠️ Emerging Bear | −8.4% | −17.1% |
SHAK | Shake Shack | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −27.6% | −45.3% |
WEN | The Wendy's | Quick Service - Burgers & Sandwiches | 🔴 Cont. Bear | −25.2% | −25.0% |
| Compared against · context, not the story | |||||
ARCO | Arcos Dorados | Quick Service - Burgers & Sandwiches | ⚠️ Emerging Bear | −5.4% | +10.8% |
QSR | Restaurant Brands International | Quick Service - Pizza | 🟢 Cont. Bull | −9.9% | +15.8% |
YUM | Yum! Brands | Quick Service - Pizza | ⚠️ Emerging Bear | −9.8% | −6.7% |
DPZ | Domino's Pizza | Quick Service - Pizza | 🔴 Cont. Bear | −13.9% | −30.1% |
CMG | Chipotle Mexican Grill | Quick Service - Mexican & Bowls | 🌱 Emerging Bull | −9.4% | −16.7% |
WING | Wingstop | Quick Service - Chicken & Wings | 🔴 Cont. Bear | −9.8% | −59.1% |
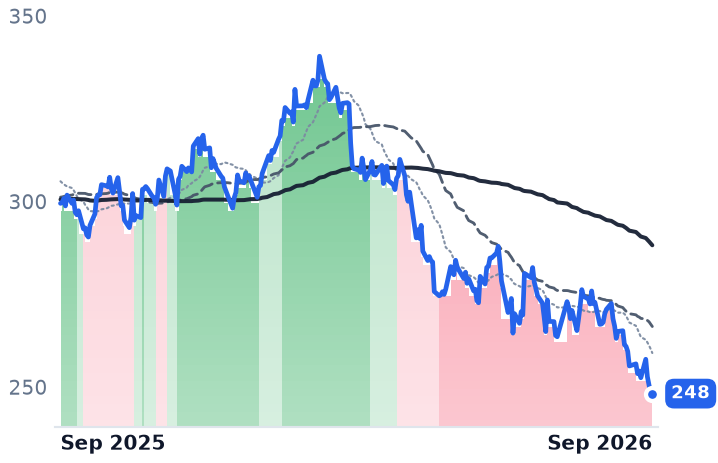
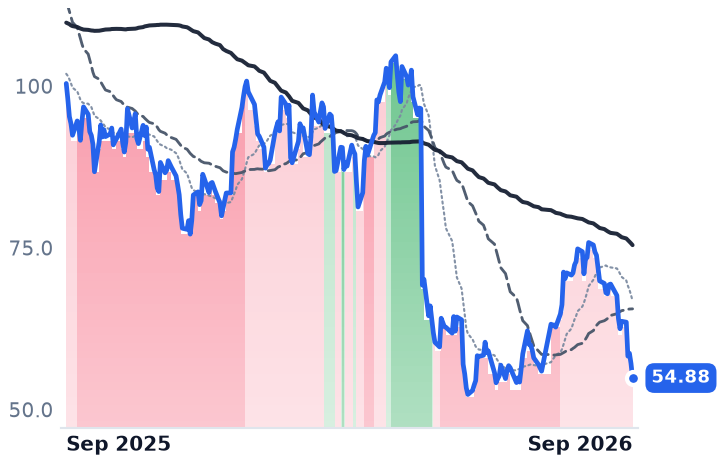
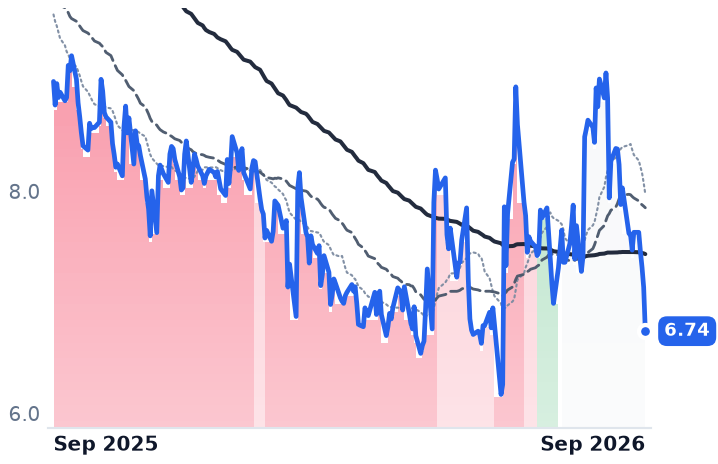
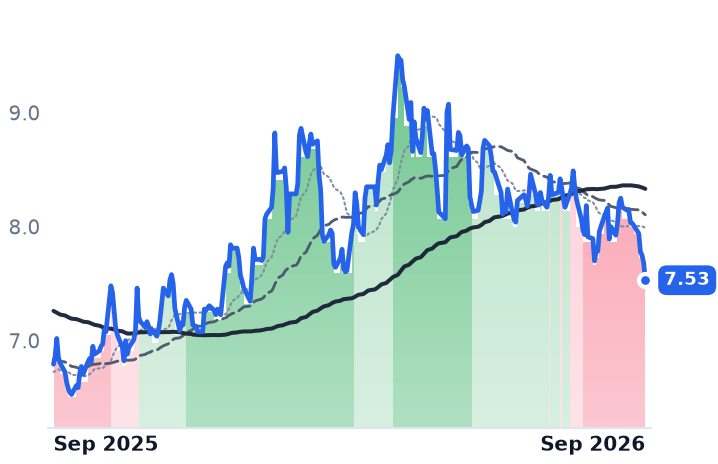
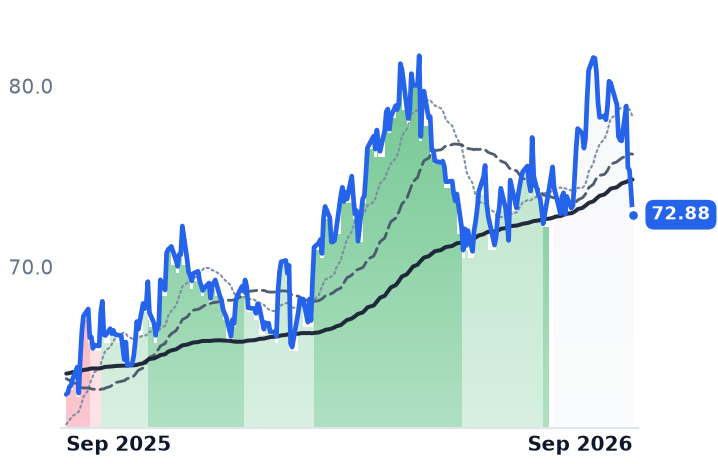
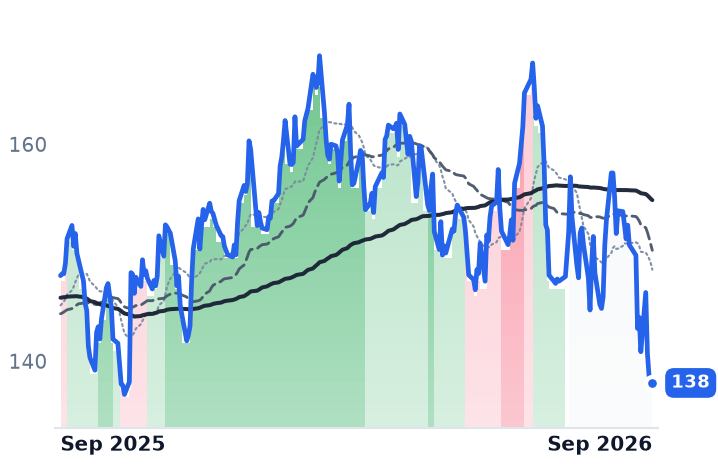
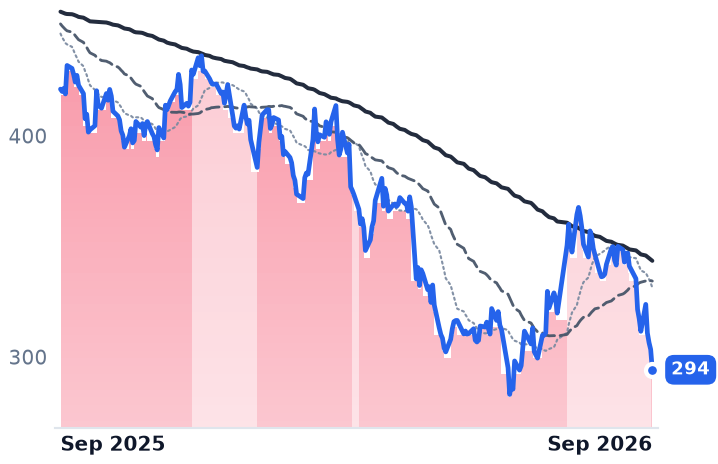
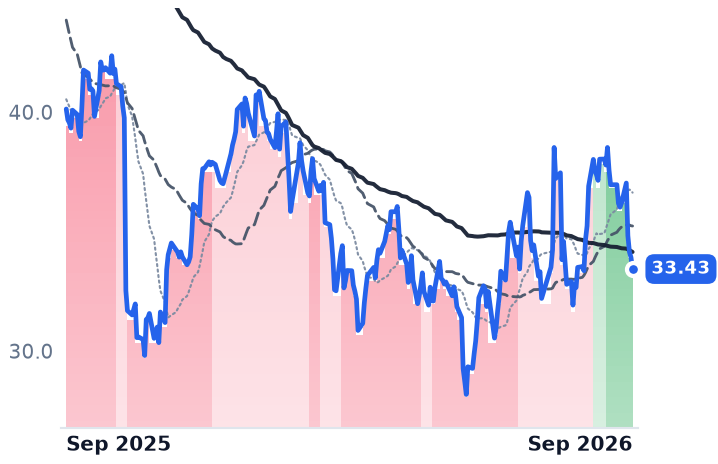
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MCD | $176.4B | 20.1x | 19.2x | 6.4x | 6.3x | 11.1x | 10.9x | 15.3x | 4.4% |
SHAK | $2.2B | 55.8x | 48.4x | 1.4x | 1.3x | 5.5x | 5.2x | 12.2x | 0.4% |
WEN | $1.3B | 10.2x | 13.3x | 0.6x | 0.6x | 2.1x | 2.1x | 10.3x | 20.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARCO | $1.6B | 6.2x | 9.4x | 0.3x | 0.3x | 2.6x | 2.4x | 5.5x | 6.0% |
QSR | $26.3B | 27.6x | 18.7x | 2.7x | 2.7x | 6.1x | 6.0x | 15.9x | 5.8% |
YUM | $42.0B | 19.0x | 23.1x | 4.8x | 4.7x | 10.5x | 10.2x | 18.6x | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DPZ | $11.1B | 18.9x | 17.7x | 2.2x | 2.1x | 5.5x | 5.3x | 16.2x | 5.9% |
CMG | $41.9B | 29.2x | 28.7x | 3.5x | 3.2x | 9.5x | 8.9x | 20.5x | 3.6% |
WING | $3.5B | 31.7x | 28.3x | 5.0x | 4.5x | 6.0x | 5.5x | 15.4x | 3.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MCD | Revenue | +5.7% | +5.1% | +4.2% |
| EPS | +6.4% | +8.0% | +7.0% | |
SHAK | Revenue | +14.1% | +14.7% | +13.3% |
| EPS | −12.2% | +22.8% | +27.3% | |
WEN | Revenue | +1.3% | −0.5% | +3.3% |
| EPS | −41.7% | +3.9% | +11.8% | |
ARCO | Revenue | +13.3% | +6.4% | +8.3% |
| EPS | −12.0% | +5.5% | +16.5% | |
QSR | Revenue | +5.2% | +1.7% | −0.4% |
| EPS | +10.4% | +9.4% | +6.5% | |
YUM | Revenue | +10.0% | +3.7% | +5.7% |
| EPS | +8.5% | +10.2% | +10.8% | |
DPZ | Revenue | +5.4% | +2.4% | +3.9% |
| EPS | +7.6% | +9.8% | +8.0% | |
CMG | Revenue | +9.0% | +11.0% | +10.9% |
| EPS | −1.6% | +19.6% | +18.0% | |
WING | Revenue | +11.6% | +15.4% | +14.1% |
| EPS | +17.0% | +22.2% | +24.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The company that buys the beef is rarely the company whose name is over the door. Meritage Hospitality Group, which runs 314 Wendy's restaurants and is the chain's largest franchisee in the United States, filed for Chapter 11 on September 17 after failing to meet payment obligations under its franchise agreements. Wendy's own franchising subsidiary is listed as the largest unsecured creditor, on a $24.9m claim for deferred fees. Meritage had already closed roughly 60 restaurants earlier in the year.
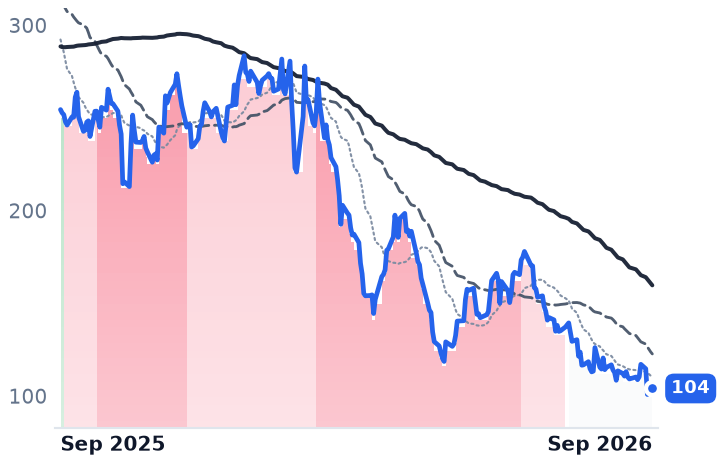
A franchisor's income statement carries no line for ground beef. It carries a royalty percentage of somebody else's sales, plus rent on property the franchisor owns or master-leases at a markup. Input inflation therefore lands on the operator first and on the brand owner later — through franchisee cash flow, which decides whether units get built, whether they stay open, and how much discounting an operator can fund. Four burger businesses have been marked down for a year on that question. McDonald's, Shake Shack, Wendy's and Arcos Dorados fell an equal-weighted 19.9% in the twelve months to September 18, a grind rather than a gap: McDonald's closed lower in 13 of the 18 sessions from late August, none worse than about 2%. Restaurant Brands International, which owns Burger King, rose 15.8% over the same year, so this is not the market marking down everything that sells a fast burger.
The input is a supply story
The American beef cow herd has shrunk to 27.6 million head, the smallest since 1961 according to the Department of Agriculture's January 2026 inventory, and cattle prices are expected to average roughly $241 per hundredweight this year, about 8% above 2025. Retail ground beef set an all-time high of $6.90 a pound in May. Fewer cattle, not hungrier customers.
What McDonald's is actually paid
About 95% of McDonald's restaurants were franchised at June 30, and those revenues are rent and royalties on a percent of sales. In the June quarter franchised revenue was $4,393m, up 4%, against $2,525m of sales from restaurants the company runs itself. The franchised line produced $3,713m of restaurant margin — 84.5% — while the company-operated line produced 15.3%. And in the US, company-operated margin dollars fell 6% to $91m. The cost shock is visible exactly where the structure says it should be.
The volume meter is worse than the margin. Global comparable sales rose 1.3%, against 3.8% a year earlier, and the US gain of 0.8% came from higher average check with fewer guests. Only 60% to 65% of the US system implemented the ten-item under-$3 value menu, chief executive Chris Kempczinski said, and a loose $3 parameter let some franchisees raise prices on items like small fries — a franchisor can mandate value but cannot pay for it out of the operator's profit and loss. "We made a bad trade in Q2... And we've got to get that fixed," Kempczinski told investors on the August 4 call, attributing two-thirds of the US sales miss to the offer change. Numerator estimates the company lost $310m of sales from lower-income customers in the quarter — in the demographic that is supposed to trade down toward it.
The operator's half of the same shock
Shake Shack runs nearly all of its Shacks itself, so it buys the beef. Food and paper rose 60 basis points to 28.8% of Shack sales, and restaurant-level profit of $92.7m was 23.0% of sales, down 90 basis points on record beef costs. Average weekly sales per Shack were flat at $78,000: the 17.2% revenue growth to $417.6m came from opening more Shacks, while operating income fell 7.3%. Operating leverage running backwards. The company had already cut second-quarter and full-year guidance in June, taking restaurant-level margin guidance to 22.0-23.0% from 24.0-24.5%. "Our second quarter results reflect a business that continues to execute across sales, development, and profitability despite operating in one of the most challenging cost environments we have faced in many years," chief executive Rob Lynch said on August 5.
Arcos Dorados, McDonald's exclusive master franchisee across 20 Latin American and Caribbean markets, shows the beef shock is North American. It posted record quarterly revenue of $1.31bn with adjusted profit before interest, tax, depreciation and amortization up more than 20%, on a third consecutive quarter of falling food-and-paper cost. "Brazil was the standout performer for Arcos during this quarter. EBITDA margin expanded 180 basis points with an EBITDA margin of 14.6%," chief financial officer Mariano Tannenbaum said on the August 13 call. It is the only one of the four whose shares are higher than a year ago, up 11.6%, at 6.2x trailing earnings.
What the de-rating is paying for
Wendy's decline is earned. US same-restaurant sales fell 7.0% on a 12.5% traffic decline, the dividend was cut to $0.07, the outlook withdrawn, net leverage sits at 5.0x, and 21 new US openings in the first half were swamped by 289 closures. Its shares trade at 10.2x trailing earnings but 13.3x forward, because consensus 2026 earnings per share are 41.7% below 2025 — profit falling faster than price. Shake Shack's 48.4x forward multiple sits against consensus 2026 earnings per share now expected to fall 12.2%; on enterprise value to EBITDA it has crossed below McDonald's, 12.2x against 15.3x.
McDonald's is the one the business does not fully explain. It trades at 20.1x trailing and 19.2x forward earnings, against roughly 25.8x a year ago — a 22% contraction while trailing earnings per share grew 5.5%, and while analysts trimmed price targets without changing ratings. Part of that is rate arithmetic: the 4% dividend increase to $1.93 a quarter announced on September 17, a 50th consecutive annual raise, yields 3.11% at the current price — below the 3.75%-4.00% federal funds target the Fed set on September 16 in its first hike since 2023. An annuity re-prices when the risk-free rate rises. The rest is the question Meritage just made concrete: the royalty-and-rent stream is only as durable as the operators underneath it, and for the first time in this cycle one of them stopped paying.
McDonald's brings a plan it calls "McDonald's > NEXT" to an investor day in Chicago on September 23. The targets read hardest there will not be the ones describing its own margin, but whatever it can say about the profit left in the restaurants it does not own.