

Akamai Halted Its Buyback to Fund Servers After Repurchasing $410m at $134.54 a Share
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Akamai's gross profit shrank last quarter while its revenue grew — the combination that tells you a company is buying its next business with the margin of its old one. June-quarter revenue rose 5.4%, gross profit fell 0.5%, and operating income fell 47%. Capital spending hit 32% of revenue and is guided to roughly 40% for the year, funded by $3.45bn of new convertible notes and by stopping the repurchase program.
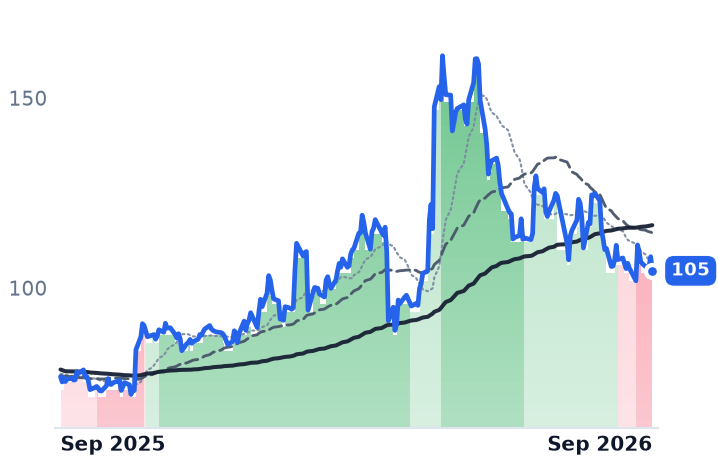
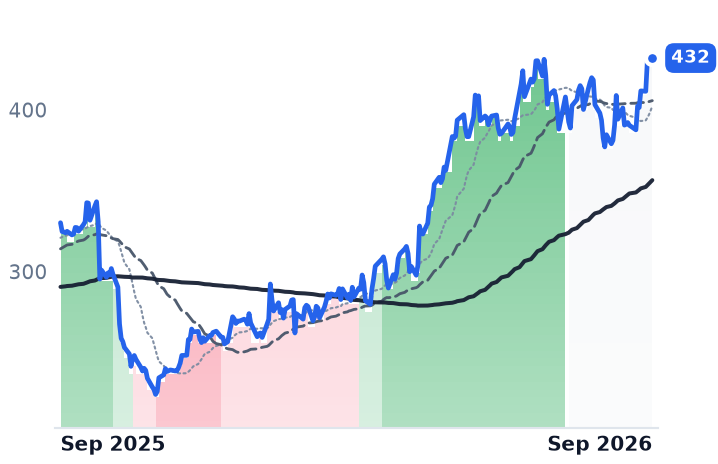
The shares have fallen in weekly steps since May and now trade below where they sat before the $1.8bn Anthropic compute contract was disclosed. Fastly, the other content-delivery company paid per gigabyte, rose over the same three months, and Cloudflare — the same physical network, billed per contract — made a record high. This de-rating belongs to Akamai's own income statement rather than to delivery economics as a class.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
AKAM | Akamai Technologies | Network & Application Delivery | ⚠️ Emerging Bear | −5.3% | +36.3% |
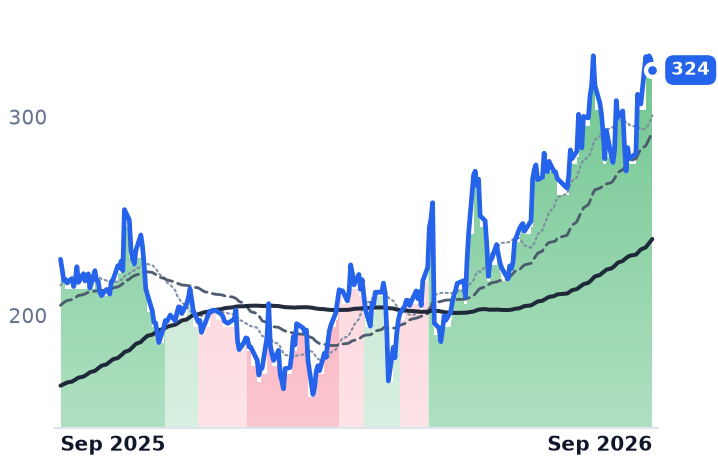
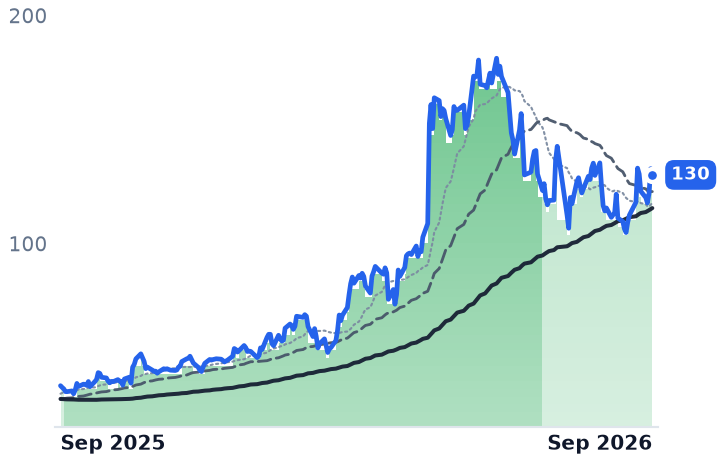
NET | Cloudflare | Network & Application Delivery | 🟢 Cont. Bull | +10.4% | +41.8% |
| Compared against · context, not the story | |||||
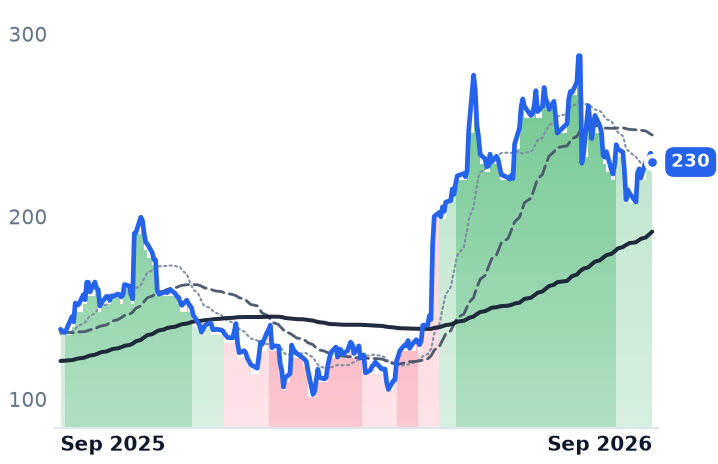
DDOG | Datadog | Data & Analytics Platforms | 🟢 Cont. Bull | −2.4% | +66.2% |
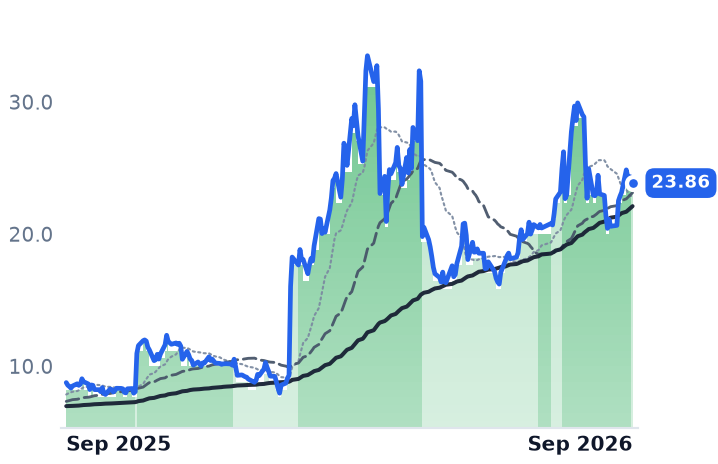
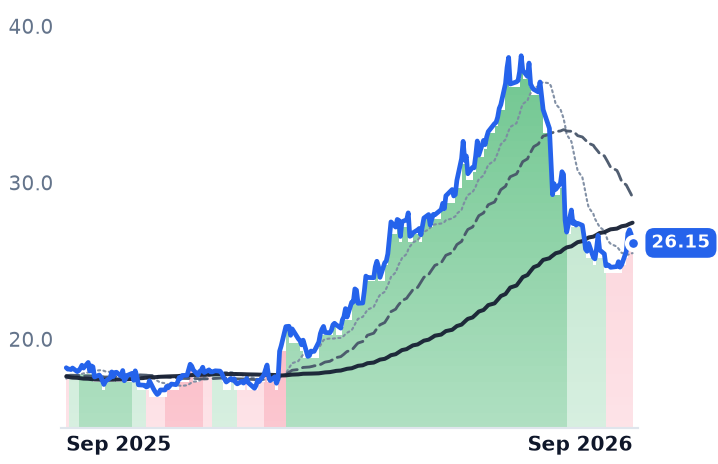
FSLY | Fastly | Cloud Infrastructure & Platform | 🟢 Cont. Bull | −4.4% | +172.4% |
FFIV | F5 | Network & Application Delivery | 🟢 Cont. Bull | +12.3% | +30.8% |
DOCN | DigitalOcean | Cloud Infrastructure & Platforms | 🟢 Cont. Bull | +12.5% | +245.1% |
ATEN | A10 Networks | Network & Application Delivery | 🟢 Cont. Bull | +0.1% | +43.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AKAM | $15.2B | 36.8x | 15.6x | 3.5x | 3.4x | 6.2x | 6.0x | 17.9x | 4.1% |
NET | $115.0B | n/m | 256.8x | 45.8x | 40.1x | 63.1x | 55.2x | — | 0.3% |
DDOG | $78.7B | 444.9x | 87.4x | 19.9x | 17.6x | 25.0x | 22.1x | 302.3x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLY | $3.6B | n/m | 43.9x | 5.2x | 4.9x | 8.5x | 7.9x | n/m | 1.2% |
FFIV | $21.7B | 30.3x | 22.2x | 6.6x | 6.4x | 8.0x | 7.8x | 21.1x | 4.5% |
DOCN | $13.0B | 44.1x | 76.5x | 12.9x | 11.1x | 22.5x | 19.3x | 36.7x | 0.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ATEN | $1.9B | 43.5x | 25.1x | 6.1x | 5.7x | 7.6x | 7.2x | 30.1x | 3.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AKAM | Revenue | +7.2% | +13.0% | +11.2% |
| EPS | −4.6% | +6.4% | +13.9% | |
NET | Revenue | +33.7% | +28.4% | +27.1% |
| EPS | +38.1% | +32.6% | +35.1% | |
DDOG | Revenue | +31.8% | +22.4% | +22.8% |
| EPS | +25.4% | +17.0% | +22.1% | |
FSLY | Revenue | +20.9% | +12.0% | +11.2% |
| EPS | +897.9% | +11.2% | +17.0% | |
FFIV | Revenue | +10.1% | +7.4% | +7.5% |
| EPS | +12.6% | +4.0% | +11.7% | |
DOCN | Revenue | +31.2% | +53.5% | +43.7% |
| EPS | −29.0% | +23.2% | +60.4% | |
ATEN | Revenue | +14.4% | +11.7% | +12.1% |
| EPS | +18.5% | +14.2% | +15.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Akamai Technologies, which delivers and secures web traffic from servers embedded inside internet providers' networks in more than 130 countries, stopped buying back its own stock this summer. It had already spent $616m on repurchases during 2026, including $410m in the June quarter at an average price of $134.54. The shares closed at $104.52 on 18 September. The cash is going into servers and graphics processors instead.
The trade is legible in a single line of the income statement. June-quarter revenue grew 5.4% to $1.1bn; gross profit fell 0.5% to $613.8m, pulling gross margin down more than three points to 55.8%. Operating income fell 47%. Akamai is spending down a delivery annuity built over two decades to buy a compute business whose revenue is dated to 2027, and the equity has to carry the interval.
Three meters, one network
Security — bot and application defense, microsegmentation, application programming interface protection — brought in $604m in the quarter, up 10%, and now accounts for 55% of revenue at a $2.4bn annualized rate. Delivery and other cloud applications fell 6% to $396m, and the company's own quarterly filing gives the reason without euphemism: the decline was "driven by a decrease in delivery revenue due to downward pricing of contract renewals". Cloud Infrastructure Services, the rented-compute line, grew 39% to $99m against a management target of at least 50% growth this year.
The replacement costs money before it earns any. Capital expenditure reached $347m in the June quarter, 32% of revenue against 21% a year earlier, with full-year capex guided near 40% of revenue plus $500m for graphics-processor replenishment, most of it landing in early 2027. Management says that capacity is sold out. The funding came from $3.45bn of zero-coupon convertible notes, taking convertible debt to roughly $7.6bn and lifting the diluted share count to 153.7m as the stock crossed conversion prices. "Akamai continues to build momentum and gain wide industry recognition as a key infrastructure provider for the AI-driven economy," chief executive Tom Leighton told investors on 6 August.
What did not move
The fall arrived without a gap: weekly steps down from a $161.14 close on 13 May to $104.52, a 35% decline that leaves Akamai up 35.6% over twelve months and therefore absent from every list of big movers. The price trend turned fully negative on 8 September and stayed there through 18 September.
The obvious explanations fail. Fastly, the other content-delivery firm paid per gigabyte delivered, rose 33.3% over the three months Akamai fell 16.3%; F5 rose 12.1%. On 14 September, when an Anthropic essay on artificial-intelligence safety lifted listed security names and Cloudflare rose 7.8%, Akamai — which books more than half its revenue in security — fell 1.1%. Nor does the rate backdrop work: the Federal Reserve's first hike in three years landed on 16 September, and the same week the company with no trailing earnings made an all-time high.
That company is Cloudflare, which runs a comparable global network from 335-plus cities and sells security, Zero Trust access and Workers compute on per-contract subscriptions rather than per gigabyte. Its June-quarter revenue grew 35.9%, a fourth straight quarter of acceleration; dollar-based net retention rose to 120% from 114%; customers spending above $100,000 a year reached 4,698, up 27%. Network capital spending ran at 7% of revenue against a 14-15% guide. Chief executive Matthew Prince has been explicit about declining Akamai's bargain: "If you're selling what is just commodity compute, if you're basically letting an AI company use your balance sheet and your credit rating in order to buy servers that are the same as everybody else's servers, then that's just not attractive business for us." Cloudflare trades at 63.1x trailing gross profit, up from roughly 60x three weeks earlier; Akamai trades at 6.2x, down from 7.1x in late August on gross profit that is itself contracting.
Billing by consumption is no protection either. Datadog, which meters infrastructure and application monitoring by data volume, grew 35.6% and still lost a fifth of its value in one session on 6 August after disclosing that its largest artificial-intelligence customer had renewed at reduced usage. It sits at 25x gross profit, between the two. All three grew gross profit more slowly than revenue.
The verdict
Most of Akamai's decline is earned. Shrinking gross profit, halved operating income, a suspended buyback, a rising share count and a capex line approaching two-fifths of revenue are not a sentiment problem, and the market has repriced them correctly. What nothing in the second quarter explains is the last leg: the shares sit 14.3% below their close the day before the seven-year, $1.8bn Anthropic contract was disclosed, so the entire deal re-rating and more has been given back, while consensus still carries 13% revenue growth for 2027 and the stock's 15.6x forward earnings rests on a per-share estimate that is down 4.6% year on year against a trailing multiple of 36.8x. The disagreement is not about June; it is about whether signed commitments convert.
The first Anthropic revenue is guided to begin in the December quarter at $20-25m. Delivery revenue fell by roughly that much, year on year, in the June quarter alone.