

LKQ Lost $140m of Sales to a German Software Switch While Its Claim Volumes Improved
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A year of selling has treated the auto aftermarket as one recession-proof category. The June quarter says it is two businesses, and they broke for opposite reasons.
LKQ cut full-year guidance after an enterprise software rollout in Germany cost it a quarter of revenue in one region — while the insurance claims that fund its collision parts stabilized and alternative-parts use hit a record above 40% of authorized repairs. O'Reilly did the reverse: professional sales up 10%, gross margin flat at 51.4%, full-year comparable-sales guidance raised — and the shares fell about a fifth over twelve months as the premium multiple set last September unwound.
The unresolved half is the do-it-yourself customer, where visit counts are already falling and a 5.5% pricing tailwind fades to 1–2% in the back half.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ORLY | O'Reilly Automotive | Automotive Parts Retail | 🔴 Cont. Bear | −4.4% | −18.5% |
LKQ | LKQ | Aftermarket Distribution & Service | 🔴 Cont. Bear | −10.2% | −22.5% |
| Compared against · context, not the story | |||||
AZO | AutoZone | Automotive Parts Retail | 🔴 Cont. Bear | −3.6% | −31.0% |
DORM | Dorman Products | Aftermarket Distribution & Service | 🌱 Emerging Bull | −6.6% | −21.7% |
AAP | Advance Auto Parts | Automotive Parts Retail | 🟢 Cont. Bull | +3.3% | −26.4% |
GPC | Genuine Parts | Automotive Parts Retail | 🔴 Cont. Bear | −3.0% | −5.1% |
BGSI | Boyd Group Services | Aftermarket Distribution & Service | 🔴 Cont. Bear | −11.3% | −48.4% |
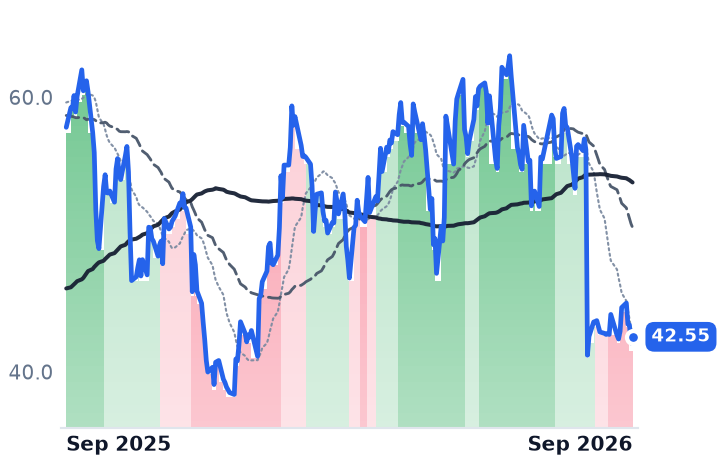
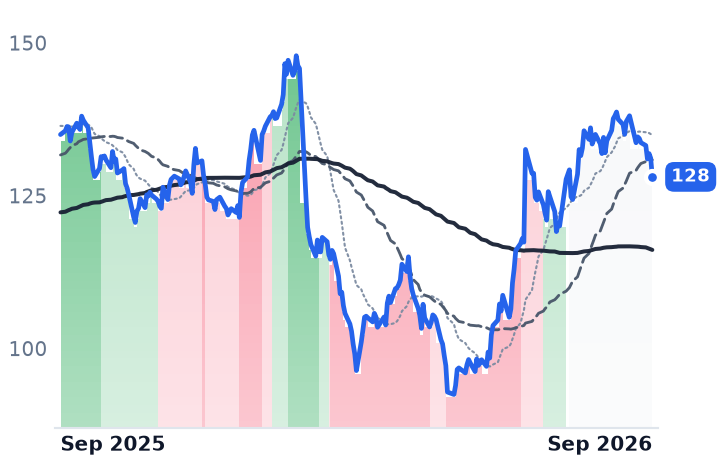
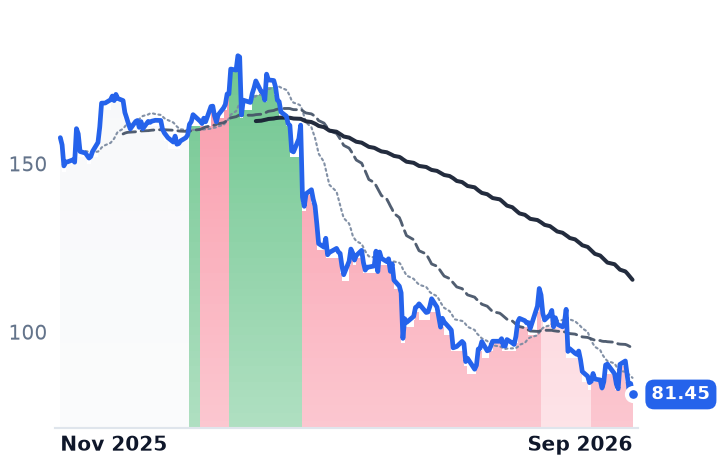
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ORLY | $70.2B | 26.7x | 25.8x | 3.8x | 3.7x | 7.3x | 7.1x | 19.7x | 3.1% |
LKQ | $5.9B | 12.9x | 8.7x | 0.4x | 0.4x | 1.1x | 1.2x | 8.6x | 10.6% |
AZO | $46.6B | 19.1x | 16.3x | 2.3x | 2.1x | 4.5x | 4.1x | 13.8x | 3.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DORM | $3.7B | 16.9x | 14.1x | 1.7x | 1.7x | 4.0x | 3.9x | 11.1x | 5.9% |
AAP | $2.8B | 64.3x | 17.0x | 0.3x | 0.3x | 0.8x | 0.8x | 15.5x | -10.5% |
GPC | $17.7B | 492.6x | 16.5x | 0.7x | 0.7x | 1.9x | 1.9x | 32.2x | 4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BGSI | $2.3B | 175.4x | 24.3x | 0.6x | 0.6x | 1.6x | 1.4x | 10.3x | 13.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ORLY | Revenue | +7.6% | +6.1% | +6.1% |
| EPS | +10.4% | +11.3% | +11.1% | |
LKQ | Revenue | −0.9% | +2.5% | −0.8% |
| EPS | −13.4% | +15.2% | +7.5% | |
AZO | Revenue | +8.1% | +7.5% | +7.1% |
| EPS | +2.8% | +16.0% | +11.8% | |
DORM | Revenue | +2.0% | +5.0% | +6.0% |
| EPS | −1.8% | +6.7% | +7.4% | |
AAP | Revenue | −6.0% | −0.3% | +2.5% |
| EPS | −624.9% | +52.8% | +42.6% | |
GPC | Revenue | +5.0% | +3.5% | +4.2% |
| EPS | +1.4% | +7.3% | +8.6% | |
BGSI | Revenue | +29.1% | +8.4% | +6.7% |
| EPS | +84.3% | +44.5% | +23.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
LKQ, which distributes recycled, salvage and aftermarket collision parts to repair shops in North America and Europe, told investors on July 30 that a new enterprise resource planning system at its German business cost it $140m of revenue and $50m of earnings before interest, taxes, depreciation and amortization in a single quarter. The part of the business the market had been braced for went the other way: North American organic parts and services revenue rose 0.5%, the first positive quarter in nine.
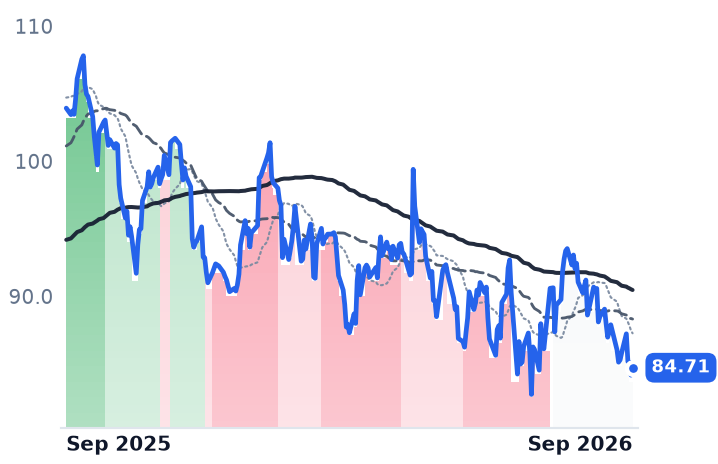
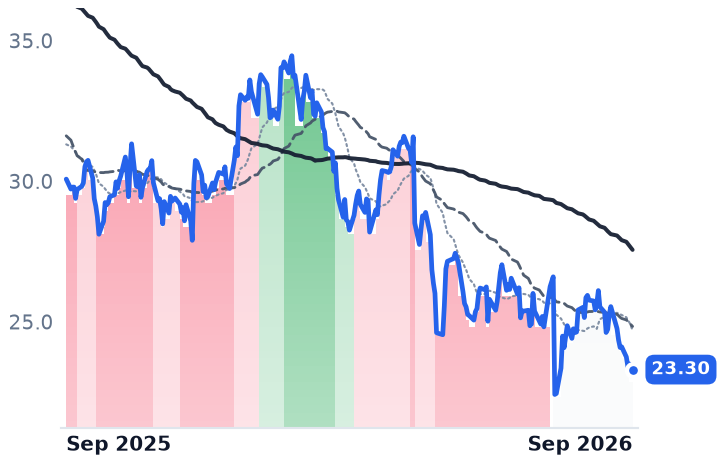
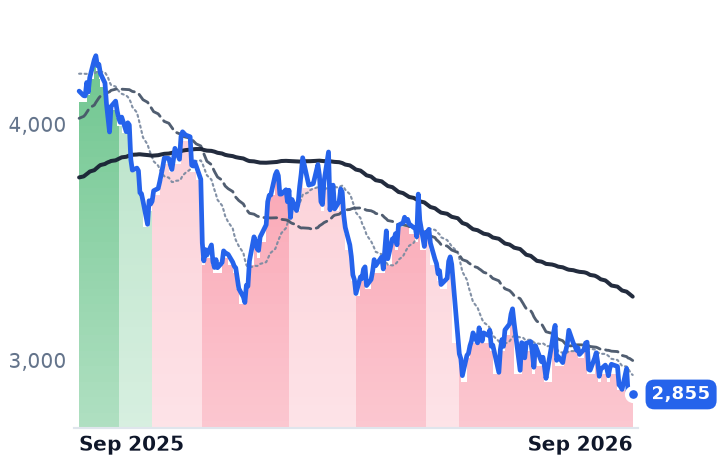
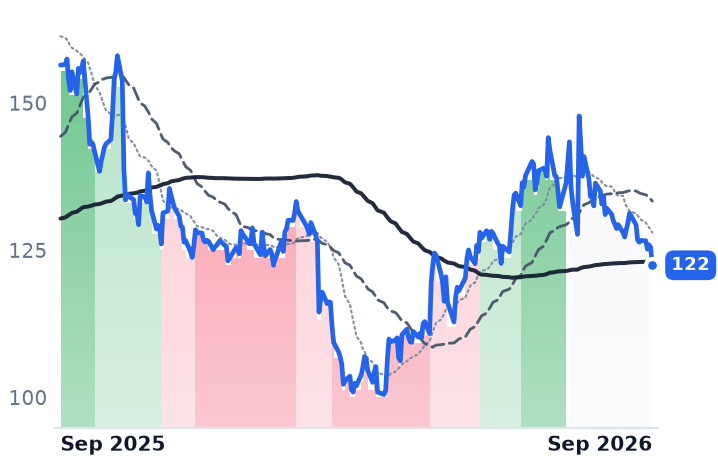
That inversion is the reason to stop pricing the aftermarket as one thing. Two different dollars fund it. One is retail — a part sold off a shelf to a driver or billed on account to an installer, at a gross margin near fifty cents. The other is insurance — a part that exists only when a carrier authorizes a repair instead of writing the vehicle off. Over twelve months both were marked down together: O'Reilly 19.6%, LKQ 26.1%, AutoZone 32.4%, Dorman 22.1%, with not one of them appearing on a 30-day list of biggest movers. The reasons do not rhyme.
The claim dollar stabilized; the software did not
LKQ's revenue fell 6.4% year on year to $3.41bn in the June quarter and operating income fell 27.9% to $225m, a fourth straight quarterly decline. Guidance was cut for the second time this year — adjusted earnings to $2.60–$2.90 a share from $2.90–$3.20, and organic parts and services growth to a range of -3.0% to -1.0% from the -0.5% to +1.5% set with the 2025 results. The shares fell 15.7% that session.
"While this quarter fell short of our expectations, this is a company that is stronger and better than reported results may suggest," chief executive Justin Jude said on the July 30 call, calling the German transition more challenging and slower to stabilize than planned. The claims meter behind the bear case improved: repairable claims ran down 1% to 3%, better than the prior quarter, while alternative-parts utilization hit a record above 40% as carriers push cheaper recycled and aftermarket parts into each authorized repair. Boyd Group, the collision-repair chain paid by those same carriers, told investors on August 12 that industry repair volumes were flat to down 2% and total losses flat year on year.
LKQ trades at 8.7 times forward earnings against 12.9 times trailing — the gap is the guidance cut, already embedded — at 0.92 times book value with a 10.6% trailing free-cash-flow yield. Its board opened a review of strategic alternatives on January 26, explicitly including a sale of the whole company.
The retail dollar is intact, and thinner than it looks
O'Reilly, which sells hard parts and maintenance items out of company-operated stores to both drivers and professional shops, reported comparable-store sales up 6.0% and raised full-year comp guidance to 4–6%. Gross margin was 51.45% against 51.41% a year earlier. "As we see inflation in acquisition costs in our industry is very rational in how we pass those through," chief executive Brad Beckham told investors on the second-quarter call. The shares fell 3.6% the next day.
The composition is where the risk sits. Professional sales rose about 10%, a fourth consecutive double-digit quarter. Do-it-yourself comps grew low single digits on a higher average ticket — and a low-single-digit decline in DIY transaction counts. Same-SKU inflation contributed 5.5%, which management expects to moderate to 1–2% in the second half as 2025's tariff-driven price increases lap. Meanwhile accounts payable covered 123.7% of inventory, down from 127.0%, with 122% guided for year-end: suppliers are financing slightly less of the same-day availability that is the moat.
What the price earned
O'Reilly's forward earnings multiple has fallen to about 25.8 times from roughly 34.6 times at last September's peak, still at the top of the 15-to-25 range it carried from 2016 to 2023. Consensus earnings for this year, at $3.29 a share, are up about 10% and have not been cut. A premium unwound; the earnings line did not break.
AutoZone is a different case: consensus profit of $150.85 a share is 2.8% above last year, a stalled line at 16.3 times forward earnings, with fiscal third-quarter gross margin down about half a percentage point that the company attributed principally to a non-cash inventory accounting charge. Dorman Products, the supplier that imports parts and actually pays the Section 232 duty, saw gross margin fall to 36.0% in the March quarter and rebound to 46.1% in June, with operating income up 40.9% on revenue up 0.7% — cost absorbed, then recovered — yet its shares are down 22.1% on flat estimates and 14.1 times forward earnings.
The split was dated on August 20, when Advance Auto Parts missed on revenue and blamed tighter household budgets in its do-it-yourself channel, its shares falling about 22% to $43.96 even as $26m of one-off tariff refunds flattered adjusted earnings. AutoZone fell 3.7% that day and O'Reilly 2.8%. LKQ closed up 0.3%.
So the verdict runs in two directions. LKQ's is a genuine earnings break with a named, geographic cause, priced below book while the claim pool it feeds steadied. O'Reilly's decline is the unwind of a 2024–25 rating rather than evidence of a damaged business — but the second half is a real test, because with pricing fading to 1–2% and DIY visits already shrinking, a 4–6% comp has to be carried almost entirely by professional installers.
One input runs only one way. The Section 232 tariff on imported auto parts took effect in May 2025, and a quarterly inclusions process lets domestic manufacturers petition to add parts to the list — with no comparable route to take one off.