

Target Hospitality Booked $1.7bn of Hyperscaler Beds; Government Work Is $13.5m a Quarter
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
A workforce-housing owner long read as a federal-contract proxy has quietly changed who pays it. Target Hospitality's Workforce Hospitality Solutions segment grew 142% year on year in the June quarter, to $36m, and is guided to more than half of 2026 revenue; the government segment ran at $13.5m in the same quarter.
On September 18 it added a roughly $250m hyperscaler contract through August 2030 and lifted full-year guidance to $435-445m of revenue and $105-115m of adjusted earnings before interest, tax, depreciation and amortization, up 22% at the midpoint from August. The contracted volume is real. The profits are not yet: June-quarter gross margin was 18.5% against 46.1% for full-year 2024, and the company posted a $9.0m net loss. Maximus, the actual government contractor, went the other way.
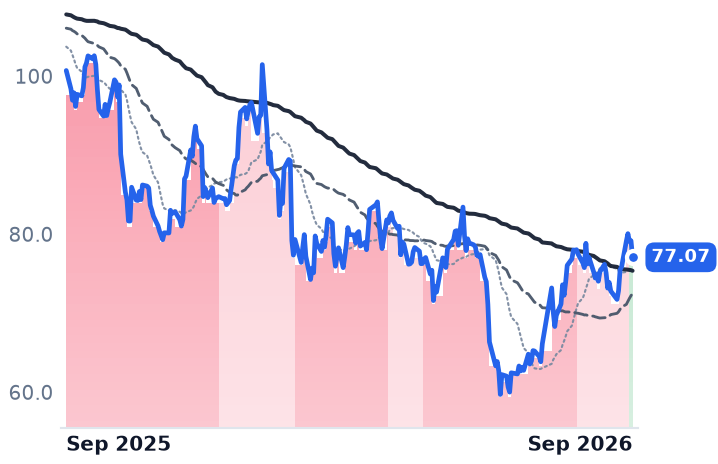
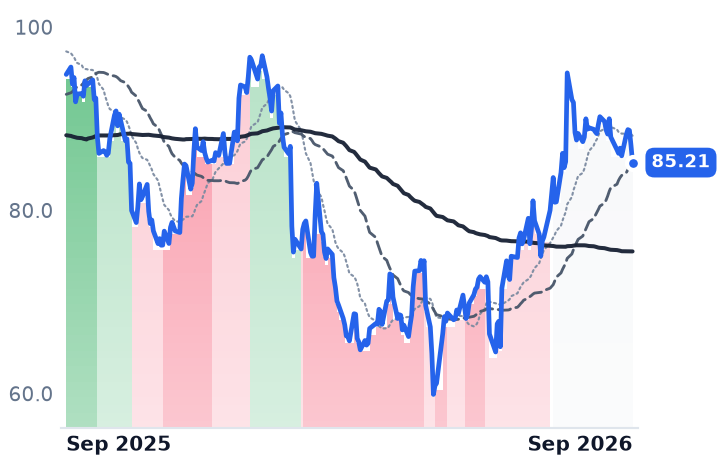
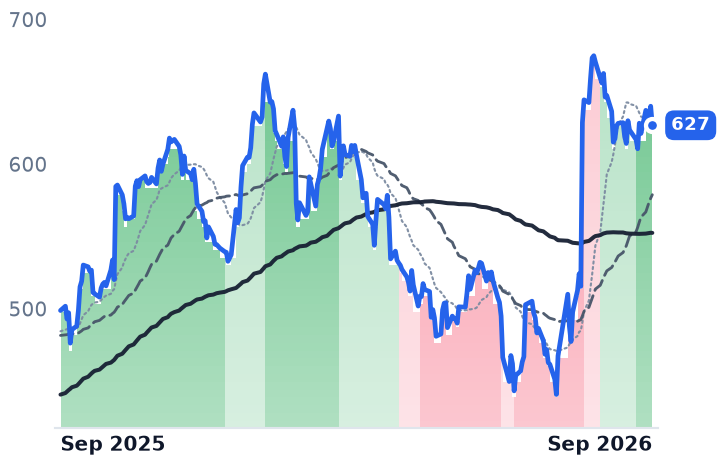
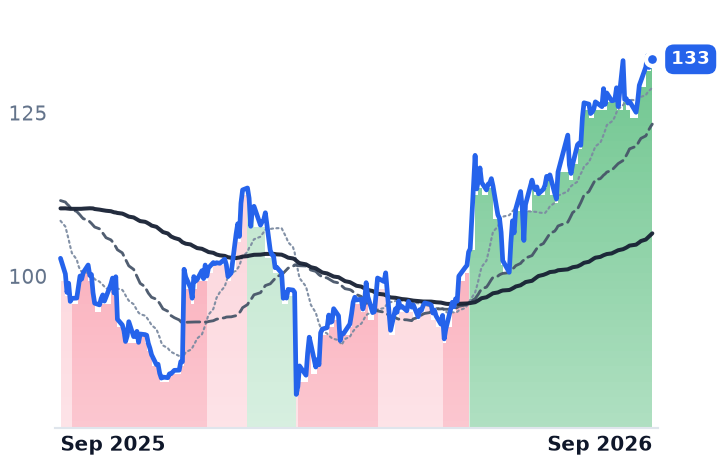
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
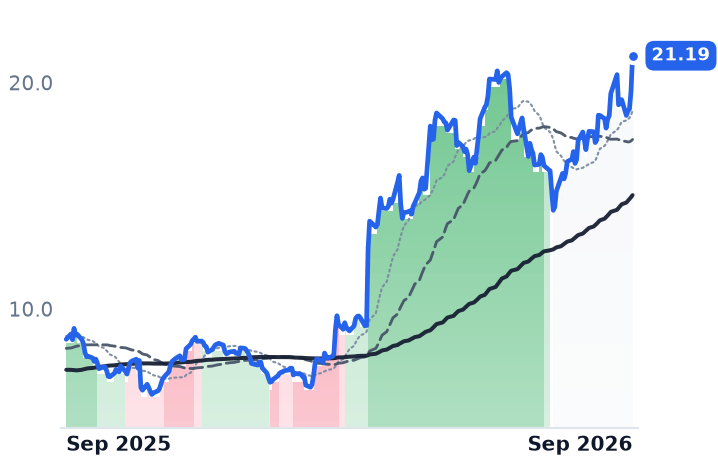
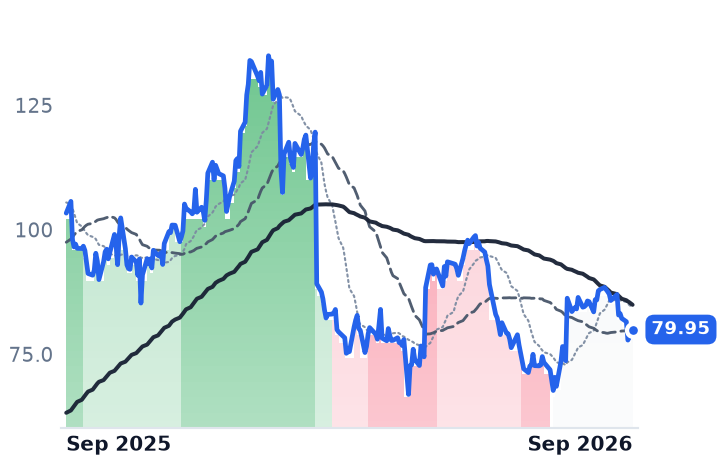
TH | Target Hospitality | Government & Workforce Services | 🟢 Cont. Bull | +21.0% | +144.7% |
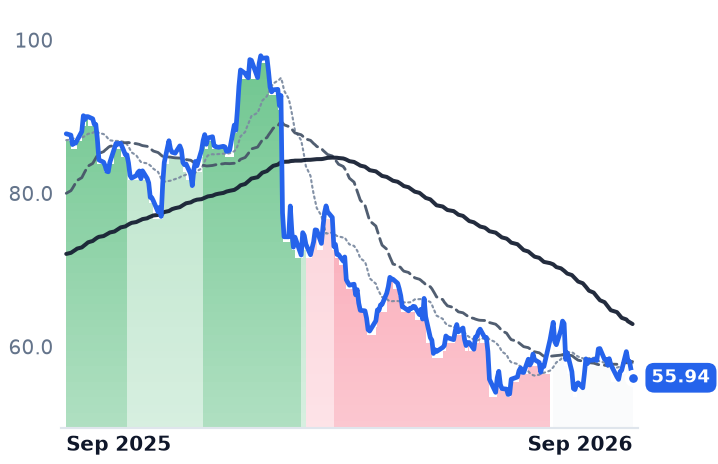
MMS | Maximus | Government & Workforce Services | ⚠️ Emerging Bear | −3.2% | −36.3% |
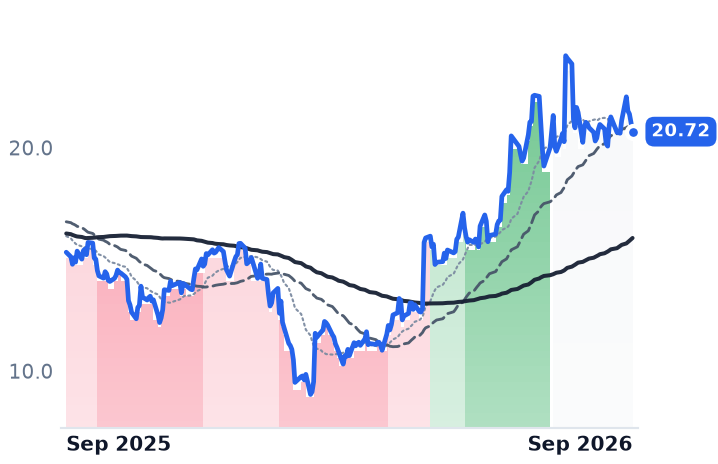
FA | First Advantage | Government & Workforce Services | 🌱 Emerging Bull | −1.6% | +35.2% |
| Compared against · context, not the story | |||||
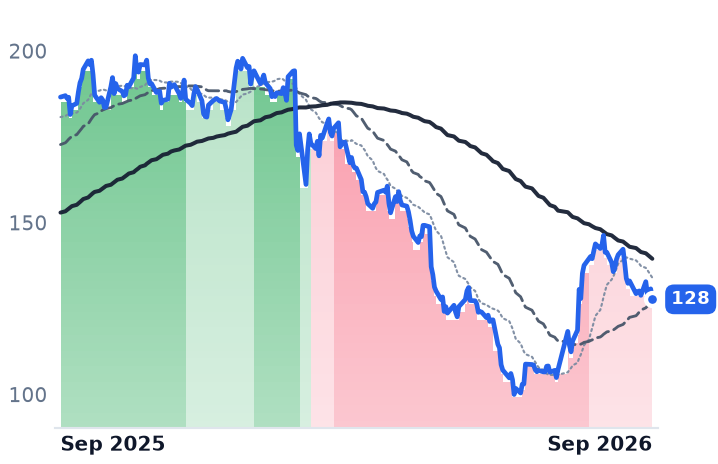
LDOS | Leidos | Defense & Government Solutions | ⚠️ Emerging Bear | −9.7% | −31.6% |
BAH | Booz Allen Hamilton | Government & Defense Consulting | 🔴 Cont. Bear | +1.1% | −23.5% |
ICFI | ICF International | Government & Defense Consulting | 🔴 Cont. Bear | −4.1% | −10.1% |
CACI | CACI International | Defense & Government Solutions | 🟢 Cont. Bull | −3.0% | +25.7% |
SAIC | Science Applications International | Defense & Government Solutions | 🌱 Emerging Bull | +5.5% | +29.6% |
WLDN | Willdan | Design & Engineering Consulting | ⚠️ Emerging Bear | −6.7% | −22.6% |
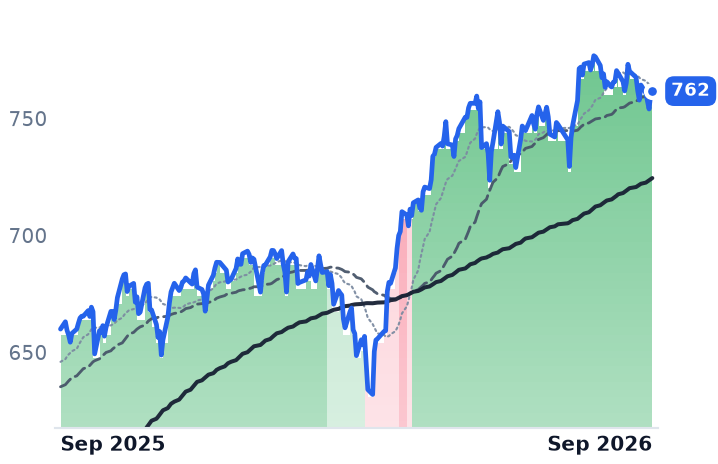
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +15.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TH | $2.1B | n/m | — | 6.1x | 4.8x | 83.0x | 65.6x | 66.8x | 4.2% |
MMS | $2.9B | 8.2x | 7.0x | 0.6x | 0.6x | 2.3x | 2.3x | 6.3x | 14.7% |
FA | $3.6B | 140.6x | 16.3x | 2.1x | 2.1x | 5.9x | 5.7x | 12.5x | 6.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LDOS | $16.8B | 12.4x | 10.8x | 1.0x | 0.9x | 5.5x | 5.3x | 9.9x | 12.9% |
BAH | $9.5B | 12.3x | 12.3x | 0.9x | 0.8x | 1.9x | 1.9x | 10.4x | 11.8% |
ICFI | $1.1B | 13.1x | 8.7x | 0.6x | 0.6x | 1.7x | 1.6x | 8.5x | 13.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CACI | $13.6B | 25.3x | 18.7x | 1.4x | 1.3x | 6.6x | 5.8x | 17.1x | 9.4% |
SAIC | $5.4B | 14.7x | 11.9x | 0.7x | 0.7x | 5.7x | 5.8x | 7.8x | 11.5% |
WLDN | $1.4B | 24.1x | 18.7x | 2.0x | 3.4x | 5.3x | 8.8x | 21.7x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TH | Revenue | +38.7% | +68.9% | +12.2% |
| EPS | −89.1% | −2666.7% | +32.7% | |
MMS | Revenue | −4.2% | +2.9% | +8.5% |
| EPS | +7.5% | +4.4% | +12.3% | |
FA | Revenue | +10.3% | +6.6% | +8.2% |
| EPS | +26.9% | +18.0% | +17.0% | |
LDOS | Revenue | +5.2% | +6.1% | +4.7% |
| EPS | +17.1% | +4.6% | +3.2% | |
BAH | Revenue | −6.1% | +0.7% | +4.2% |
| EPS | −4.3% | +5.1% | +5.1% | |
ICFI | Revenue | +2.0% | +5.4% | +8.7% |
| EPS | +3.7% | +9.4% | +7.0% | |
CACI | Revenue | +10.9% | +12.7% | +6.7% |
| EPS | +14.2% | +16.7% | +15.4% | |
SAIC | Revenue | −2.4% | +0.0% | +1.1% |
| EPS | +15.3% | +6.0% | +5.8% | |
WLDN | Revenue | +24.5% | +13.2% | +13.4% |
| EPS | +109.3% | +19.2% | +4.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Target Hospitality, which owns roughly 15,528 beds across 27 communities and rents them by the person to crews working in remote places, told investors on September 18 that a top-five hyperscaler will pay it about $250m through August 2030 to house roughly 1,100 people near a data-center development in the Pecos region of West Texas. The company says it can serve the contract by modifying under-utilized assets for less than $15m of capital.
That announcement, and the guidance raise that came with it — to $435-445m of 2026 revenue and $105-115m of adjusted EBITDA, from $410-420m and $85-95m guided in August — settles an argument about what this company is. It is no longer paid mainly out of appropriated federal funds. Its customer is data-center construction capital.
The mix flipped in about eighteen months
In the June quarter the Workforce Hospitality Solutions segment, which houses industrial and data-center construction crews, grew 142% year on year to $36m, with average utilized beds in that segment passing 4,000. Management guides it above half of consolidated 2026 revenue. Government revenue was $13.5m, up from $7.5m a year earlier on the reactivation of the Dilley, Texas community, whose contract runs to 2030 — growing in dollars, shrinking in mix.
Behind that sit three signings: more than $550m in North Texas on April 1, structured with a guaranteed minimum and extension options; a 48-month agreement announced May 11 expected to generate more than $750m housing about 3,370 people for AI infrastructure work; and the September contract. "Since January 2026, we have secured over 9,000 contracted beds, representing more than $1.4 billion of multiyear contracts," chief executive Brad Archer said on the August 10 call; with September's award the disclosed total exceeds $1.7bn.
The shares have followed the paper, not the quarters. Over twelve months Target Hospitality rose 146.7%, and the three largest up-sessions of that year — 36.4% on April 1, 17.9% on May 11, 8.0% on September 18 — each landed on a contract announcement.
What the contracts have not yet produced
Profit. June-quarter revenue rose 38.7% to $85.5m, but gross margin was 18.5% against 46.1% for full-year 2024, operating margin was negative, and the net loss was $9.0m. Full-year 2025 was the trough being measured against: revenue down 17.0% to $320.6m and a $37.1m loss. Capital spending guided at $490-510m for 2026 exceeds the entire guided revenue, funded by a $660m credit facility and by customers paying up front. "Year-to-date cash flows from operating activities exceeded $110 million and included more than $100 million of advance payments from customers," chief financial officer Jason Vlacich said on August 10. Net leverage was 0.6x at the June quarter; management expects to exit 2027 under 3x.
At 6.1 times trailing sales and 66.8 times trailing EV/EBITDA, the $2.11bn equity is not priced off what has been earned. It is priced off consensus 2027 revenue of $742m and $219m of EBITDA — about 9.6 times that 2027 figure — a ramp the company says its existing contracted portfolio alone supports, before any of a pipeline it puts above 20,000 beds.
The contractor that actually invoices Washington
Maximus, which runs Medicaid and marketplace eligibility, disability assessments and federal case management for governments, fell 37.3% over the same twelve months. Revenue has declined three straight quarters, down 5.1% in the latest, and the company cut fiscal 2026 adjusted earnings guidance to $7.90-8.20 a share after the Department of Veterans Affairs paused performance incentives on its medical disability exam program; it trades near 8.2 times trailing earnings against roughly 16.4 times a year ago. Operating margin still expanded, and U.S. Federal Services margin reached 18.6%.
So the year's move in workforce housing is not a re-rating of companies that bill the federal government — that trade went the other way. It is hyperscaler capital expenditure reaching a supplier small enough for it to matter, and the market has paid for the signature rather than the income statement. The gap between the two is the whole position.
The beds in Pecos are supposed to be occupied this quarter. That is the first of these contracts where revenue, not a press release, becomes checkable.