

CF Industries' Gas Cost Is Forecast to Rise About $1 in 2027, or $33 a Ton of Ammonia
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Two nitrogen and methanol producers are being paid for a cost advantage their own government's forecaster expects to shrink next year. CF Industries and Methanex both earn the gap between a globally traded product price set by Europe's gas-bound producers and the cheap American gas they burn, and both just printed their best quarters in years on it — CF widening gross margin to 51.5% from 44.8%, Methanex to 45.7% from 27.1% after three straight losing quarters.
The product side has already turned: urea is $443 a tonne, roughly half April's peak, and Methanex guided its July–August realized price down to $460–485 from $529. The cost side turns in 2027, when the Energy Information Administration expects Henry Hub near $4.60. Consensus already has CF's earnings per share falling 27.7% that year and Methanex's 39.3%.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CF | CF Industries | Nitrogen Fertilizers | 🟢 Cont. Bull | +1.7% | +51.8% |
MEOH | Methanex | Basic Chemicals & Intermediates | 🟢 Cont. Bull | +3.3% | +58.6% |
| Compared against · context, not the story | |||||
LXU | LSB Industries | Basic Chemicals & Intermediates | ⚠️ Emerging Bear | +2.8% | +34.0% |
NTR | Nutrien | Fertilizer Distribution & Retail | ⚠️ Emerging Bear | +5.6% | +37.2% |
MOS | The Mosaic | Phosphate & Potash | 🔴 Cont. Bear | +5.4% | −26.7% |
IPI | Intrepid Potash | Phosphate & Potash | 🔴 Cont. Bear | −0.9% | +32.7% |
UAN | CVR Partners | Nitrogen Fertilizers | 🟢 Cont. Bull | +7.9% | +58.9% |
EQT | EQT | Appalachian Shale Gas | ⚠️ Emerging Bear | −7.9% | +2.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −0.2% | +15.4% |
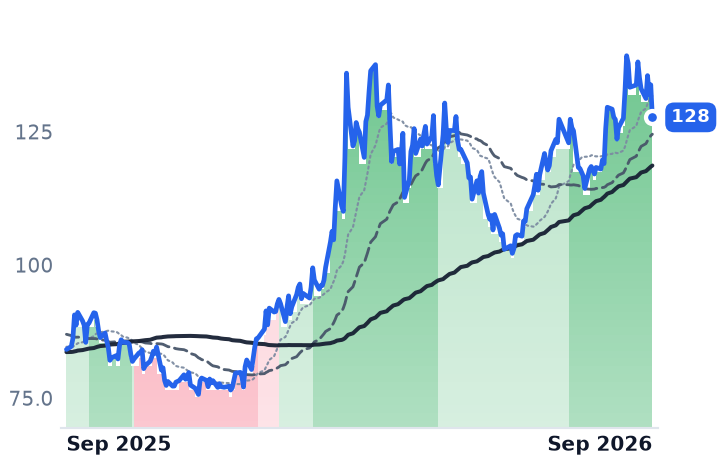
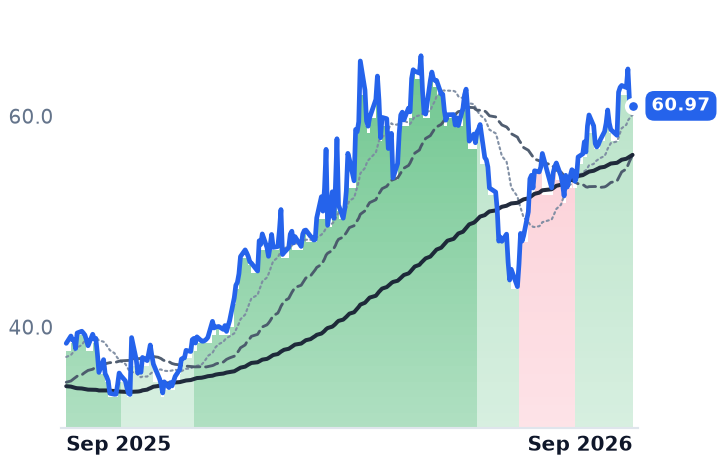
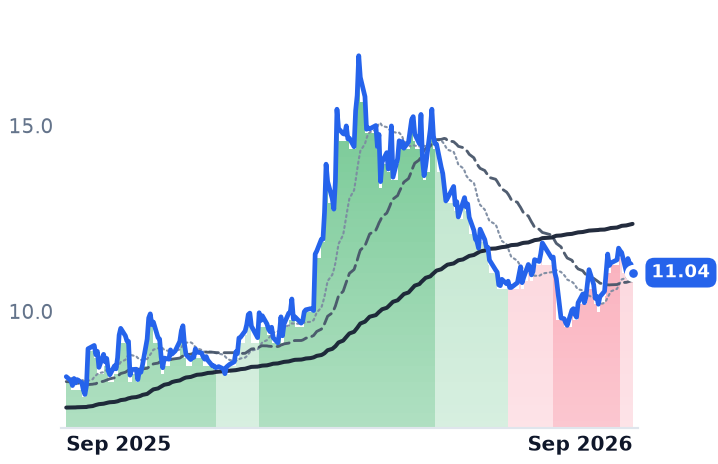
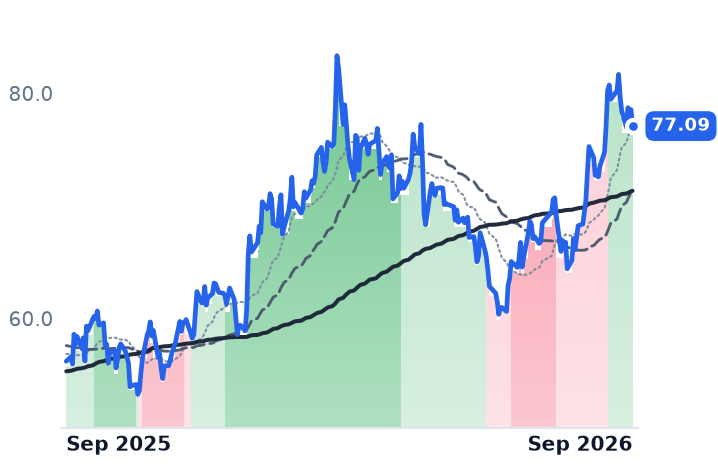
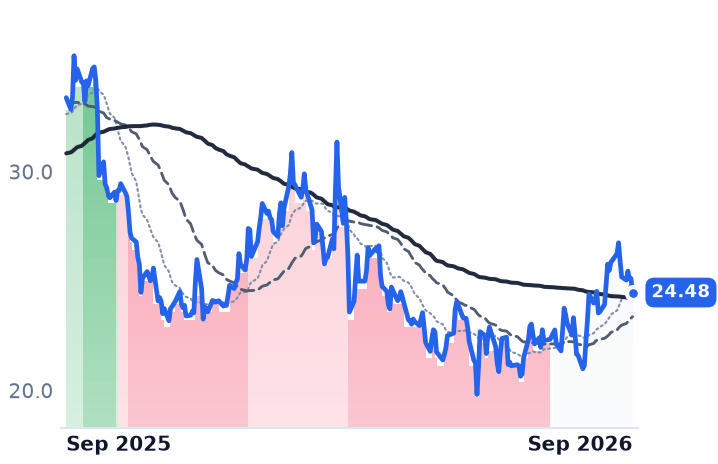
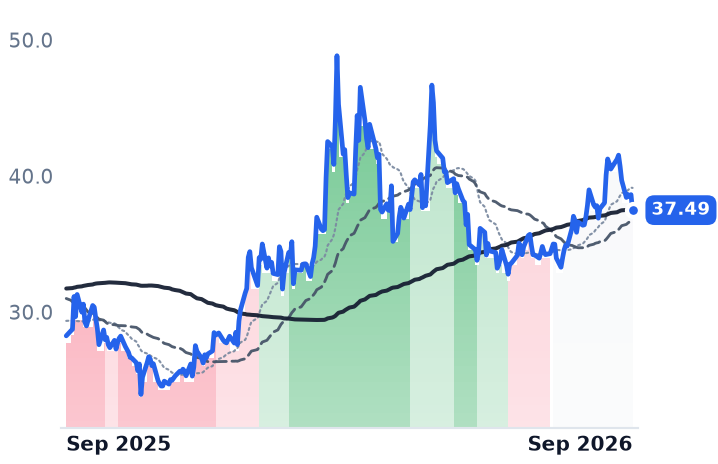
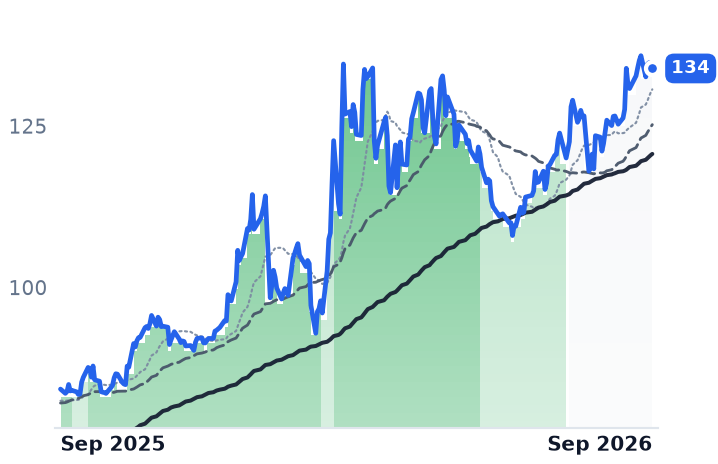
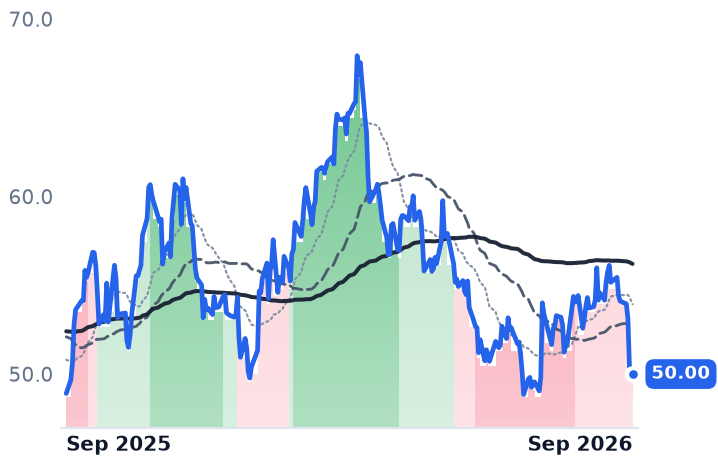
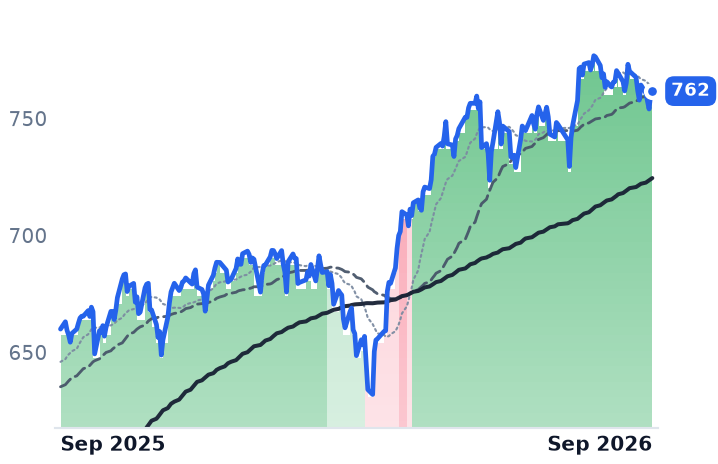
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CF | $19.6B | 9.4x | 8.5x | 2.5x | 2.4x | 6.0x | 5.7x | 5.3x | 9.7% |
MEOH | $4.7B | 54.5x | 6.7x | 1.1x | 1.0x | 3.9x | 3.4x | 7.4x | 15.7% |
LXU | $795.6M | 22.2x | 18.5x | 1.2x | 1.2x | 7.0x | 7.0x | 8.3x | 20.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NTR | $37.0B | 15.6x | 15.6x | 1.3x | 1.3x | 4.2x | 4.3x | 7.7x | 5.7% |
MOS | $6.9B | 9.5x | 18.4x | 0.6x | 0.5x | 4.1x | 3.9x | 4.0x | -7.1% |
IPI | $562.2M | 39.3x | 33.4x | 1.9x | 2.3x | 10.2x | 12.7x | 7.9x | 7.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UAN | $1.4B | 11.3x | — | 2.1x | — | 8.4x | — | 6.8x | 8.2% |
EQT | $33.8B | 11.9x | 13.3x | 3.6x | 3.6x | 5.3x | 5.3x | 6.3x | 11.2% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CF | Revenue | +16.5% | −10.6% | −5.0% |
| EPS | +68.3% | −27.7% | −20.0% | |
MEOH | Revenue | +32.6% | −18.6% | −3.4% |
| EPS | +202.6% | −39.3% | −24.3% | |
LXU | Revenue | +9.8% | −3.3% | −0.5% |
| EPS | +73.2% | +23.0% | +7.4% | |
NTR | Revenue | +5.2% | −1.3% | −1.1% |
| EPS | +6.8% | −0.3% | −8.0% | |
MOS | Revenue | +7.5% | −0.7% | −1.2% |
| EPS | −53.0% | +65.0% | +1.6% | |
IPI | Revenue | −4.8% | −3.9% | −0.1% |
| EPS | +8.4% | −54.5% | −34.3% | |
EQT | Revenue | +11.3% | −1.1% | +11.4% |
| EPS | +38.2% | −5.5% | +38.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
CF Industries, North America's largest nitrogen fertilizer maker, closed at a twelve-month high of $139.27 on September 2. By then the granular urea it sells had lost about half its value since April, easing to $443 a tonne from $935 as China's exports resumed and Strait of Hormuz fears faded. The rally that carried the shares to that high was not a fertilizer-price rally. It was a gas rally — someone else's gas.
That distinction is the whole stake. CF is paid the gap between a global ammonia and urea price set at the marginal European producer's cost and the Henry Hub gas it burns. Dutch TTF gas reached €78.71 a megawatt-hour on September 9, up 136% on the year after Qatar's force majeure, and European ammonia capacity is cost-bound: when TTF rises, those plants idle and the region buys from the Gulf. CF's own cost, meanwhile, is forecast to move the wrong way. The Energy Information Administration expects Henry Hub to rise from just under $3.50 an MMBtu in 2026 to just under $4.60 in 2027 as Plaquemines, Corpus Christi Stage 3 and Golden Pass add 1.7 billion cubic feet a day of liquefied-natural-gas feed demand. CF's 10-K sensitivity puts a $1.00 move at roughly $33 on the cost of a ton of ammonia and $22 on a ton of urea.
The year was two rallies, and the first one is gone
CF's twelve-month gain of 51.8% was no grind. The shares were down 6.4% by mid-December. Then two sessions after US and Israeli strikes on Iran — March 11 and 12, up 9.2% and 13.2% — delivered $25.95 of the year's $43.60 point gain. That product-price rally has fully round-tripped: over six months CF is up 0.8%, Nutrien down 1.0%, LSB Industries down 26.4%. What is standing is a second, cost-side move dating from mid-June, worth 24.1% at CF and 14.6% at Methanex.
The businesses earned it. CF grew June-quarter revenue 17.6% to $2.22bn and lifted net income 88.3% to $727m; diluted shares fell 5.6%, so buybacks account for roughly a ninth of the near-doubling in earnings per share and the spread did the rest. "Higher global capital costs have structurally raised the incentive price required for new global nitrogen capacity," chief executive Christopher Bohn told investors on the August 6 call. "This is before we factor in any geopolitical premium."
Methanex, the world's largest methanol supplier, swung harder: revenue up 75.2% to $1.40bn, operating income up 356%, on a realized $529 a tonne against $351 in the first quarter and a record 1,027,000 tonnes from Geismar. Only Geismar buys American gas; its Trinidad, Egypt, New Zealand and some Chilean contracts are indexed to the methanol price itself, which cushions the downside and caps the upside — and there the binding constraint is availability rather than price. Methanex idled the 860,000-tonne Titan plant indefinitely on June 29 after failing to agree a gas contract, taking a $115m impairment.
The same gas, two different outcomes
LSB Industries, which makes ammonia and ammonium nitrate in Oklahoma off the identical Henry Hub feedstock, grew revenue 11.1% and watched gross margin collapse to 6.8% from 15.3%, with operating income negative. It carries the group's dearest forward multiple at 18.5x. Cheap gas is necessary and nowhere near sufficient. Nutrien's 37% year, for its part, came from record potash volumes and retail while its first-half nitrogen volumes fell 7%.
CF at 8.5x forward earnings looks cheap only because "forward" means 2026. Consensus has 2027 earnings per share falling 27.7% to $10.84, which is 11.8x today's price, and revenue down 10.6%. The nineteen-analyst average target of $126.11 now sits below the close; Freedom Broker cut the stock to Hold, noting nitrogen prices had returned to pre-conflict levels by June. Methanex trades at 6.7x its 2026 consensus and 11.0x 2027, with a 15.7% trailing free-cash-flow yield and leverage near three times EBITDA that has deferred buybacks — the cheaper peak year, and the one whose multiple has compressed while the shares rose.
The verdict the numbers support: the June quarters are real and the cost advantage is real, but the part of this year still standing rests on European gas staying expensive through a winter, while the consensus underneath both stocks already assumes it does not last. Methanex has told the market the reversion has started, guiding July and August realized methanol to $460–485. CF has not yet had to.
On September 18 the whole complex fell — CF 4.6%, Mosaic 2.6%, Intrepid Potash 3.0% — while the S&P 500 rose, on volumes two to three times normal in a quadruple-witching and index-rebalance session. No company news was discoverable, so mechanical flow is the likelier reading. The date that matters is the next quarterly report, when the gas line inside cost of sales speaks for itself: $3.37 an MMBtu bought CF a 51.5% margin in June, and $4.57 bought it 37.6% three months earlier.