

Modine Spins Off Its Truck-Cooling Half October 1 After Data-Center Margin Fell to 14.8%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.6
Modine gives away roughly a third of its revenue in under two weeks and keeps the half the market is arguing about. Its Data Centers segment sold $348.6m of cooling in the June quarter, up 90% from a year earlier, but segment profit grew less than a third as fast and group operating income went backwards.
Management then reaffirmed full-year adjusted EBITDA growth above 40% after a first quarter that delivered 5% — arithmetic that requires roughly 52% across the three quarters left. Demand is not what deteriorated: a hyperscale customer prepaid $165m to reserve factory capacity. AAON, running the same playbook one state over, has raised its sales guidance twice this year and cut its gross-margin guidance both times.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
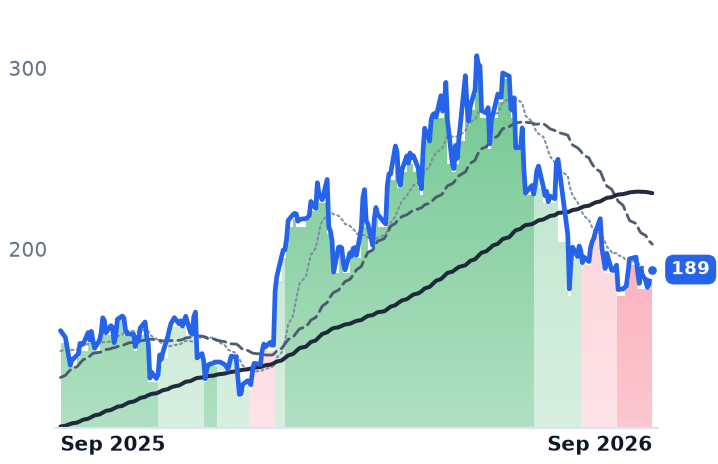
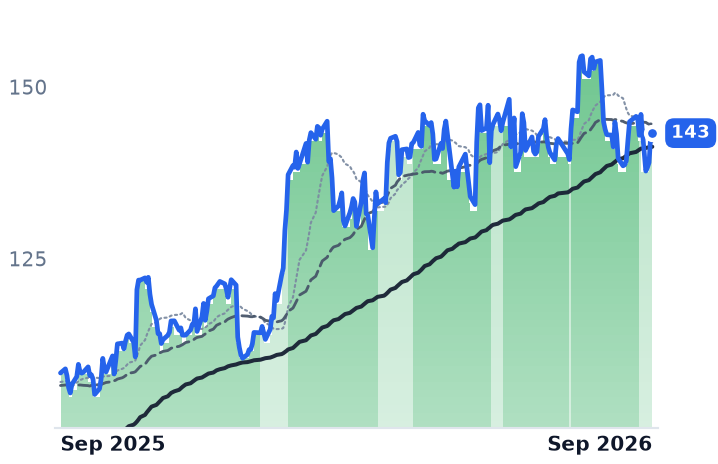
MOD | Modine Manufacturing | Thermal & Powertrain Components | ⚠️ Emerging Bear | −0.3% | +21.8% |
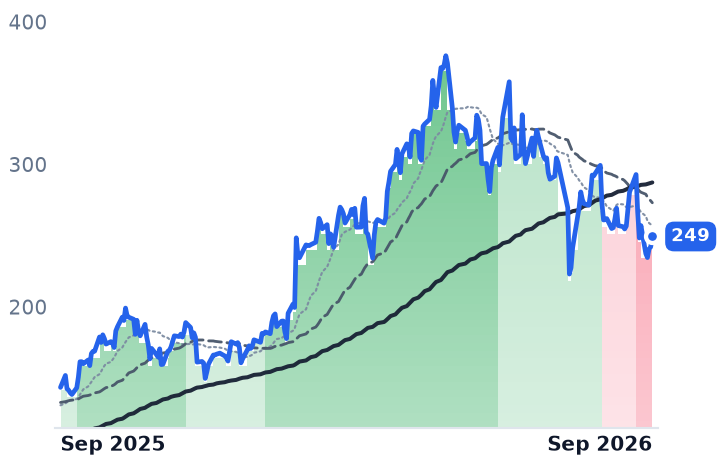
AAON | AAON | HVAC Systems | ⚠️ Emerging Bear | −5.0% | −16.0% |
| Compared against · context, not the story | |||||
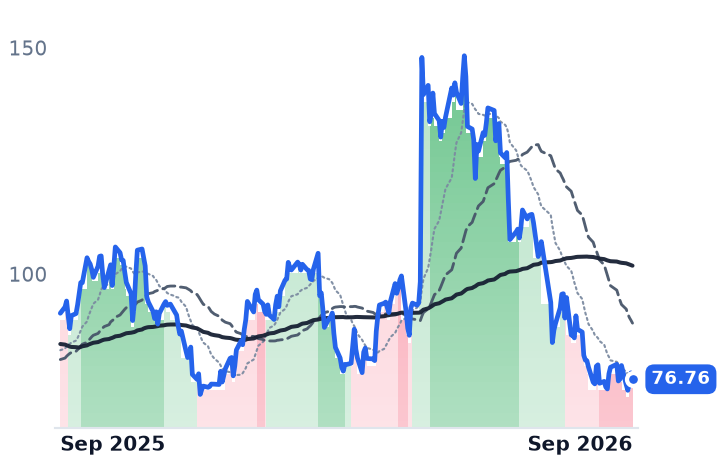
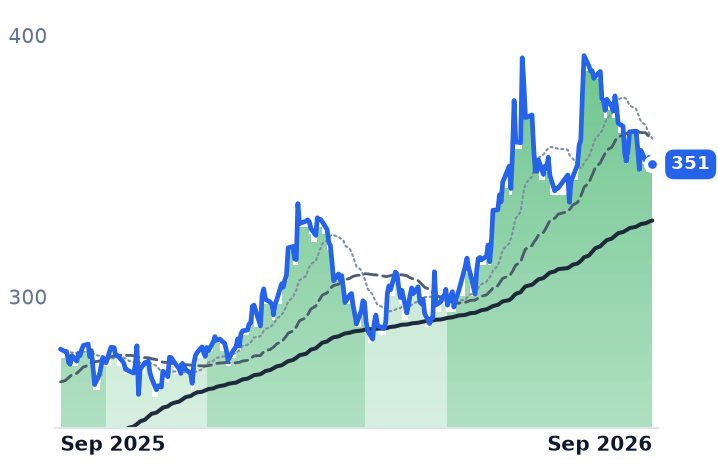
TT | Trane Technologies | HVAC Systems | 🟢 Cont. Bull | −4.9% | +5.8% |
CARR | Carrier Global | HVAC & Refrigeration | 🔴 Cont. Bear | −10.2% | −10.1% |
JCI | Johnson Controls International | HVAC & Refrigeration | 🟢 Cont. Bull | −0.4% | +32.2% |
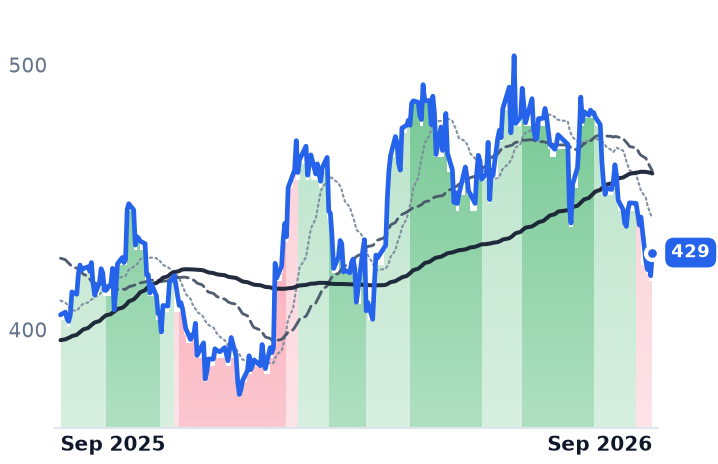
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −4.5% | +73.8% |
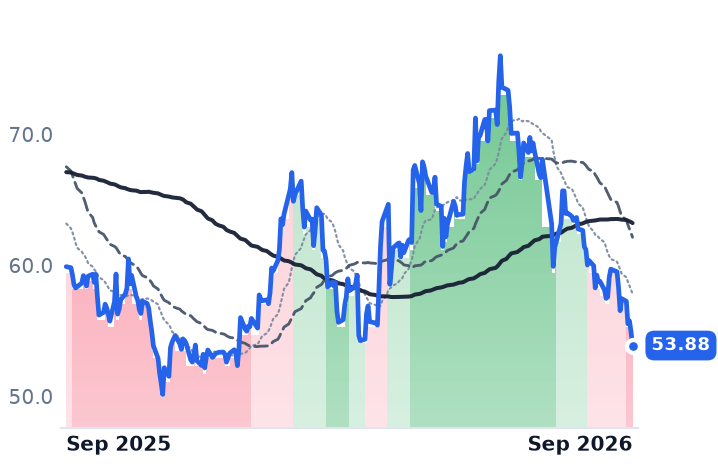
WTS | Watts Water Technologies | HVAC & Refrigeration | 🟢 Cont. Bull | −5.6% | +25.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOD | $10.0B | 70.7x | 25.1x | 3.0x | 2.5x | 13.4x | 11.1x | 35.0x | 1.0% |
AAON | $6.3B | 39.6x | 32.6x | 3.3x | 2.7x | 12.7x | 10.7x | 21.1x | -1.9% |
TT | $94.4B | 32.4x | 28.1x | 4.3x | 4.0x | 12.0x | 11.2x | 22.5x | 4.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CARR | $44.4B | 37.1x | 18.6x | 2.0x | 1.9x | 8.3x | 7.9x | 20.2x | 4.3% |
JCI | $87.1B | 24.9x | 28.4x | 3.5x | 3.4x | 9.5x | 9.3x | 26.6x | 2.3% |
VRT | $100.8B | 58.0x | 39.0x | 8.8x | 7.2x | 23.4x | 19.2x | 40.1x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WTS | $12.5B | 32.6x | 29.1x | 4.7x | 4.4x | 9.5x | 9.0x | 20.2x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MOD | Revenue | +22.6% | +29.0% | +22.3% |
| EPS | +33.4% | +45.0% | +45.5% | |
AAON | Revenue | +64.8% | +16.9% | +13.3% |
| EPS | +67.0% | +50.4% | +29.1% | |
TT | Revenue | +11.7% | +9.1% | +8.8% |
| EPS | +17.3% | +15.0% | +15.5% | |
CARR | Revenue | +5.9% | +4.8% | +5.2% |
| EPS | +11.2% | +13.9% | +12.8% | |
JCI | Revenue | +8.8% | +7.8% | +7.6% |
| EPS | +36.2% | +19.0% | +17.1% | |
VRT | Revenue | +37.0% | +29.7% | +21.9% |
| EPS | +62.8% | +36.4% | +27.1% | |
WTS | Revenue | +16.7% | +6.2% | +5.1% |
| EPS | +24.5% | +9.8% | +8.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Modine Manufacturing stops being half a truck-parts company on October 1. The Racine, Wisconsin heat-exchanger maker is handing its Performance Technologies arm — powertrain and battery cooling sold to truck, bus, agricultural and construction manufacturers — to Gentherm in a tax-free spin-and-merge, with a record date of September 28 and Gentherm shareholder approval already secured on September 10. Modine holders keep about 40% of the combined vehicle company, and the remainder will ask to be renamed Modexus Solutions.
What survives is the business everyone said they wanted — data-center cooling and commercial heating and air conditioning — and it has been marked down by more than a third since June. The reason sits inside the June quarter, and it is not an order problem.
Volume doubled, profit did not follow
Group sales rose 28% to $874.1m in the quarter ended June, and group operating income fell 1.2% to $74.8m. The Data Centers segment — Airedale chillers, precision air conditioning, coolant distribution units — sold $348.6m against $183.7m a year earlier, a 90% increase on North American hyperscale demand, close to 40% of the whole company. Segment adjusted earnings before interest, taxes, depreciation and amortization rose 27%. That gap is a margin: 14.8%, against 22.1% a year earlier.
Chief executive Neil Brinker blamed supply-chain constraints flagged a quarter earlier, which he said limited production and temporarily reduced data-center margins. On the remedy — locking in volume with existing partners and qualifying additional suppliers — he added in the July 29 release: "These initiatives are yielding positive results, driving sequential volume and margin improvements as the quarter progressed."
The half being sold is not the drag, and neither is the other half staying. Commercial HVAC grew 22% to $261.6m. Performance Technologies, at roughly $264m of the quarter, leaves at about $1bn, near 6.8x trailing EBITDA, plus $210m of cash to Modine.
The number the price is arguing with
Modine left its fiscal 2027 guidance untouched: 20% to 35% revenue growth and adjusted EBITDA growth in excess of 40%. The first quarter delivered 5%, to $106.5m. Against roughly $456m last year, the guide implies more than $638m — leaving over $532m to be earned in three quarters that produced about $349m a year ago, roughly 52% growth. That arithmetic, rather than any wobble in AI spending, is what a 36.5% three-month decline is disputing.
Demand is contracted and partly prepaid. In May, Modine reserved capacity for more than $4bn of Airedale product through 2029 for one data-center customer, who paid $165m upfront to fund the factories. Two hyperscalers already make up the majority of data-center revenue.
The shares now fetch 13.41x trailing gross profit, against 17.96x in early May, with market value down to $10.02bn from $12.31bn. Forward earnings of 25.1x rest on consensus assembled while Performance Technologies was still inside the company, which ends in under two weeks.
The same trade, one state over
AAON, the Tulsa maker of semi-custom rooftop units whose BasX division builds custom air handlers and data-center cooling plant, is running the identical experiment. June-quarter revenue rose 101% to $627m, BasX sales tripled and total backlog nearly doubled to about $2.0bn. It has raised 2026 sales guidance twice, to 55–60% growth, and cut gross-margin guidance both times, to 25–26%. Overhead at its new Memphis plant ran $18.1m in the quarter against $3m a year earlier. AAON trades at 12.73x trailing gross profit, from 18.35x in May, and its shares are down 43.9% in three months.
What the fall earns
Part of this is paid for. Both companies are absorbing the cost of capacity before the revenue it carries, and Modine's segment margin fell more than seven percentage points while it did — a disclosed deterioration, whatever the order book says. The rest is borrowed from elsewhere: a July credit scare around AI tenants, a 30-year Treasury yield at a 19-year high in August, and the September 14 session when AI-slowdown warnings hit hardware names and liquid-cooling shares fell about 8%. Those repriced the payback period on factories being built today, which is precisely what a prepaid capacity agreement is meant to insulate.
After October 1 there is nowhere for a bad cooling quarter to hide. The vehicular business that smoothed Modine's results for a century leaves with the spin, and the next report is a pure reading on whether the chillers get built at the margin the guidance assumes.